admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
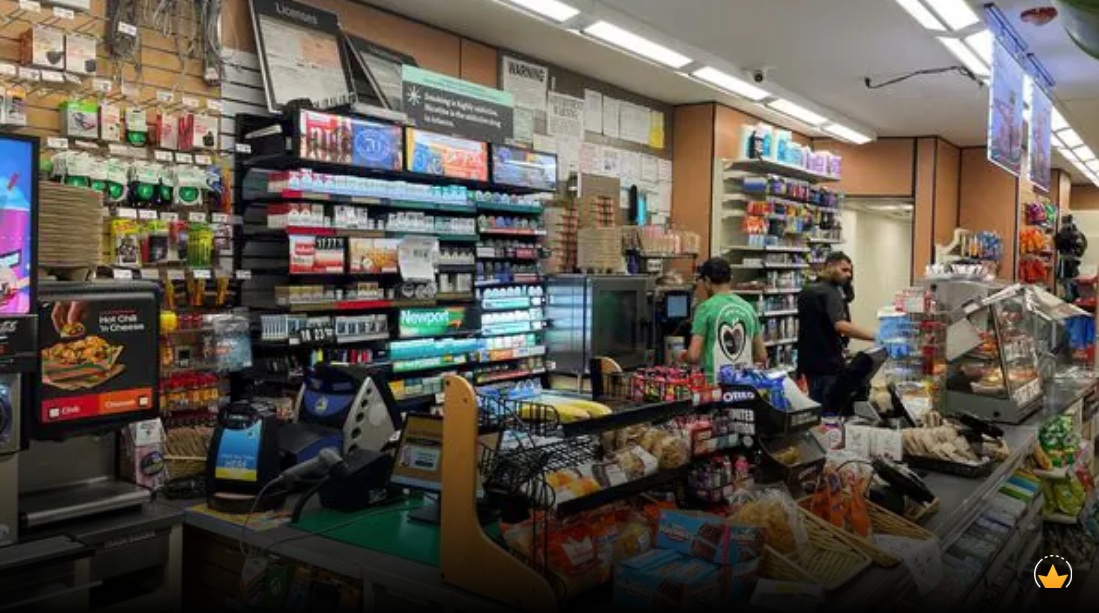
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
June 12, 2026
Aanya Thakur & Writankar Mukherjee, Economic Times
12 June 2026, Mumbai/Kolkata
India’s leading retail chains have seen the share of e-commerce in total sales either remain flat or edge up by a sluggish 1-2 percentage points over the past four-five years despite a sustained push towards omnichannel retailing.
An ET analysis of eight major retailers-market leader Reliance Retail, Shoppers Stop, Westside, Arvind Fashions, DMart, Spencer’s Retail, Pantaloons and Bata-showed that the contribution of e-commerce to overall revenue has seen minuscule improvement since 2021-22 even as online sales continue to increase in absolute terms. By contrast, the Covid-19 pandemic spurred explosive growth, with the share of digital sales in total revenue surging three to four times in 2020-21 and 2021-22.
Industry executives attribute the slowdown partly to lower investment levels compared with pure-play digital firms such as Amazon, Flipkart, Swiggy and Blinkit-parent Eternal. Besides, retailers have consistently maintained that they will not pursue online growth at the expense of profitability, keeping prices largely aligned across online and offline channels.
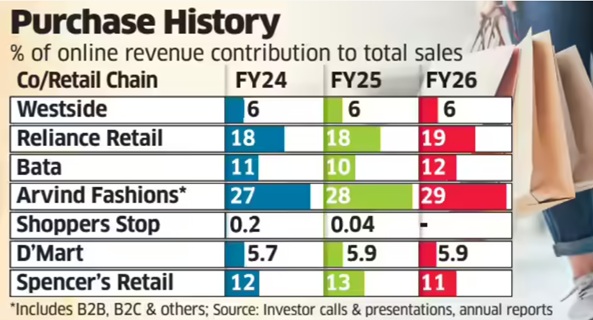
The ET study found Tata-owned Westside’s online contribution stood at 7% in 2021-22 and thereafter remained around 6% till 2025-26. Reliance Retail’s online share ranged between 17% and 19% during the period, while Bata’s remained at 10-12%.
For DMart, e-commerce accounted for 5-6% of sales, while Shoppers Stop’s online arm, Shoppers Stop.Com (India) Ltd, contributed less than 1% to the consolidated revenue between 2021-22 and 2024-25. The company has not disclosed 2025-26 online sales figures yet.
“The DNA of these retailers is rooted in the physical world-infrastructure, processes and systems are not inherently designed for e-commerce, which requires a different operating model,” said Devangshu Dutta, chief executive of consultancy Third Eyesight.
“Most retailers calling themselves omnichannel are effectively multi-channel. Online retail is capital-intensive and hyper-competitive. Given the significant scope for physical store expansion, especially in tier-2 and tier-3 cities, retailers are reluctant to invest aggressively online,” he said.
Even so, Avenue Supermarts, which runs DMart, invested Rs 150 crore in online grocery platform DMart Ready this week, following a Rs 174-crore infusion a year earlier.
By comparison, Eternal infused Rs 2,600 crore into Blinkit in 2025 and another Rs 450 crore in March this year. Similarly, Swiggy approved a Rs 1,000-crore investment in supply-chain subsidiary Scootsy last year as both companies expanded their dark-store networks.
The chief executive of Aditya Birla-owned departmental chain Pantaloons, Sangeeta Tanwani, recently told analysts that online sales accounted for just 3-4% of the business. She said the company had earlier refrained from investing in the channel because profitability remained elusive.
“But over the last year, we called out omnichannel as one of our priorities… The reason why we had paused that business was because we wanted to make sure that we can get the unit economics right and make this business profitable… With all the shifts we have made this year, we feel confident of scaling up this business,” Tanwani said.
Reliance Retail, meanwhile, reported lower earnings before interest, taxes, depreciation and amortisation (EBITDA) margin growth in both the January-March quarter and entire 2025-26 as investments in quick commerce weighed on profitability. Chief financial officer Dinesh Taluja recently told analysts that margins depend on the pace at which online and business-to-business segments grow relative to the core offline business.
“If we slow down online growth, margins will improve. It is a mix as far as the online business continues to grow faster,” he had said.
An industry executive said the online contribution may go up modestly in this financial year due to high investment in scaling up dark stores for quick commerce.
Queries emailed to Reliance Retail did not elicit a response till press time. The company had in December last year appointed former Flipkart executive Jeyandran Venugopal as its new chief executive for the retail business.
(Published in Economic Times)
admin
June 12, 2026
Christina Moniz, Financial Express/Brand Wagon
12 June 2026
Legacy luggage brand VIP Industries is shedding some of its old baggage. The company, which manufactures Skybags and Aristocrat along with its flagship VIP range, has gone beyond cringey makeovers solely to attract Gen Z, and has embarked on a transformation journey that leverages its legacy to purvey a fresh range of offerings.
The company is modernising its digital presence and supply chain to catch up with competitors.
Managing director Atul Jain admits that the company has been a bit slow on the e-commerce front. It is reinventing its online store, while also making its products available across other e-commerce channels. “Quick commerce is becoming an important channel since there are several use occasions and segments within the luggage market. For instance, consumers often make last-minute purchases for a weekend trip via quick commerce. School bags and backpacks for kids, also great gifting options, are seeing good demand on these platforms,” he says
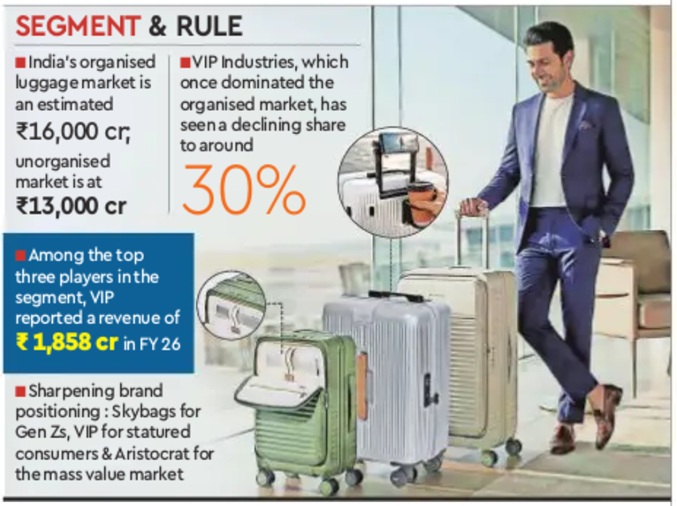
The company, which once dominated the ₹16,000 crore organised luggage market in India, saw a bit of a shakeup last year when the Piramal family sold 32% of its stake to a private equity firm. But it continues to be among the top three players in the category with a 29-30% market share. “Luggage plays the role of a traveller’s companion. We are creating designs to fit that role,” says Jain. “For example, our new VIP suitcases have a coffee cup holder and our cabin trolley bag has an easy access compartment for devices like laptops and iPads.”
The transformation goes beyond the product. VIP’s 350 exclusive physical retail touchpoints in the country are being revamped to offer a new customer experience.
Unpacking opportunities
Overits 55 years, VIP has grown from a briefcase brand into Asia’s largest luggage maker, housing labels like Skybags, Aristocrat, and Carlton (premium segment). While VIP is a premium offering targeted at business and travellers, its Aristocrat brand operates in the mass market and the budget-friendly Alfa targets consumers who typically shop in the unbranded segment. Aristocrat and Alfa together contributed upwards of 40% to the company’s revenue in FY25, followed by Skybags (28%) and VIP (20%).
Like many legacy brands, the VIP Industries’ faces the challenge to ia, stay relevant among Gen Z buyers as a plethora of digital-first brands swamp the market. “VIP has lost ground on relevance and desirability to a generation for whom luggage, like sneakers, is an expression of identity. To them, VIP feels like their parents’ brand,” says Nisha Sampath, managing partner, Bright Angles Consulting. D2C players in the category operate in the business of “lifestyle accessories” and not for “luggage” per se, she points out.
With a design-forward approach, incorporating features like compression systems, silent wheels and charging ports, these new-age brands have embedded themselves in travel “culture”, while also being Instagram worthy, say experts.
Jain says Skybags is VIP’s Gen Z focussed brand, which has over 8,20,000 Instagram followers. “We are sharpening our positioning for Skybags in our design, advertising and marketing outreach, especially on social platforms. The brand has a clear differentiation with youthful colours and prints to attract younger consumers,” he adds.
While D2C players have seen notable growth in recent years, they don’t have the kind of trust and brand equity that VIP has cultivated across its brands, nor do they have the scale or revenue that legacy brands have, he says.
Experts believe there is a significant growth opportunity for legacy players given that the unbranded market still accounts for ₹13,000-14,000 crore. The important lever for legacy brands is to clearly demonstrate value beyond price. “The unorganised market competes heavily on affordability, so organised players need to communicate durability, warranty, after-sales service, and consistent quality – areas where they have a strong inherent advantage over unorganised alternatives,” says Praveen Govindu, partner at Deloitte India. He adds that these brands should also invest in advertising and communicate this value to the end consumer.
Not only are the needs different among different consumer groups, competitive pressures are also diverse. “VIP can segment the market more cleanly with its portfolio of brands if it maintains absolute distinction to ensure clear consumer targeting across not just product attributes and pricing, but also communication and channels,” says Devangshu Dutta, CEO, Third Eyesight.
(Published in Financial Express)
admin
May 27, 2026
Writankar Mukherjee and Aanya Thakur, Economic Times
Kolkata/Mumbai, 27 May 2026
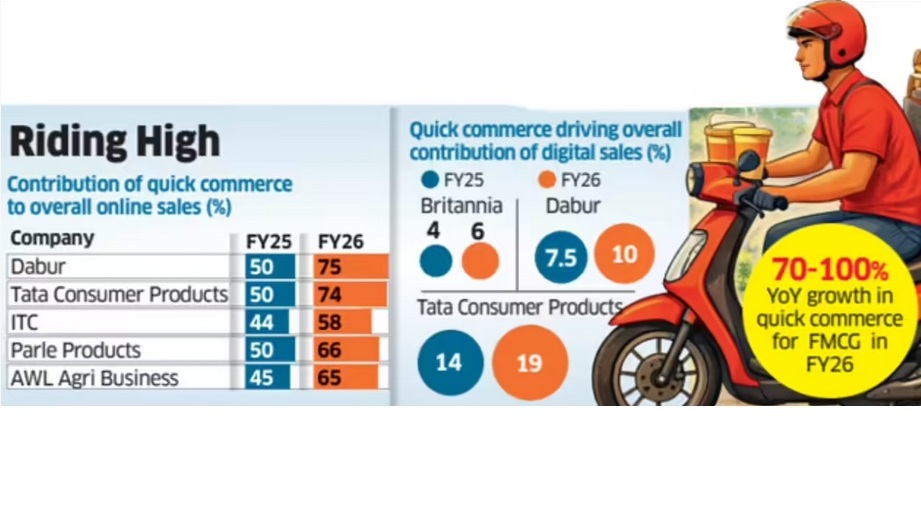
Quick commerce has become the dominant online sales channel for India’s top fast-moving consumer goods (FMCG) companies, with Dabur India and Britannia Industries among others now deriving up to 75% of their digital sales from 10-minute delivery platforms.
Industry executives said quick commerce is reshaping consumer buying habits and increasingly cannibalising sales from all other channels, including ecommerce platforms, modern trade and kirana stores, even as large online marketplaces and retailers expand into the segment.
Latest data from companies including ITC Ltd, AWL Agri Business, Tata Consumer Products and Parle Products showed quick commerce accounted for 60-75% of their total online sales in FY26, rising sharply from less than half a year earlier.
For Britannia and Tata Consumer Products, quick commerce now contributes more than 70% of online sales, while the share climbed to 75% for Dabur in the fourth quarter ended March from 50% in the December quarter.
Executives said expanding assortments and demand for instant replenishment are accelerating the shift. “Quick commerce has been gaining ground with several ecommerce companies such as BigBasket, Amazon and Flipkart, as well as retail chains like Reliance Retail, entering the space,” said Mayank Shah, vice-president at leading biscuits maker Parle Products. “Given consumers’ demand for convenience and immediate replenishment, quick commerce has emerged as a strong growth opportunity for them.”
Quick commerce accounted for 65% of online sales of Parle Products and AWL Agri Business last fiscal, compared with 50% and 45%, respectively, in FY25. ITC derived 58% of its online sales from this channel in FY26.
Frequent Purchases
Grocery-shopping are now centred around frequent top-up purchases through the week.
“Quick commerce has facilitated a grocery shopping habit which already existed – more frequent purchases. These companies are now also looking to improve profitability by expanding into higher-margin and impulse-driven categories,” said Devangshu Dutta, founder and CEO of Third Eyesight, a consultancy in consumer space.
While the channel is already significant for FMCG companies in the top 8-10 cities, it is expanding rapidly into smaller towns as operators such as Blinkit, Zepto and Swiggy Instamart widen their footprint.
Premium Push
The channel has also allowed companies to push premium products, executives said.
“While on marketplaces and traditional e-commerce platforms we were heavily skewed towards staples, the shift to q-commerce is helping us premiumise our assortment and sell far more indulgent categories,” Britannia Industries chief commercial officer Vipin Kataria told analysts earlier this month.
The transition has led to a threefold increase in sales of adjacency categories for the biscuits and dairy products maker, he said.
Kataria expects quick commerce’s contribution to the company’s total online sales to rise to 85% from 70% currently.
Most FMCG companies reported 70-100% year-on-year growth in quick commerce sales in FY26, making it the fastest-growing channel for the industry for the past two to three years. Executives expect the trend to continue.
Dabur India global chief executive officer Mohit Malhotra said beverages, foods, personal care and home care are currently the strongest-performing categories in this channel.
Saugata Gupta, managing director of Marico, said quick commerce is likely to be especially dominant in foods, while specialised ecommerce players such as Myntra and Nykaa remain strong in personal care.
The maker of Parachute, Saffola and Livon brands is strengthening its quick commerce supply chain through digitisation, automation and AI-based forecasting, Gupta said.
(Published in Economic Times)
admin
May 6, 2026
Vaeshnavi Kasthuril, MINT
Mumbai, 6 May 2026
Fashion retailers are speeding up deliveries to keep pace with instant-gratification shopping driven by quick-fashion startups, with established players and newer brands taking sharply different approaches.
For example, brands such as Biba and The House of Rare have adopted a more calibrated, infrastructure-led strategy rather than a rapid overhaul of existing store networks. “We’ve been doing this in a very soft way but not necessarily from the same stores because that affects the customer experience,” said Siddharth Bindra, managing director of Biba. Bindra said using retail stores as fulfilment hubs for rapid delivery creates operational constraints, particularly given store sizes and layouts. “We don’t have very large stores; they are anywhere between 1,000 and 2,000 square feet. So that’s not the right efficiency,” he said.
Instead, the brand is evaluating a hub-based model in cities with higher store density, enabling faster deliveries without disrupting stone operations. “If we do, it will be though proper hubs in cities where we have four to five stores, where we would start with quick commerce and accelerate it,” he said. This could enable same-day or two to three-hour deliveries.
The House of Rare, which houses Rare Rabbit (men’s urban fashion) and Rareism (women’s fashion), is adopting a similar approach, evaluating city-levee fulfilment hubs in markets with higher store concentrations to enable faster deliveries while keeping retail outlets focused on walk-in consumers.
The strategy reflects a broader attempt among legacy retallers to belance speed with experience, rather than treating stores as Interchangeable logistics nodes. “The eventual goal is the customer, but it creates a lot of difference in the customer experience” Bindra said, pointing to the trade-offs involved.
Different take
In contrast, some brands are moving more aggressively to integrate stones directly into fulfilment networks.
Libas, an initial public offering (IPO)-bound apparel company, is networking its operating model to plug its physical retail network Into a faster, hyperlocal delivery system.
Earlier, the 12-year-old company followed a more traditional structure. Online orders were largely fulfilled from central warehouses and delivered over a few days, while stores primarily served walk-in customers, with the two channels operating independently.
That is now changing. Libas is using its stores and nearby warehouses as local fulfilment points, allowing it to service orders within a much smaller delivery radius,
“At Libas, the time frame will be approximately 60-90 minutes at the max,” said Bhavay Pruthi, senior vice president, e-commerce and product management.
The rollout has been gradual, starting with select cities and limited catchments, typically within a 7-10km radius, where delivery timelines can be tightly controlled. It has also narrowed the product mix initialy to itams that are easier to move quickly.
The push comes as consumer expectations around delivery timelines extend beyond groceries into fashion, forcing brands to rethink supply-chain design,
Rise of quick fashion
The urgency to adapt is being shaped by a surge in quick fashion startups that are attracting investor attention despite heavy cash burm.
The segment has seen a flurry of funding in recent months, with Zilo raising $15.3 million in February led by Peak XV, and Knot securing $5 million in a round led by 12 Flags in December.
It has also evolved rapidly. Quick-commerce platforms such as Zepto, Instamart and Blinkit initially offered a limited range of basic fashion items for last-minute purchases. This has since expanded into a more specialized category, with vertical players offering wider assortments across party, work and occasion wear with rapid delivery timelines.
New entrants are pushing the model further. Wydo, for instance, promises deliveries within 15 to 30 minutes in Bengaluru, while Gen Z-focused offerings such as Newme’s Zip and Snitch Quick are building businesses around near-instant fashion access.
Myntra’s rapid commerce division, M-Now, accounted for about 10% of orders in the locations where it was available as of last November.
“This is the new kind of experience that customers are expecting,” Pruthi said.
Libas is working with third-party logistics providers and quick commerce platforms for the last-mile delivery, while focusing internally on faster picking, packing and order routing. Quick commerce currently accounts for about 2% of its overall sales, with scope to grow as the model scales..
Early results, however, highlight the trade-offs. “We saw very good sell-throughs for e-commerce, but it was cannibalizing existing store sales,” Pruths said.
There are also fimits to what customers are willing to buy through rapid-delivery channels. “Customers do not have the confidence to spend 15,000 for a fashion product from a quick- commerce channel,” he said.
To address this, Libas has tightened delivery radii, curated a more suitable product mix, and is testing stores with attached dark-store infrastructure to balance walk-in and online demand.
Experts say these challenges are structural.
“If you look at fashion, it’s extremely unpredictable, and if you are a brand across multiple products, it’s complicated process,” said Devangshu Dutta, founder of management consulting firm Third Eyesight.
While demand for faster deliveries is rising, it remains a small slice of the overall market, with profitability still uncertain due to limited assortments and high fulfilment costs. For traditional retailers, adopting the model requires a fundamental reworking of supply chains that were not built for near-instant delivery, Dutta added.
(Published in MINT)
