admin
November 3, 2026
Pritha Pahari, The Core
3 November 2026
India’s packaged food and soap makers are running out of easy choices. Input costs have continued to rise since late February, when the Middle East conflict began disrupting supply chains and pushing up crude-linked costs.
A visible price hike, however, risks sending shoppers to a rival. To offset this, companies have reduced package sizes. However, scope for how much these packs can be reduced is limited, especially for products already sold at low price points. Take the example of a Rs 10 pack of Parle-G biscuits.
At this price, there is little room to reduce the quantity further without risking consumer dissatisfaction. Cutting the pack size could make the product less attractive, while increasing the price may discourage price-sensitive buyers.
India’s FMCG giants have squeezed pack sizes about as far as they can go. With input costs still climbing and shoppers watching every rupee, the choice between eating the cost and raising prices is coming, likely right after Diwali.
The Hikes Are In
Britannia, Hindustan Unilever (HUL), Dabur and Godrej Consumer had already raised prices by around 2-5% in the June quarter, and were weighing more for the September quarter. FMCG companies have continued to raise prices to offset higher input costs.
FMCG companies have continued to raise prices to offset higher input costs.
Tata Consumer Products increased tea prices by 8-10% between the June and September quarters, while it raised the price of its Rs 30 salt pack to Rs 32 in May and again to Rs 34 in October.
Hindustan Unilever also took price increases of around 7.5% during the September quarter, according to media reports.
Godrej Consumer Products said it would continue calibrated price increases, particularly in soaps and liquid detergents, to manage cost pressures.
Dabur has also confirmed taking pricing actions in its October business update, while Britannia had indicated a further 1.5-2% increase, largely through smaller packs. However, the latter two companies’ September-quarter results were still awaited.
Experts said that lower-income households face greater pressure because everyday essentials take up a larger share of their budgets. Affordable products such as biscuits, noodles, soaps, detergents and cooking oils are particularly sensitive to price changes.
According to experts, some manufacturers are weighing selective price increases after Diwali, possibly from December.
Shoppers haven’t walked away yet
So far, demand is holding up. Nestlé India’s sales rose 20.5 per cent to Rs 6,782 crore in the September quarter, with double-digit volume growth.
At HUL, June-quarter underlying sales growth of 10 per cent came equally from volume and price.
The market is still nervous.
Nestlé India shares closed 7.7% lower on results day after management flagged rising input costs, especially packaging, edible oils and farm commodities.
Business Standard quoted chairman Manish Tiwary as saying, “Rising inflation, particularly food inflation, is a reality.”
India’s FMCG volume growth remains mixed, although several companies continue to report resilient demand. Tata Consumer Products’ India branded volume growth eased from 16% in Q4 FY26 to 13% in Q1 FY27 and 11% in Q2 FY27.
Marico reported that India volume growth reached near double digits in Q2 FY27, following 11% in Q1.
Dabur India recorded 5% underlying volume growth in Q1 FY27, while its October update indicated double-digit revenue growth for Q2 but did not disclose a confirmed volume figure.
Overall, demand remains resilient, but revenue growth should not be confused with volume growth, particularly as companies raise prices to offset higher input costs.
Why Smaller Packs?
Satish Meena, founder of research firm Datum Intelligence, said that companies try to absorb costs first. “They can do it for one quarter, they can do it for two quarters, but at a certain point they have to pass it on to the customer,” he said. He expects much of that to happen after the festive season.
Discounts are not an option either, since margins are thin. That leaves pack sizes. “Instead of 150 grams, we are doing 120 grams, keeping the price the same,” Meena said, describing the move.
A visible price rise carries a risk of its own.
“Your positioning in the shop will change, and customers will also perceive you as an expensive product and look for other brands,” he said. Once a rival takes the shelf space, it is hard to win it back.
Devangshu Dutta, founder of research firm Third Eyesight, says price points are hard to move. “Price points are often anchored either in the consumer’s mind or by competitive benchmark pricing, making them difficult to change,” he said.
He also said the practice now carries a reputation risk. “The shrinkflation phenomenon isn’t new, but social media has given it viral visibility, which can potentially damage brand reputation.”
Pricing Pecking Order
Meena said companies will follow a set order. First they improve buying and supply chains, then trim ad spending. Next they raise prices on premium products, where buyers are more willing to pay. Raising prices across all products comes last, so they don’t lose share.
Dutta says companies are “caught in a vice” because input costs are rising while core shoppers are cautious about spending. Companies have “no option but to cut brand-level advertising and also review overheads deeply.”
Indian FMCG companies are facing rising input costs across several product categories.
In October 2026, plastic packaging costs were reported to have increased by 30–40%, putting pressure on snack makers and household-product manufacturers.
Palm oil prices rose 21% year-on-year in September, while sunflower oil increased 14%, soybean oil 9% and mustard oil 8%.
Sugar prices climbed 18% year-on-year, adding pressure on confectionery and packaged-food producers.
Tea prices rose 10% over the same period. Coffee and cocoa also recorded increases, with Arabica coffee up 19% quarter-on-quarter and cocoa rising 48%. These increases affect biscuits, noodles, chocolates, soaps, shampoos and detergents differently.
Now What?
The next test is HUL’s September-quarter results, due after its board meets on 28 October. Meena does not expect much to change in the next one to two quarters.
He says the pressure is not seasonal. “It’s because of the war happening in the Middle East… it’s a much longer issue for them,” and he points to RBI data showing some impact on demand.
Input-cost pressures could persist into early 2027.
S&P Global’s September outlook projected elevated manufacturing costs through 2027, while October data showed plastic packaging costs 30–40% higher and key polymer prices more than 50% above pre-conflict levels.
Although prices may ease if supply routes improve, these figures suggest FMCG companies could face continued cost pressure over the next two quarters.
Dutta said only a few brands will come through easily. “Few brands or products are able to build longer-term loyalty consistently and whose value to the consumer is stickier than the resistance to price movement.”
For everyone else, the room to raise prices or shrink packs is running out.
(Published in The Core)
admin
October 30, 2026
Kartikay Kashyap, Financial Express
30 October 2026
Brands are ready to roll the red carpet for consumers this festive season. But for jewellery brands this Diwali will likely be a tad different from previous ones.
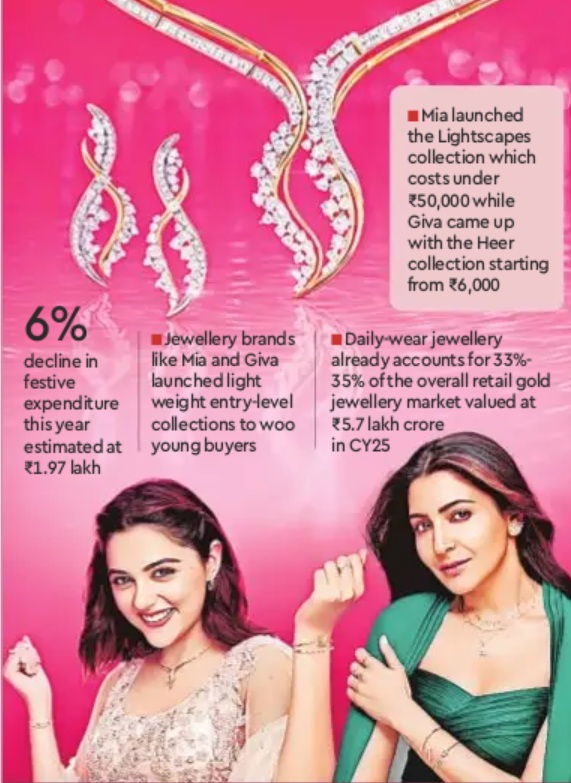
For context, consumer spending during Diwali is expected to see a decline according to Mood Of The Consumer, a survey released earlier this week by LocalCircles. On an average, urban households are looking to spend ₹20,000 in discretionary purchases this festive season, with the total spending to decline 6% from last year. The estimate puts festive expenditure at ₹1.97 lakh crores in 2026 compared with ₹2.1 lakh crores in 2025.
For jewellery brand Mia, which retails lightweight everyday jewellery, this is yet another opportunity to cast its net wider. The Titan Company-owned brand has launched Lightscapes, a new collection featuring more than 230 designs across plain gold, natural diamonds and coloured stones. The collection features a range of jhumkis, sculptural danglers, necklaces, pendants, rings and bracelets in 9KT and 14KT gold and is priced under ₹50,000 to woo first-time jewellery buyers. The supporting campaign takes forward Mia’s promise to offer women a conduit for self-expression. At the same time, the new campaign aims to push the idea of buying jewellery for festive gifting.
Mia is not the only one. Giva, which entered the gold jewellery segment during 2023 Akshay Tritiya, has introduced the Heer by Giva collection featuring polki jewellery crafted in 14 KT gold, while its Vivid Gemstone collection offers gemstone designs in 9KT and 14 КТ gold, besides a range of lab-grown diamonds. The range starts from 6,000 and goes up to ₹90,000.
The advertising pitch for jewellery brands is changing in tan-dem. If earlier they used emotion and heritage as triggers, recent advertising highlights self-expression, self-gifting and gender-neutral collections.
“The strategy to bet on affordable jewellery seems to be prompted by the surging price of gold and the hope that consumers would be keen on buying lightweight affordable jewellery this festive season,” says Devangshu Dutta, founder, Third Eyesight.
To be sure, gold prices have been volatile all of 2026. Though it has fallen more than 26% from its January record high, it is still 11.6% higher than last Diwali. For jewellery brands lightweight pieces have become the primary solution to maintaining retail volume, says Sanjeev Shukla, business advisor to fashion retailer Vinusto.in.
Lightweight jewellery has also gained traction among younger consumers in recent years. “Today’s consumers, particularly younger women, are increasingly seeking jewellery that reflects their personal style, offers versatility and fits within their budgets,” says Ajay Maurya, head of marketing & category, Mia by Tanishq. “Our focus is on making contemporary fine jewellery more accessible without compromising on design, quality or craftsmanship.”
Naresh Gupta, managing partner & chief strategy officer, Bang In The Middle, believes that younger generations especially Gen 2 buyers are drastically changing what and how they buy. Instead of heavy, occasion-led, or locker-stashed gold pieces meant strictly for weddings and festivals, they are pivoting toward lightweight, design-forward, and everyday wear. They want Indo-Western pieces that pair as well with a Diwali lehenga as they do with an office-event blazer. “The Diwali campaign strategy aligns with the jewellery retailers’ strategy to catch on the younger lot and recruit them into the ecosystem early in their stage,” says Gupta.
Daily-wear jewellery already accounts for 33%-35% of the overall retail gold jewellery market valued at 15.7 lakh crore in CY25. Organised retailers held about 37% of this market in CY25.
Apart from self-expression, light-weight jewellery also makes a good case for gifting. “Entry-level fine jewellery and budget-friendly pieces work particularly well for gifting, which makes them relevant during the festive season,” tells Disha Shah, founder, DiAi Designs.
A golden opportunity
Will Mia’s decision to take the affordability route cannibalise stable brands like Zoya and Carat Lane? If young buyers form the habit of wearing lightweight jewellery, they might do that during wedding as well, says Gupta.
One might argue that brands like Mia enable new buyers enter the fine jewellery ecosystem and move up the ladder to become the customers of brands like Tanishq and Zoya. But Vinusto’s Shukla argues repeat buying might still be a challenge for the affordable jewellery players.
For Mia, which crossed the ₹2,000-сrоге revenue milestone in the financial year 2025-26, the festive season represents a crucial window to turn up the volume. Experts say the season makes up 15-20% of the annual jewellery sales and some brands have gone on record to say they have already seen a 50% surge over pre-Diwali sales.
DiAi’s Shah remains optimistic. “We are seeing new customers explore jewellery, alongside existing customers who are looking to redesign or upgrade pieces they already own. Festive occasions provide a natural reason to enter the category, while contemporary, everyday fine jewellery can help build that relationship beyond the festive period,” she says.
(Published in Financial Express)
admin
October 29, 2026
Pritha Pahari, The Core
29 Oct 2026
When ITC Ltd. launched Aashirvaad in May 2002, it sold one thing — whole wheat flour. The brand now has more than 200 SKUs across staples, spices, fresh foods and frozen foods.
ITC wants to double what Indians spend on Aashirvaad to Rs 20,000 crore in five years. It said growth will come from two places: more premium atta, and new categories around the Indian kitchen. That makes the brand a test of a hard question in packaged food. Can a name built on the purity of an ingredient win in the other segments and break out from its identity built around atta?
Trust in the purity of flour may not translate into trust in ready-to-eat meals, where taste, consistency and repeat purchases matter more. ITC itself has bought brands and built separate ones for some of these jobs.
A Big Target, A Soft Core
Hemant Malik, who runs ITC’s foods division, told PTI the company expects spending on Aashirvaad to double from above Rs 10,000 crore. That figure is what shoppers pay, including taxes and trade margins. It is not ITC’s revenue. The push comes as the core product slows. In the quarter ended June 30, ITC said atta was held back by heat waves, an LPG shortage and low wheat prices.
FMCG-Others revenue rose 12%, or 16% without staples, and dairy, snacks, noodles and frozen snacks each grew more than 20%. Not all of that belongs to Aashirvaad. Snacks, noodles and frozen foods sell under Bingo!, YiPPee! and ITC Master Chef.
The wider backdrop matters too. ITC is trying to rely less on cigarettes, which now face a sharp rise in tax.
Devangshu Dutta, founder of consultancy Third Eyesight, said value-added ready-to-cook and ready-to-eat products earn better gross margins than staples. Selling more of them would also help ITC use its factories more fully, he said.
ITC’s recent annual report shows multigrain atta, vermicelli and besan have grown threefold over five years, and now make up about 16% of the staples portfolio. ITC does not give a brand-level split between premium atta and new categories, or Aashirvaad’s profit.
ITC’s own Q1 FY27 release said atta performance was tempered by transient factors including heat waves, an LPG shortage and benign wheat prices. The FMCG-Others business grew 12% in the quarter.
The Easy Stretch
ITC said its value-added atta variants and staples-related products have grown three-fold in five years, and their share of the portfolio has doubled. They include besan, rava, vermicelli and soya chunks. The newest addition is chana sattu, first sold in Bihar, Jharkhand and West Bengal, with a Rs 10 pack that carries 10 grams of protein.
Suumit Kapoor, a brand growth consultant, calls these safe stretches. Besan and rava barely change what a shopper expects, he said. They are “still about what’s in the bag,” so purity still answers the question.
The Harder Jump
Ready-to-cook and ready-to-eat food asks something different. “Purity is a raw material promise. Ready to eat is a finished experience,” Kapoor said. Nobody buys a packaged curry because the dal was well sourced, he said. They buy it because they are hungry, short of time and hoping it tastes home-cooked.
ITC’s recent launches show it knows this. Its ready-to-cook chapati comes in packs of 10, with no preservatives and a shelf life of five to six days. The chutney and sambar range, launched in June, is made in small batches without preservatives and depends on a cold supply chain.
At launch it was sold only in Bengaluru through quick-commerce apps. The short shelf life answers a real problem.
Dutta said many shoppers prefer freshly cooked, hot meals and are wary of additives that extend shelf life. Cold chains remain patchy even in big cities, he said. A time-pressed household can also cook, order in, eat out or buy a packaged meal, and each choice is judged on price, convenience and taste.
Kapoor added a caution about ITC’s own numbers. They do not show whether shoppers buy the new products because of the Aashirvaad name, or simply because those categories are growing.
ITC’s latest results release names ready-to-cook chapati in a list of products but gives no sales figure for it, or for ready-to-eat meals. That may reflect how ITC groups its figures, not a change in plans.
Why One Name Still Makes Sense
Dutta sees a strong business case for using one name. A familiar brand cuts the cost of getting shoppers to try something new, he said, because Aashirvaad is already in millions of homes. New items can also move through ITC’s existing distribution, including modern trade and quick commerce, and retailers accept extensions from a leading brand more readily than unknown labels.
He also sees a defensive motive. Aashirvaad sits in everyday kitchen use, between ITC’s older gourmet line, Kitchens of India, and its snack-led Sunfeast. A bigger range puts it up against MTR, Haldiram’s and iD Fresh.
Tata Consumer said Tata Sampann grew 69% in Q4 FY26 with strong performance across categories. On the Q1 FY27 earnings call, CEO Sunil D’Souza said the core portfolio of pulses, spices, poha and vermicelli was growing at about 30%, with cold-pressed oils and dry fruits adding to that growth.
Poha and vermicelli are the closest items to convenience foods, but Tata doesn’t separate them out.
AWL Agri Business, which owns Fortune and Kohinoor, reported Q1 FY27 Food & FMCG revenue of Rs 1,726 crore, up 22%, with a segment EBITDA margin of 6%, and management said the Fortune and Kohinoor brands both grew at double-digit rates. AWL’s investor day deck also shows Kohinoor rising from Rs 150 crore in FY23 to over Rs 400 crore in FY26.
Not Betting Only On The Name
ITC’s record suggests it does not rely on one brand for everything.
It launched Kitchens of India in 2001 as a separate premium name, using the dishes of its hotel restaurants. It bought the spices brand Sunrise in 2020. In February 2025, it agreed to buy Prasuma, a frozen and ready-to-cook company, starting with a 43.8% stake. Sproutlife Foods, the Yogabar business, became a subsidiary on April 1.
Mint reported in February 2025, citing two unnamed people, that ITC was in early talks to buy MTR Foods and Eastern Condiments from Norway’s Orkla for about $1.4 billion. Orkla said it does not comment on rumours. ITC did not reply to Mint. No deal followed.
Kapoor reads such moves as ITC buying skills it lacks, not as proof that Aashirvaad cannot stretch.
ITC is also putting weight behind fresh food. Its fresh food business, which includes a brand called ITC Aashirvaad Soul Creations, grew gross order value 90% in the quarter, passed an annual revenue run rate of Rs 300 crore and now runs 75 cloud kitchens in five cities.
What Comes Next
The company’s position is strongest where the brand started. In July, ITC said it had already secured 95% of the wheat of the quality needed for Aashirvaad atta, but it also warned that monsoon rains were short and El Niño could hurt growth.
Value-added atta variants and staples adjacencies have grown three-fold over five years, and Aashirvaad Svasti dairy is among its fastest-growing categories, but neither is a meal category.
The newest meal-type launches, such as ready-to-cook chapatis, frozen naans and parathas, and fresh chutneys and sambar, have no disclosed sales or repeat-purchase data.
ITC launched Aashirvaad ReadyMeals back in 2003 and still describes ready-to-cook as a new bet, and it markets other finished-food lines under separate brands (Kitchens of India, ITC Master Chef, Prasuma), which suggests it doesn’t simply assume the Aashirvaad name carries into every meal category.
Management frames success around product innovation and differentiation, not brand trust alone. The larger test is on the shelf.
Kapoor said staples-linked products can keep drawing on Aashirvaad’s purity, but anything close to a finished meal has to earn a name for taste and consistency. Whether shoppers will pay for that under the Aashirvaad label is what ITC’s Rs 20,000 crore target depends on.
(Published in The Core)
admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
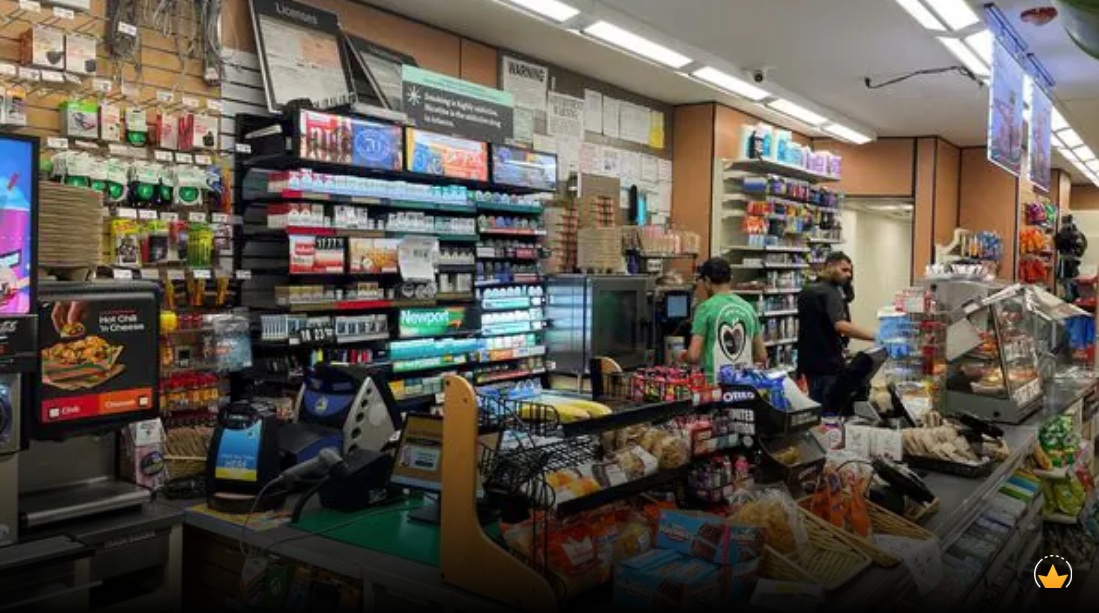
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
October 5, 2026
Sagar Malviya, Economic Times
5 October 2026
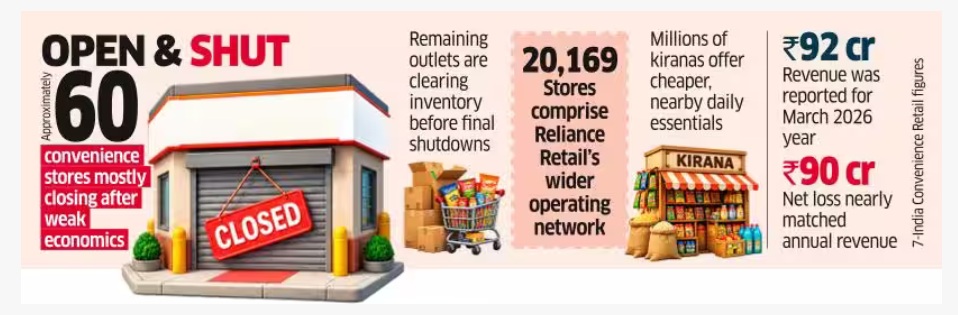
Reliance Retail and 7-Eleven are ending their five-year franchisee deal in India, closing most of the nearly 60 convenience stores they operated under the partnership, after struggling to make the format profitable, people familiar with the matter said.
A handful of outlets are clearing the inventory before shutting, they said. 7-Eleven may look for another Indian partner to keep a foothold in the market, although no decision has been made, the people said.
The exit highlights an unusual squeeze that convenience stores are facing in India, with millions of small kirana stores that have long served consumers’ immediate needs on one side and quick-commerce companies that are bringing the same snacks, groceries and daily essentials to doorsteps within minutes on the other.
Reliance and 7-Eleven did not respond to ET’s queries.
The partnership, struck in 2021, was intended to bring the world’s largest convenience-store chain to India through Reliance’s retail network. But the business struggled to achieve the scale needed to offset the relatively high costs of running branded stores.
The 7-India Convenience Retail venture reported revenue of about ₹92 crore ($10.6 million) and a net loss of nearly ₹90 crore in the year ended March 2026, according to its financial statements.
“Reliance wants to reach consumers across every channel, but sustainability ultimately matters. Convenience stores have faced increasing pressure from quick commerce since the pandemic, with both formats offering similar assortments and serving the same immediate-needs occasions,” said Devangshu Dutta, founder and CEO of Third Eyesight, a consumer-sector consultancy.
“Kiranas operate with far lower overheads and different margin expectations than corporate-run convenience stores. Reliance’s exit could therefore signal a broader rethink of the format, particularly in markets where quick commerce has become a strong alternative.”
Globally convenience stores have become powerful retail businesses in several markets despite the expansion of supermarkets and hypermarkets. 7-Eleven in Japan, Taiwan, Thailand and Singapore; Lawson in Japan and Oxxo in Mexico are among the largest retailers in their respective markets.
7-Eleven’s Japanese parent, Seven & i Holdings, operates more than 85,000 stores globally, making it one of the world’s largest retail networks. Yet the company has been restructuring its overseas operations and closing stores in North America as consumer behaviour and store economics change.
In India, however, organised convenience retail has struggled to replicate the success seen in other Asian and emerging markets. EasyDay, More and Spencer’s have either shut stores or shrank their smaller-format networks over the years, underscoring the difficulty of building profitable neighbourhood stores at scale.
Packaged consumer goods companies continue to derive roughly three-fourths of their sales from small neighbourhood stores, underlining the strength of the traditional distribution network. Quick commerce platforms are, meanwhile, expanding rapidly.
That makes it difficult for organised convenience stores to charge a premium or generate sufficient sales density to cover higher rents, staffing, inventory and logistics costs.
Convenience retail works best when operators achieve high store density and productivity, supported by strong supply chains and differentiated offerings such as fresh food and private labels.
Reliance initially expanded the 7-Eleven network in Mumbai and other markets, but the footprint remained small compared with the company’s wider retail operations.
(Published in Economic Times)
