admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
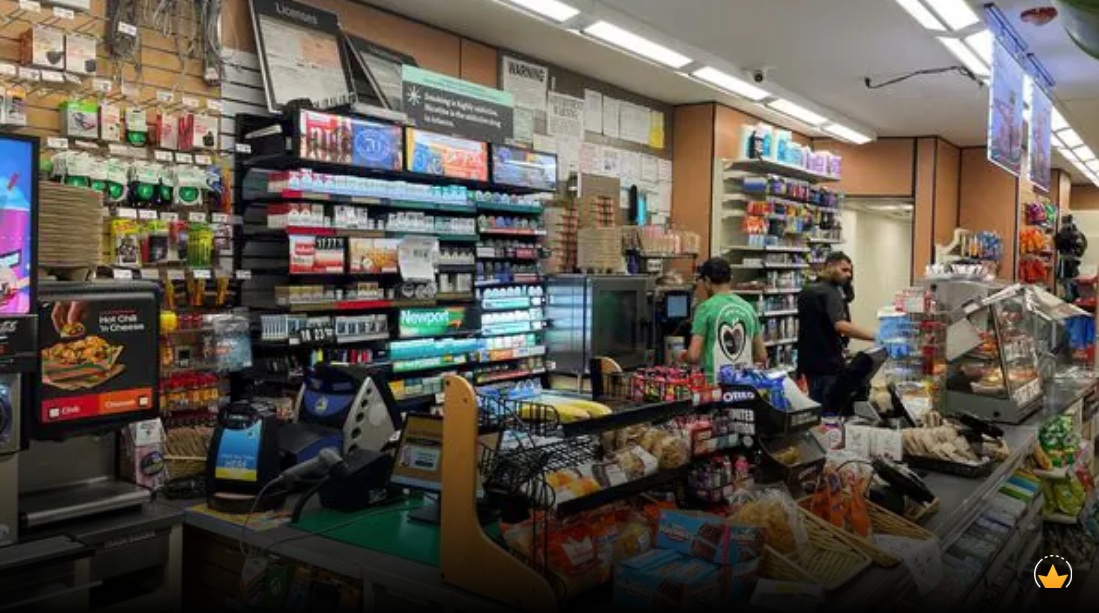
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
May 9, 2026
Writankar Mukherjee, Economic Times
Kolkata, 9 May 2026
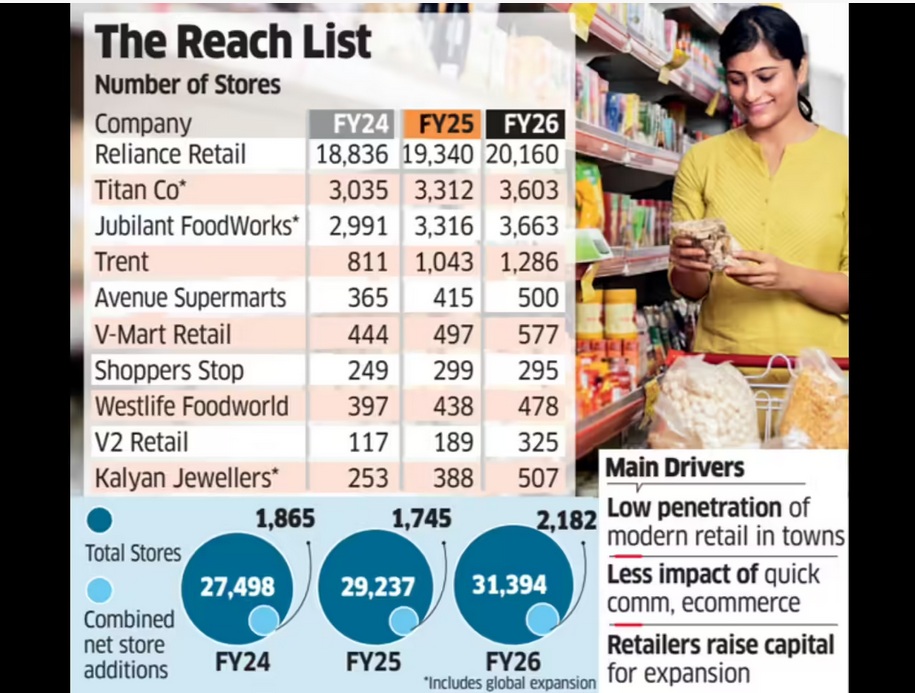
India’s top retail chains including Reliance Retail, DMart, Trent, Titan Company, Jubilant FoodWorks, and V-Mart Retail opened the highest number of stores in three years in FY26, seeking to capitalise on a demand recovery and a clean-up of unviable outlets added during the post-Covid revenge-spending period.
Entry into smaller towns and cities where many consumers continue to prefer shopping at physical stores over online is also influencing the expansion plans.
An ET study of the 10 largest listed retailers showed they added 25% more stores in the last fiscal year compared to FY25. Additions are on a net basis after accounting for loss-making outlet closures.
Collectively, the retailers added 2,182 stores in FY26, equivalent to six new stores a day on a net basis. In comparison, they added 1,745 stores in FY25 and 1,865 in FY24.
Retailers attributed the store expansion spree to improving consumer sentiment, helped further by cuts in income tax and goods and services tax (GST) rates last fiscal, along with low penetration of organised retail in smaller towns and cities. Together, the ten retailers had 31,394 stores operational as of March 2026.
Expansion Set to Continue
V-Mart Retail chief executive officer Lalit Agarwal said the ongoing shift from unorganised to organised retail is fuelling this expansion as several companies are meeting their sales growth expectations. “Many retailers have also raised capital, which they are deploying to grow topline,” he said, adding that the “growth phase will continue in the current fiscal as well.”
Companies surveyed by ET also include Shoppers Stop, Westlife Foodworld, V2 Retail and Kalyan Jewellers. Together, the ten retailers had 31,394 stores operational as of March 2026. Their combined store count grew 7% in FY26, ahead of a 6% expansion in the year before.
Reliance Retail alone added 820 net stores last fiscal, rebounding from a slowdown in FY25 when it shut several unviable outlets that were opened immediately post Covid, impacting overall industry growth rates. The country’s largest retailer had added 504 net stores in FY25, 796 in FY24, and 2,844 in FY23.
Similarly, Tata-owned Titan added 532 stores in FY23, but expansion moderated to 280-290 stores annually in FY25 and FY26.
India’s retail industry saw hyper expansion in late FY22 and FY23 as retailers sought to tap a boom in post-pandemic revenge shopping.
“Retail expansion now is more organic and measured as compared to the post Covid phase when there was a huge backlog of demand and over expansion,” said Devangshu Dutta, founder and CEO at Third Eyesight, a consultancy in consumer space.
(Published in Economic Times)
admin
February 18, 2026
Kartikay Kashyap, BrandWagon, Financial Express
18 February 2026
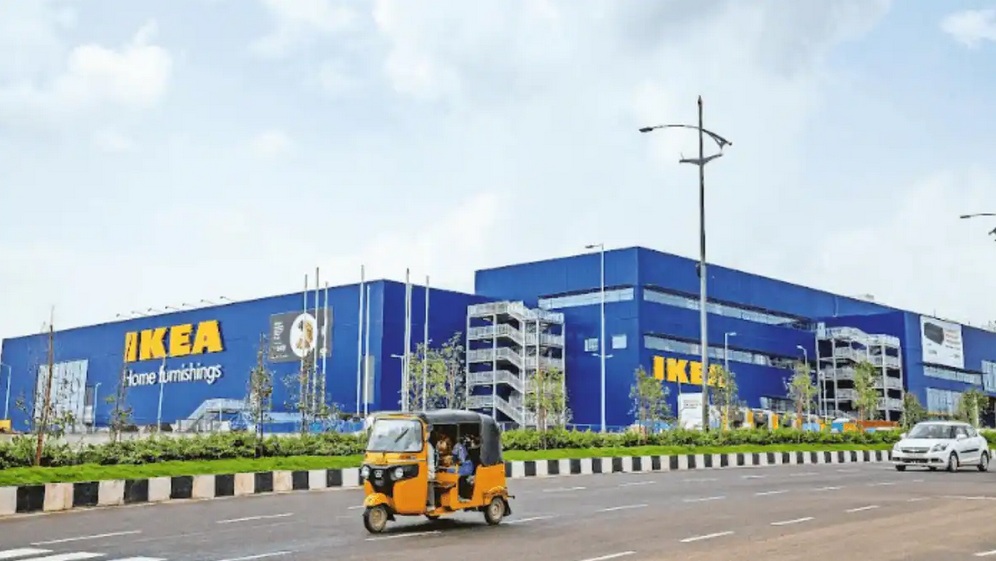
IKEA HAS BEEN around in India for about eight years, with another three years before that spent studying the market. It has developed a range that it deems “locally relevant-like the roti maker, the tava (pan), the belan (rolling pin), and the pressure cooker -which now constitute about 50% of the products it offers in the country. It has shifted its communication strategy to sync with local culture and fit into local spaces and has worked hard to beef up its omnichannel sales model with about 30% of its sales originating online. But profitability has remained elusive for the retailer whose global sales reached approximately €45billion in the 2015 financial year (FY25).
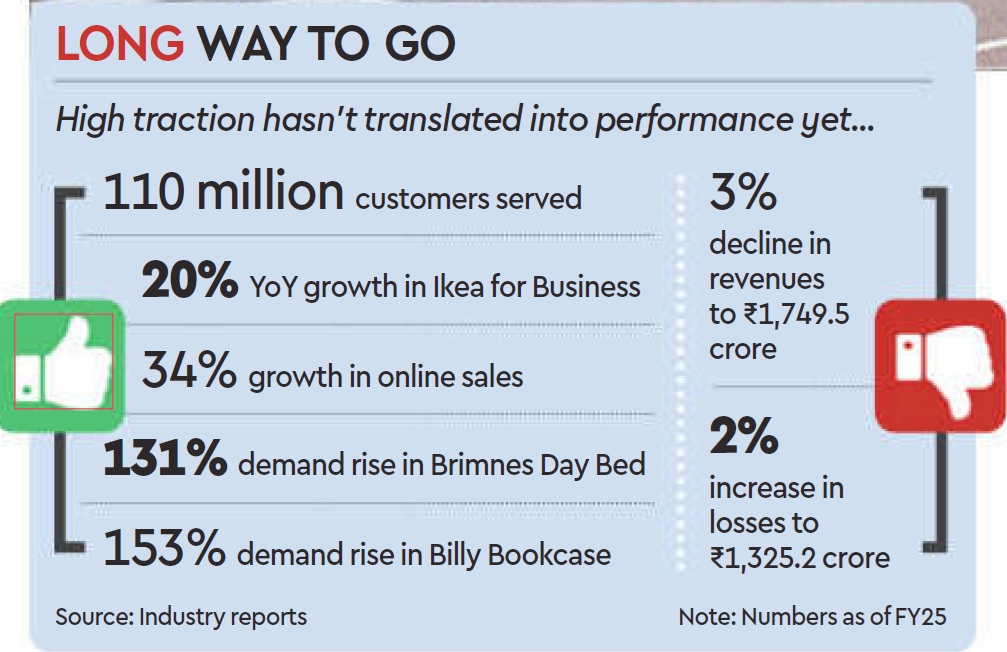
Just for context, the company’s India entity widened its losses by about 29 to 1,325.2 crore in the financial year ending March 31, 2025 (FY25). The revenue also dipped 3 to 1,749.5 crore from 1,809.8 crore in FY25.
So now the brand is taking a leaf out of its China playbook and tweaking its retail formats. Starting last year, it started piloting smaller store sizes ranging from 15,000-20,000 sq ft that are more cost-effective to set up and faster to integrate with its omnichannel model. “The goal is to create a simpler and more efficient shopping experience,” Ingka Group Retail Manager Tolga Oncu had said when the concept was unveiled last August.
Five months on, the furniture retailer is looking to take a step up the ladder – setting up new stores in the 50,000-70,000 sq ft range in the country, which will sit comfortably between its smaller stones (15,000-20,000 sq ft) and big box retail outlets (4 lakh sq ft), Adosh Sharma, country commercial manager at Ikea India told FE recently. Ikea’s broader plan also includes doubling its investments in the country to over 20,000 crore ($2.2 billion) over the next five years and improving local sourcing.
Will all this help the retailer grab a larger share of the highly fragmented furniture and furnishing market in the country? Will the brand achieve profitability in the next two years in keeping with its plans?
Ikea realises copy-pasting its global retail strategy in India is not going to work. That explains its recent moves to tweak store sizes and product design. Over and above the regular 5-M-L strategy, the fourth format the brand is developing comprises no-frills planning and order points, focused on customers who want to design homes or seek complex solutions without distraction.
“Smaller stores, which fulfill purpose-led needs will help them to get closer to their customers,” says Devangshu Dutta, founder & CEO, Third Eyesight.
The furniture and home decor segment has been up against slow purchase cycles in India. Smaller sized stores that are closer to residential arras might help step up the frequency of purchases. “Players are moving towards a higher purchase frequency strategy and smaller stores will help lkea cash in on this opportunity,” says Kushal Bhatnagar, associate partner, Redseer Consultant Strategy. He says quick commerce has helped improve the purchase cycle in the home decor space, and that is something Ikea will likely tap going forwand.
Dutta says Ikea has taken a long-term view on India and the investments in the pipeline is an indication of the opportunity that awaits players.
The brand claims it has served close to 110 million customers in FY25 across channels, and online sales are growing 34% compared to the previous fiscal. While furniture contributed the lion’s share of its revenue, the food business contributed 100% and Ikea for Business (tailored solutions for businesses) another 19% to its topline.
(Published in Financial Express)
admin
January 28, 2026

What does it actually take to build a fashion brand in India?
This panel (“Beyond the Noise- How D2c Fashion Brands Are Reinventing Retail”) at the 25th Edition of India Fashion Forum focussed on some real answers, in a refreshing, down-to-earth conversation moderated by Devangshu Dutta (Founder, Third Eyesight), with the founders of DeMoza (Agnes Raja George), The Mom Store (Surbhi Bhatia), Miraggio (Mohit Jain), BeyondBound (Tejasvi Madan), and Bari (Sameer Khan Lodhi).
No fluff, no “disrupting the industry” talk. Just founders being honest about what’s worked, what hasn’t, and what they’d do differently. A few things that struck a chord:
• Every single brand started because the founder couldn’t find something they personally wanted: inclusive activewear, affordable handbags that didn’t look cheap, good maternity wear. Sometimes the simplest observation is the best business idea.
• Inventory management came up often. One founder took their inventory cycle from 6 months down to 4. Another re-shuffles stock every 15 days based on what’s selling where. Unglamorous? Yes, but this is what actually keeps a business alive.
• The marketing conversation highlighted a move away from traditional advertising toward things that actually make people feel something. One founder talked about turning a farmhouse into a full “apricot colour” experience for customers. Another shoots content with real customers, not influencers.
• And the most memorable line of the whole discussion came from the most experienced founder in the room sharing a learning: “I won’t open stores fast.” No explanation needed, really.
Building a brand is exciting. Keeping it alive is the harder, quieter work. This panel was a good reminder of that. Worth a watch if you’re building something in this space.
admin
January 6, 2026
Saumyangi Yadav, Entrepreneur India
Jan 6, 2026
After years of rapid growth and a sharp reset, India’s direct-to-consumer (D2C) sector is expected to settle into a more balanced phase. The period of easy funding, aggressive customer acquisition and scale-at-all-costs expansion is clearly over, experts suggest. Now, what lies ahead in 2026 is a shift towards steadier growth driven by better execution, stronger retention and clearer brand positioning.
According to Bain and Flipkart, India’s e-retail market is projected to reach $170–190 billion in GMV by 2030, driven by a growing online shopper base and evolving commerce models. As adoption deepens across Tier-2 and Tier-3 cities, high-frequency categories such as grocery and lifestyle are expected to drive a larger share of growth, making repeat purchase and habit formation critical for D2C brands.
Against this backdrop, 2026 is shaping up as the year when D2C brands are judged less on ambition and more on outcomes.
A Post-Hype Phase of D2C
Industry observers say the D2C ecosystem has clearly moved beyond its hype-driven phase. Devangshu Dutta, Founder and Chief Executive of retail consultancy Third Eyesight, describes the current moment as one of structural correction rather than contraction.
“India’s D2C ecosystem is in a post-hype phase where growth may be slower but structurally healthier,” Dutta says, adding, “Earlier growth cycles prioritised visibility and sales at the expense of profitability and consistency. Now, success is being measured by repeat rates, contribution margins and the ability to fund growth internally.”
Tighter funding is also driving this shift. With D2C investments slowing and overall capital remaining cautious, brands are now being pushed to show predictability rather than promise. Tracxn data shows Indian D2C startups raised USD 757 million in 2024, significantly lower than previous years, while overall PE-VC investments in India remained flat at USD 33 billion in 2025, according to Venture Intelligence.
As a result, Dutta notes that many D2C companies are rationalising portfolios, tightening inventory cycles and optimising supply chains. Marketing strategies, too, are evolving, with greater emphasis on retention, community-building and owned channels instead of discount-led growth.
Uniqueness Will Define Winners
If capital discipline is one defining force, speed is another. Harish Bijoor, business and brand strategy expert, argues that D2C’s next phase will be shaped by how brands respond to a faster, more fragmented commerce environment.
“The e-commerce revolution led to a more refined orientation of D2C, and that has now given way to a q-commerce revolution that is even faster,” Bijoor says, adding, “The D2C revolution is going to be leveraged by speed. A whole host of players will invest time, energy and innovation into this.”
In Bijoor’s view, traditional e-commerce is now the slowest layer in a spectrum where quick commerce is the fastest, and D2C sits in between. In such a landscape, competing purely on price is no longer sustainable. He believes differentiation will increasingly come from uniqueness and premium positioning rather than ubiquity.
“When you know that you get a particular great-tasting biryani at just one place with no branches, you will go to that place. That uniqueness is what will distinguish D2C commerce in the future,” he says.
Bijoor adds that many D2C brands have been trapped in price wars under the guise of differentiation. He also argued that brands that premiumise and resist excessive omnichannel dilution are more likely to build desirability and long-term value.
Consumers Move Beyond Metros
Structural shifts in demand are reshaping how and where D2C brands grow. India now has one of the world’s largest and most diverse online consumer bases, with growth increasingly driven by Tier-2, Tier-3 and smaller towns rather than metros alone. Internet adoption continues to deepen across rural and semi-urban India, expanding the addressable market well beyond early digital buyers.
This widening base is changing the nature of growth. Consumers are becoming more deliberate in how they spend, weighing value, quality and trust more carefully than before.
As Devangshu Dutta notes, Indian consumers have always been discerning, but rising living costs and economic uncertainty have made them even more thoughtful, pushing brands to earn repeat demand rather than rely on impulse or discount-led purchases.
“Value is not just about discounts,” he says. “It’s a balance of price, performance and trust. For D2C brands, repeat consumption has to be earned through consistent quality, transparent pricing and dependable service.”
High-frequency categories such as grocery, lifestyle and general merchandise are expected to drive much of this expansion. Bain estimates these segments will account for two out of every three e-retail dollars by 2030, reinforcing the importance of habit formation and retention-led models.
Quick Commerce Expands Discovery, Not Profitability
Quick commerce has emerged as a powerful but complex growth lever for D2C brands. The format now accounts for a significant share of India’s e-grocery demand and has scaled into a multi-billion-dollar market, becoming a key discovery channel for food and everyday consumption brands.
However, expansion beyond metros remains challenging. RedSeer data shows non-metro markets contribute just over 20 per cent of quick commerce GMV, even as platforms scale to over 150 cities, with breakeven economics in smaller towns requiring significantly higher throughput.
Praveen Govindu, partner at Deloitte India, cautions that while quick commerce has helped many D2C brands gain discovery, particularly in food and beverage, it is not a sustainable growth engine on its own.
“From a customer acquisition standpoint, quick commerce is not fundamentally different from traditional e-commerce,” Govindu says, adding, “It is an expensive channel, and competition will only intensify. Over the long term, brands cannot rely on burning capital there.”
Omnichannel Enters Its Toughest Phase Yet
As digital acquisition costs rise, India’s ad market is projected to grow nearly 8 per cent in 2025 to Rs 1.37 lakh crore, with digital accounting for almost half of the spends, brands are being pushed to diversify distribution. Yet omnichannel presence alone is no longer enough.
“Many brands talk about omnichannel, personalisation and seamless journeys, but in practice these efforts are still disjointed. In 2026, the focus will shift from intent to execution,” Govindu says.
RedSeer projects India’s retail market to cross USD 2 trillion by 2030, with nearly 90 per cent of consumption still happening offline. For D2C brands, this makes offline expansion unavoidable, but success will depend on consistent execution across pricing, inventory, service and communication.
Consumers, Govindu notes, do not consciously differentiate between online, offline or social platforms. “They simply want a consistent experience,” he says. “Even small inconsistencies can erode trust.”
AI-Led Discovery and Experience
Perhaps the most transformative force shaping 2026 will be the evolution of buying journeys themselves. Govindu sees the rise of AI-led and agentic commerce as a major inflection point.
“Conversational platforms and AI-driven assistants will increasingly influence discovery, purchase, fulfilment and post-sales experiences. What earlier happened across multiple touchpoints is now beginning to happen in one place,” he says.
This convergence amplifies the importance of content-led discovery, owned data and deep consumer understanding. Brands that can unify storytelling, commerce and service into a coherent narrative are more likely to build loyalty in an environment where switching costs are low and alternatives are abundant.
Whether growth comes through D2C websites, marketplaces, quick commerce or offline stores, experts agree that the real differentiator will be a brand’s ability to build durable consumer relationships. As investors shift focus from short-term metrics to long-term value creation like retention, margins and brand strength, the next phase of India’s D2C story is less about rapid expansion and more about refinement.
(Published in Entrepreneur India)
Saumyangi is a Senior Correspondent at Entrepreneur India with over three years of experience in journalism. She has reported on education, social, and civic issues, and currently covers the D2C and consumer brand space.
