admin
September 1, 2026
Vikash Tripathi, Outlook Business
1 September 2026
Eight decades ago, the ‘nationalist businessman’ GD Birla helped prepare the ‘Bombay Plan’, which asked the state to pro-vide for the bare minimum needs of its people. His plan asked for 2,800 calories of well-balanced food per day, 30 yards of clothing per year and 100sq ft of housing per person.
Today, seventh-generation Aryaman Vikram Birla is betting on an entirely different opportunity: premium dining. “We continue to believe in the remarkable potential of the premium casual dining space, spurred by rising disposable income and evolving lifestyles,” the 29-year-old said after Aditya Birla New Age Hospitality acquired KA Hospitality in 2023.
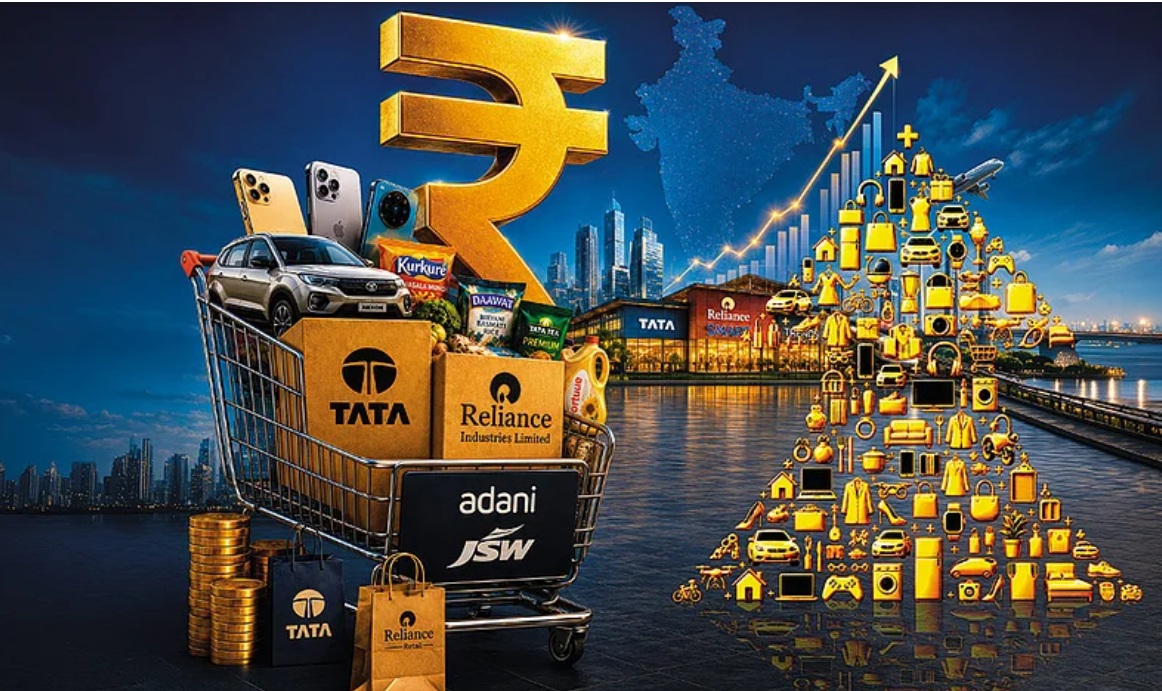
The Birlas are not alone in trying to cash-in on rising prosperity in India. In the past five years alone, India’s top 10 industrial groups have announced new ventures in consumer-facing sectors or doubled down on existing ones. A rough tally of these investments crosses ₹4.8 lakh crore.
For decades, these same business houses built their dominance in core sectors like steel, power, aluminium, cement and chemicals, laying the industrial backbone of the economy. This helped the nation become a large producer of such goods and, in some cases, an exporter as well.
But as India’s economic conditions changed, so has the focus of its largest conglomerates.
For the likes of Tata, Aditya Birla, Bajaj and Bharti, that journey started way back. “What has changed in recent years is the speed and openness of the amount of capital being invested,” says Jitender Kumar, associate professor and programme chairperson, retail management programme at Birla Institute of Management Technology.
“It is not ‘opportunistic’ reasons, it’s structural reasons.”
Two factors seem to be driving the shift: the first is the arrival of an affluent consuming class that can buy branded and premium goods, and the second is the attraction of consumer businesses as a way to diversify revenue and, in some cases, improve the quality of earnings.
The Rise of Affluence
A couple of decades ago, if an Indian household had some extra cash, it often meant buying more of the same. Today, it increasingly means buying better. Even salt is being upgraded, from iodised to Himalayan pink or rock salt. The same shift is visible in bigger purchases: sports utility vehicles (SUVs) over hatchbacks, and ₹1cr-plus homes over budget flats.
But India isn’t simply consuming more. It is moving from basic consumption towards discretionary, branded and premium consumption. This boom is most clearly seen in the rapid expansion of the financial infrastructure that enables consumption. Formal retail credit penetration has more than doubled over the past decade, according to a TransUnion Cibil report, driven largely by personal loans, credit cards and consumer durable loans. Meanwhile, the government-backed Unified Payments Interface has untethered spending from the cash in a buyer’s wallet.
The signs show up across the broader consumption economy. Homes priced above ₹1cr accounted for 54% of total sales in 2025, up from just 30% in 2023—the market that decorative paints and home solutions are chasing.
Out of 4.7mn cars sold in the financial year 2025–26, SUVs accounted for more than half.
“The consumer market has grown substantially—not only through rising incomes but also the dramatic expansion of branded consumption across product verticals,” says Devangshu Dutta, founder of management-consulting firm Third Eyesight.
The bets are also getting more varied, from Reliance Retail tying up with global brands like Fenty and Skims to the Bharti Group bringing Olive Garden to India.
The Lure of Returns
For a passenger walking through an airport, the flight is only one part of the journey. There is coffee before boarding, food between flights, a lounge, retail outlets, parking and a host of other things to spend money on. For Adani Airports, those non-aero businesses are increasingly becoming the more lucrative part.
Its non-aero operations already generate about ₹2,500cr, with returns in the high-20% range, against roughly 12% from regulated aeronautical operations.
Jeet Adani, director of Adani Airport Holdings, expects the share of aeronautical revenue to fall to around 10% of total revenue, with non-aero becoming the bigger growth driver. The motivation can be seen as an escape from a return ceiling as much as a bet on rising affluence.
As Kumar puts it, consumer businesses help the conglomerates in two major ways. First, they help insulate them from volatile and often punishing commodity cycles, and second, they often offer far better returns with lower capital intensity and faster cash conversion.
Reliance Industries (RIL) shows how significant that shift can become. By 2025–26, its consumer-facing arms, Jio Platforms, Reliance Retail Ventures and Reliance Consumer Products, together contributed over 40% of group revenue and nearly 60% of operating profit.
And there is another advantage. “A small business, when it wants to build a new venture, faces constant margin pressure and often has to build its supply chain from scratch. A large conglomerate can leverage its existing scale, infrastructure and supply chain to enter a new business far more efficiently,” explains Kranthi Bathini, equity strategist at WealthMills Securities.
Different Strokes
In chasing consumers, some conglomerates are following the fastest-growing categories, while others are using their existing industrial capabilities to enter consumer-facing businesses. One is trying to build an entire ecosystem around it. But the lines between these approaches are not always clean.
Tatas is doing both: building entirely new consumer brands while also using the industrial ecosystem it has built over decades.
For Tatas, the consumer opportunity has largely been about following where spending is moving. Their consumer ventures have followed this arc longest. It began decades ago with Lakmé (1952), Tata Tea (1962) and Titan (1984). Tanishq and the expansion of Trent under brands such as Zudio are only the latest examples.
At Tata Consumer Products, once largely a staples business built around salt, tea and pulses, the focus has been shifting towards value-added foods and beverages, with ₹7,000cr spent on the acquisitions of Capital Foods and Organic India in 2024. Across companies such as Tata Digital, Indian Hotels, Air India and Tata Motors Passenger Vehicles, the group has announced close to ₹93,180cr in investment over the past five years.
Aditya Birla’s jewellery chain Indriya and its move into premium hospitality belong to the same category of ‘pull-based’ diversification.
JSW is taking a different route. It is taking its existing industrial strengths one step closer to the buyer. The group, which has traditionally been focused on areas such as steel, energy and cement, has expanded into consumer-facing areas such as auto, paints and home solutions.
It launched JSW Paints in 2019, and acquired a controlling stake in paintmaker AkzoNobel India for ₹8,986cr last year. Its strategy is to leverage an established network of contractors, dealers, architects and builders to reach consumers.
The same strategy can be seen in its push into autos, acquiring a 35% stake in the Indian unit of China’s MG Motor in 2024, leveraging synergies with its established steel business.
At Tatas, too, group companies like Tata Steel, Tata Power, Tata AutoComp, Tata Technologies and TCS are doing significant businesses with Tata Motors.
Adani is also using an asset it already controls to move further into the consumer’s wallet. Adani Airports announced a ₹20,000cr investment in June to develop hotels, retail, entertainment and commercial infrastructure around its eight airports, and has signed hotel management agreements with IHG Hotels & Resorts for five hotels. City-side developments could contribute 30–40% of Adani Airport Holdings’ non-aero revenue.
Yet another example of the extension strategy is Aditya Birla Group’s attempt to diversify from cement, metals and textiles into decorative paints with Birla Opus.
RIL took a different approach: trying to connect multiple consumer businesses into one ecosystem. It expanded its retail network through new formats and acquisitions, added brands and partnerships, and then built a consumer-goods business around acquisitions such as Campa Cola and Lotus Chocolate.
That expansion was helped by billions of dollars raised by both Jio Infocomm and Retail Ventures from foreign investors in 2020. The group now plans to spend another ₹8,000cr expanding consumer goods manufacturing. The advantage of having that kind of scale is clear. If RIL has Ajio at a mall and, next to it, GAP and Herschel, it can negotiate better rental terms.
For conglomerates, Kumar points out, the next level of competition will not be based on investment, “but on the ability to create different consumer experiences, foster innovation and create lasting brand loyalty through the integration of these capabilities”.
Can Scale Win?
When Reliance Fresh opened its first stores in 2006, it was part of a rush by some of India’s biggest business groups to crack organised retail. Aditya Birla Group, RP-Sanjiv Goenka Group’s Spencer’s and Kishore Biyani’s Future Group were all betting that organised retail could transform the way Indians shopped. What followed was years of experimentation, losses and, for some, eventual retreat.
Birlas essentially gave up on grocery retail after a decade of heavy losses and exited entirely.
Future was pushed into insolvency after a controversial ₹24,713cr deal with RIL. Spencer’s is still trying to find its footing, with ₹249.33cr in net losses in 2025–26.
Conglomerates may have deeper pockets, but that does not automatically make them better at selling to consumers. India has seen some of those bets fail or take years to work. And even among today’s biggest players, the results are still mixed.
Tata Sons has been in this segment longer than the Ambanis, yet its consumer businesses still make up less than 40% of its total revenue —a share that has not changed since 2020.
These groups have what most standalone consumer companies don’t: capital, distribution, infrastructure, brands, scale.
But winning consumers takes something else entirely—reading what people want, building brands, innovating fast and earning loyalty.
“In B2B [business to business], it’s about manufacturing at scale, getting your costs down. Then you can compete. In B2C [business to consumer], it’s all about the product. With the right product at the right price, you have a chance to win in the market,” Parth Jindal, managing director of JSW Cement and JSW Paints, told Outlook Business in 2025.
Tata Sons’ chairman N Chandrasekaran hit the same wall while revamping the group’s consumer unit. “I have the money. But I don’t have the team to run it,” he had told Sunil D’Souza while hiring him to lead Tata Consumer Products in 2020.
Reliance and Tatas have had the longest head start, but even their journeys show how difficult it is to turn scale and capital into consumer businesses. Birla, JSW and Adani are now trying to make that transition in their own ways.
A longer tail—Bajaj in hospitals, L&T in retail finance and education, Mahindra in insurance and hospitality, Murugappa in electric mobility—is playing it safer, going deeper into what it already owns rather than chasing new categories.
What ties them together is a bet on consumers buying not just more but better, and on those consumers being worth more per rupee of capital than the industrial customers who built these houses.
The prize is growing, but so is the competition. Capital and scale may get these conglomerates through the door. They won’t guarantee a seat at the table.
(Published in Outlook Business)
admin
July 27, 2026
Vaeshnavi Kasthuril, MINT
Bengaluru, 27 Jul 2026
Over the past six years, Trent Ltd has grown its revenue more than fivefold, outpacing Titan Co. Ltd, Tata Consumer Products Ltd (TCPL) and Voltas Ltd to become the fastest-growing established company in Tata Sons’ consumer and retail portfolio.
Trent, incorporated in 1998, is the youngest among the Tata group’s four major listed consumer businesses. Voltas was incorporated in 1954, TCPL traces its origins to Tata Tea, established in 1962, while Titan was incorporated in 1984.
While Titan remains the group’s largest consumer business by revenue, Trent has overtaken Voltas and nearly caught up with TCPL.
Trent’s revenue rose to ₹20,189 crore in FY26 from ₹3,635 crore in FY20, showed Tata Sons’ FY26 annual report. In comparison, Titan’s revenue expanded 4.2 times, while TCPL and Voltas grew 2.1 times and 1.8 times, respectively. Six years ago, Trent accounted for just 8.6% of the combined revenue of the group’s four major consumer businesses. In FY26, that share has climbed to 14.1%, close to TCPL’s 14.3%.
Trent’s portfolio includes Westside and Zudio in fashion, Samoh and Burnt Toast in newer lifestyle formats, and Star in grocery retail.
Zudio effect
The growth has been driven by Trent’s aggressive expansion across value and premium fashion. Zudio has emerged as the retailer’s biggest growth engine, benefiting from rising demand for affordable fashion among middle-income consumers, while Westside has continued to strengthen its presence in the premium apparel and lifestyle segment.
Zudio has been “a phenomenal driver of revenue growth”, with the retailer aggressively expanding the format over the past few years, said Devangshu Dutta, founder of retail consulting firm Third Eyesight.
He said Trent has also benefited from a structural shift in the country’s retail landscape as consumers increasingly move from fragmented, unorganised markets to organised retail. “The conversion from informal to formal happens not so much driven by demand but by availability. So if you open a new outlet… you have something which was not there earlier, which becomes a magnet for footfall,” Dutta said.
He said that Zudio’s combination of fashion-led products and sharp pricing has helped it stand out in the crowded value apparel market.
The retailer has simultaneously expanded beyond apparel into adjacent categories such as beauty and personal care, home décor, footwear, and accessories through Westside, while also nurturing newer concepts, including Samoh, Burnt Toast, and Star.
During FY26, Trent added 289 stores, taking its total network to 1,286 outlets across 321 cities and expanding its retail footprint to more than 17.7 million sq. ft.
The company said it sees opportunities to increase store density in existing markets while expanding into new cities, particularly as demand for organized retail continues to deepen beyond the country’s largest metropolitan areas.
The next phase of growth is likely to be driven by Westside. According to media reports, Trent plans to significantly accelerate the expansion of its flagship premium fashion chain by opening up to 100 stores annually, nearly double its historical pace. The chain, which had 300 stores at the end of FY26, is expected to expand into newer geographies, including the northeastern states, while strengthening its presence in key metropolitan markets.
Dutta said macroeconomic uncertainty, including the impact of geopolitical tensions and softer employment conditions, could weigh on discretionary spending. “If there is uncertainty, then you tend to be a little bit more careful,” he said.
Dutta said that while consumer demand may fluctuate in the short term, the long-term shift towards modern retail remains firmly intact.
Noel Tata’s farewell message
The FY26 annual report also carries Noel Tata’s final message as chairman of Trent, marking the end of an era for the retailer he helped transform into one of India’s largest fashion retailers.
Tata reiterated his long-held ambition of building Trent into a platform capable of creating and scaling multiple consumer businesses rather than relying on a single retail format. “I have long believed that Trent is not intended to be defined by a single brand, but rather by a portfolio of brands,” he wrote, adding that Westside, Zudio and Star continue to have significant runway for growth.
Looking ahead, he said Trent should aspire to build Indian brands with global relevance and generate a material share of revenues from overseas markets.
He also recalled his vision, first articulated in 2023, of making Trent ten times larger in terms of revenue with commensurate profitability, noting that the company’s revenue and profitability run rate have already grown more than 2.5 times since then.
The company has not yet named a successor to Noel Tata, who is set to retire as chairman in November.
(Published in MINT)
admin
June 12, 2026
Christina Moniz, Financial Express/Brand Wagon
12 June 2026
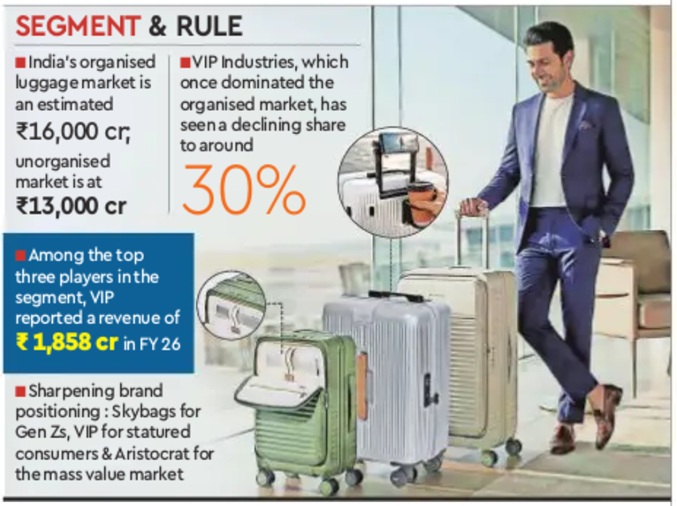
Legacy luggage brand VIP Industries is shedding some of its old baggage. The company, which manufactures Skybags and Aristocrat along with its flagship VIP range, has gone beyond cringey makeovers solely to attract Gen Z, and has embarked on a transformation journey that leverages its legacy to purvey a fresh range of offerings.
The company is modernising its digital presence and supply chain to catch up with competitors.
Managing director Atul Jain admits that the company has been a bit slow on the e-commerce front. It is reinventing its online store, while also making its products available across other e-commerce channels. “Quick commerce is becoming an important channel since there are several use occasions and segments within the luggage market. For instance, consumers often make last-minute purchases for a weekend trip via quick commerce. School bags and backpacks for kids, also great gifting options, are seeing good demand on these platforms,” he says
The company, which once dominated the ₹16,000 crore organised luggage market in India, saw a bit of a shakeup last year when the Piramal family sold 32% of its stake to a private equity firm. But it continues to be among the top three players in the category with a 29-30% market share. “Luggage plays the role of a traveller’s companion. We are creating designs to fit that role,” says Jain. “For example, our new VIP suitcases have a coffee cup holder and our cabin trolley bag has an easy access compartment for devices like laptops and iPads.”
The transformation goes beyond the product. VIP’s 350 exclusive physical retail touchpoints in the country are being revamped to offer a new customer experience.
Unpacking opportunities
Overits 55 years, VIP has grown from a briefcase brand into Asia’s largest luggage maker, housing labels like Skybags, Aristocrat, and Carlton (premium segment). While VIP is a premium offering targeted at business and travellers, its Aristocrat brand operates in the mass market and the budget-friendly Alfa targets consumers who typically shop in the unbranded segment. Aristocrat and Alfa together contributed upwards of 40% to the company’s revenue in FY25, followed by Skybags (28%) and VIP (20%).
Like many legacy brands, the VIP Industries’ faces the challenge to ia, stay relevant among Gen Z buyers as a plethora of digital-first brands swamp the market. “VIP has lost ground on relevance and desirability to a generation for whom luggage, like sneakers, is an expression of identity. To them, VIP feels like their parents’ brand,” says Nisha Sampath, managing partner, Bright Angles Consulting. D2C players in the category operate in the business of “lifestyle accessories” and not for “luggage” per se, she points out.
With a design-forward approach, incorporating features like compression systems, silent wheels and charging ports, these new-age brands have embedded themselves in travel “culture”, while also being Instagram worthy, say experts.
Jain says Skybags is VIP’s Gen Z focussed brand, which has over 8,20,000 Instagram followers. “We are sharpening our positioning for Skybags in our design, advertising and marketing outreach, especially on social platforms. The brand has a clear differentiation with youthful colours and prints to attract younger consumers,” he adds.
While D2C players have seen notable growth in recent years, they don’t have the kind of trust and brand equity that VIP has cultivated across its brands, nor do they have the scale or revenue that legacy brands have, he says.
Experts believe there is a significant growth opportunity for legacy players given that the unbranded market still accounts for ₹13,000-14,000 crore. The important lever for legacy brands is to clearly demonstrate value beyond price. “The unorganised market competes heavily on affordability, so organised players need to communicate durability, warranty, after-sales service, and consistent quality – areas where they have a strong inherent advantage over unorganised alternatives,” says Praveen Govindu, partner at Deloitte India. He adds that these brands should also invest in advertising and communicate this value to the end consumer.
Not only are the needs different among different consumer groups, competitive pressures are also diverse. “VIP can segment the market more cleanly with its portfolio of brands if it maintains absolute distinction to ensure clear consumer targeting across not just product attributes and pricing, but also communication and channels,” says Devangshu Dutta, CEO, Third Eyesight.
(Published in Financial Express)
admin
May 25, 2026
Vaeshnavi Kasthuril, MINT
Bengaluru, 25 May 2026
Value fashion retailers across the country are likely to face margin pressure in the upcoming quarters as rising crude oil prices are driving up the cost of polyester and other fabrics. Executives at V-Mart Retail Ltd, Vishal Mega Mart Ltd, and Kewal Kiran Clothing Ltd (KKCL) said crude oil-linked inflation has begun to push up yarn and sourcing costs across apparel and general merchandise categories, with the full impact expected to play out over the next few months.
Value fashion retailers face a double whammy: their heavy reliance on polyester and synthetic blends exposes them to crude-linked inflation, while their price-sensitive customer base leaves little room to pass on rising costs without hurting demand.
Apparel contributes about 22.8% of the overall revenue of the country’s largest retailer, DMart, in FY26. Rising polyester and fabric prices could also weigh on this share, which has been declining since FY20.
“We see almost 60% to 70% consumption of polyester yarn or poly-based product lines, which have or will get impacted,” said Lalit Agarwal during the company’s March-quarter earnings call. Agarwal said that yarn prices had already risen sharply in recent weeks. “There is a rise of almost 10% to 15% in the yarn prices, which effectively converts to almost 5% to 7% in the apparel prices,” he said.
“Cost increases are at multiple points. One, of course, is raw material, which is not only fabric, but also polyester buttons, thread, packaging, all of that,” Devangshu Dutta, founder of Third Eyesight, a consulting firm, said. “Because with value, you cannot really pass on the price hikes so readily to the consumer.”
Dutta said that lower- and middle-income consumers were already under financial stress from broader inflationary pressures, “so, they will not be able to absorb price hikes as easily as well.”
Ebitda margins in Q4FY26 are 10.9% for V-Mart Retail, 13.6% for Vishal Mega Mart and 19.1% for Kewal Kiran Clothing.
Double whammy for value segment
Gunender Kapur, CEO of Vishal Mega Mart, during the company’s March-quarter earnings call, said the inflationary impact had started becoming visible towards the end of April and would likely intensify in the coming months.
Despite rising input costs, retailers said they are avoiding broad-based price hikes on entry-level products amid fragile demand conditions in the value segment.
Entry-level products for these retailers range from ₹199 to ₹399, with some going up to ₹1,500.
“We would never tinker with the opening price points and the lower price points in these difficult times, because those are the customers who are the most vulnerable in inflationary situations,” Kapur said.
Hemant Jain, CEO of KKCL, said the company was willing to absorb part of the pressure on profitability to protect revenues and market share.
Jain also said the company had not yet implemented price hikes despite the inflationary environment.
To cushion the impact, companies said they are increasingly relying on cost optimisation, fabric innovation, premium fashion products and deeper expansion into smaller towns to sustain growth.
V-Mart said it was attempting to offset part of the inflation through alternative fabric usage, sourcing efficiencies and tighter inventory planning.
The retailer has also blocked orders in advance and is utilising existing yarn and fabric inventories available with vendors to soften the immediate impact of rising prices.
Vishal Mega Mart’s Kapur said it has revived cost-saving measures from the post-Ukraine cotton inflation cycle, including replacing cartons with gunny bags, removing polybags from some apparel categories, and shipping footwear without outer cartons.
The retailer has also increased the use of computer-aided design systems to reduce fabric waste during cutting.
Premium products, private labels offer buffer
These value retailers are also increasingly depending on premium and higher-fashion assortments, where consumers are relatively less price sensitive, to absorb selective price increases while keeping entry-level products affordable.
Kapur said Vishal Mega Mart’s large private-label portfolio, which contributes over 74% of its revenue, gives it greater flexibility to manage pricing pressure while maintaining discounts against national brands.
KKCL on the other hand, said it would absorb part of the inflationary impact rather than immediately pass on higher costs to consumers.
These retailers are also increasingly leaning on expansion into smaller towns and deeper markets to drive incremental growth as discretionary spending in larger urban centres remains uneven.
Value fashion retailers have underperformed the broader market amid growing concerns over rising input costs and margin pressure. Shares of V-Mart Retail, V2 Retail Ltd, Vishal Mega Mart and Kewal Kiran Clothing have fallen between 4% and 11% on a year-to-date basis, while the benchmark BSE rose 6.1% during the same period.
(Published in MINT)
admin
May 15, 2026
The ET Now Swadesh panel discussion focussed on the dual challenge facing the Indian economy: a weakening rupee and rising crude oil prices, which together are driving “imported inflation” and straining household budgets. Devangshu Dutta (Founder, Third Eyesight) put forth the following key points during the discussion (the video link is under the text summary below):
1. Dual Impact on Industry and Consumers:
2. Vulnerability of Small Businesses (SMEs):
3. Income vs. Expenditure Strain:
4. Ripple Effect of Crude Oil Beyond Logistics:
5. Shifts in Consumer Spending Patterns & “Shrinkflation”:
The panel noted that while the Reserve Bank of India (RBI) has adequate foreign exchange reserves to defend the rupee temporarily, the definitive solution relies heavily on the cooling down of global geopolitical tensions (such as the Middle East conflict affecting the Strait of Hormuz). Until then, Indian consumers will need careful financial planning and smart spending adjustments to navigate this inflationary phase. [Video below.]
