admin
October 29, 2026
Pritha Pahari, The Core
29 Oct 2026
When ITC Ltd. launched Aashirvaad in May 2002, it sold one thing — whole wheat flour. The brand now has more than 200 SKUs across staples, spices, fresh foods and frozen foods.
ITC wants to double what Indians spend on Aashirvaad to Rs 20,000 crore in five years. It said growth will come from two places: more premium atta, and new categories around the Indian kitchen. That makes the brand a test of a hard question in packaged food. Can a name built on the purity of an ingredient win in the other segments and break out from its identity built around atta?
Trust in the purity of flour may not translate into trust in ready-to-eat meals, where taste, consistency and repeat purchases matter more. ITC itself has bought brands and built separate ones for some of these jobs.
A Big Target, A Soft Core
Hemant Malik, who runs ITC’s foods division, told PTI the company expects spending on Aashirvaad to double from above Rs 10,000 crore. That figure is what shoppers pay, including taxes and trade margins. It is not ITC’s revenue. The push comes as the core product slows. In the quarter ended June 30, ITC said atta was held back by heat waves, an LPG shortage and low wheat prices.
FMCG-Others revenue rose 12%, or 16% without staples, and dairy, snacks, noodles and frozen snacks each grew more than 20%. Not all of that belongs to Aashirvaad. Snacks, noodles and frozen foods sell under Bingo!, YiPPee! and ITC Master Chef.
The wider backdrop matters too. ITC is trying to rely less on cigarettes, which now face a sharp rise in tax.
Devangshu Dutta, founder of consultancy Third Eyesight, said value-added ready-to-cook and ready-to-eat products earn better gross margins than staples. Selling more of them would also help ITC use its factories more fully, he said.
ITC’s recent annual report shows multigrain atta, vermicelli and besan have grown threefold over five years, and now make up about 16% of the staples portfolio. ITC does not give a brand-level split between premium atta and new categories, or Aashirvaad’s profit.
ITC’s own Q1 FY27 release said atta performance was tempered by transient factors including heat waves, an LPG shortage and benign wheat prices. The FMCG-Others business grew 12% in the quarter.
The Easy Stretch
ITC said its value-added atta variants and staples-related products have grown three-fold in five years, and their share of the portfolio has doubled. They include besan, rava, vermicelli and soya chunks. The newest addition is chana sattu, first sold in Bihar, Jharkhand and West Bengal, with a Rs 10 pack that carries 10 grams of protein.
Suumit Kapoor, a brand growth consultant, calls these safe stretches. Besan and rava barely change what a shopper expects, he said. They are “still about what’s in the bag,” so purity still answers the question.
The Harder Jump
Ready-to-cook and ready-to-eat food asks something different. “Purity is a raw material promise. Ready to eat is a finished experience,” Kapoor said. Nobody buys a packaged curry because the dal was well sourced, he said. They buy it because they are hungry, short of time and hoping it tastes home-cooked.
ITC’s recent launches show it knows this. Its ready-to-cook chapati comes in packs of 10, with no preservatives and a shelf life of five to six days. The chutney and sambar range, launched in June, is made in small batches without preservatives and depends on a cold supply chain.
At launch it was sold only in Bengaluru through quick-commerce apps. The short shelf life answers a real problem.
Dutta said many shoppers prefer freshly cooked, hot meals and are wary of additives that extend shelf life. Cold chains remain patchy even in big cities, he said. A time-pressed household can also cook, order in, eat out or buy a packaged meal, and each choice is judged on price, convenience and taste.
Kapoor added a caution about ITC’s own numbers. They do not show whether shoppers buy the new products because of the Aashirvaad name, or simply because those categories are growing.
ITC’s latest results release names ready-to-cook chapati in a list of products but gives no sales figure for it, or for ready-to-eat meals. That may reflect how ITC groups its figures, not a change in plans.
Why One Name Still Makes Sense
Dutta sees a strong business case for using one name. A familiar brand cuts the cost of getting shoppers to try something new, he said, because Aashirvaad is already in millions of homes. New items can also move through ITC’s existing distribution, including modern trade and quick commerce, and retailers accept extensions from a leading brand more readily than unknown labels.
He also sees a defensive motive. Aashirvaad sits in everyday kitchen use, between ITC’s older gourmet line, Kitchens of India, and its snack-led Sunfeast. A bigger range puts it up against MTR, Haldiram’s and iD Fresh.
Tata Consumer said Tata Sampann grew 69% in Q4 FY26 with strong performance across categories. On the Q1 FY27 earnings call, CEO Sunil D’Souza said the core portfolio of pulses, spices, poha and vermicelli was growing at about 30%, with cold-pressed oils and dry fruits adding to that growth.
Poha and vermicelli are the closest items to convenience foods, but Tata doesn’t separate them out.
AWL Agri Business, which owns Fortune and Kohinoor, reported Q1 FY27 Food & FMCG revenue of Rs 1,726 crore, up 22%, with a segment EBITDA margin of 6%, and management said the Fortune and Kohinoor brands both grew at double-digit rates. AWL’s investor day deck also shows Kohinoor rising from Rs 150 crore in FY23 to over Rs 400 crore in FY26.
Not Betting Only On The Name
ITC’s record suggests it does not rely on one brand for everything.
It launched Kitchens of India in 2001 as a separate premium name, using the dishes of its hotel restaurants. It bought the spices brand Sunrise in 2020. In February 2025, it agreed to buy Prasuma, a frozen and ready-to-cook company, starting with a 43.8% stake. Sproutlife Foods, the Yogabar business, became a subsidiary on April 1.
Mint reported in February 2025, citing two unnamed people, that ITC was in early talks to buy MTR Foods and Eastern Condiments from Norway’s Orkla for about $1.4 billion. Orkla said it does not comment on rumours. ITC did not reply to Mint. No deal followed.
Kapoor reads such moves as ITC buying skills it lacks, not as proof that Aashirvaad cannot stretch.
ITC is also putting weight behind fresh food. Its fresh food business, which includes a brand called ITC Aashirvaad Soul Creations, grew gross order value 90% in the quarter, passed an annual revenue run rate of Rs 300 crore and now runs 75 cloud kitchens in five cities.
What Comes Next
The company’s position is strongest where the brand started. In July, ITC said it had already secured 95% of the wheat of the quality needed for Aashirvaad atta, but it also warned that monsoon rains were short and El Niño could hurt growth.
Value-added atta variants and staples adjacencies have grown three-fold over five years, and Aashirvaad Svasti dairy is among its fastest-growing categories, but neither is a meal category.
The newest meal-type launches, such as ready-to-cook chapatis, frozen naans and parathas, and fresh chutneys and sambar, have no disclosed sales or repeat-purchase data.
ITC launched Aashirvaad ReadyMeals back in 2003 and still describes ready-to-cook as a new bet, and it markets other finished-food lines under separate brands (Kitchens of India, ITC Master Chef, Prasuma), which suggests it doesn’t simply assume the Aashirvaad name carries into every meal category.
Management frames success around product innovation and differentiation, not brand trust alone. The larger test is on the shelf.
Kapoor said staples-linked products can keep drawing on Aashirvaad’s purity, but anything close to a finished meal has to earn a name for taste and consistency. Whether shoppers will pay for that under the Aashirvaad label is what ITC’s Rs 20,000 crore target depends on.
(Published in The Core)
admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
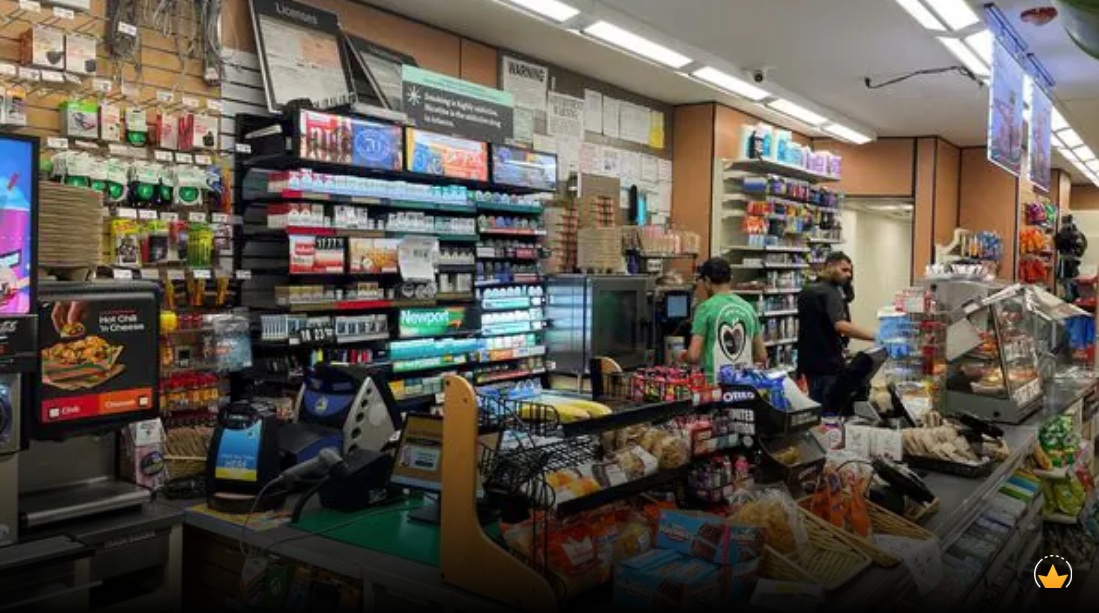
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
October 5, 2026
Sagar Malviya, Economic Times
5 October 2026
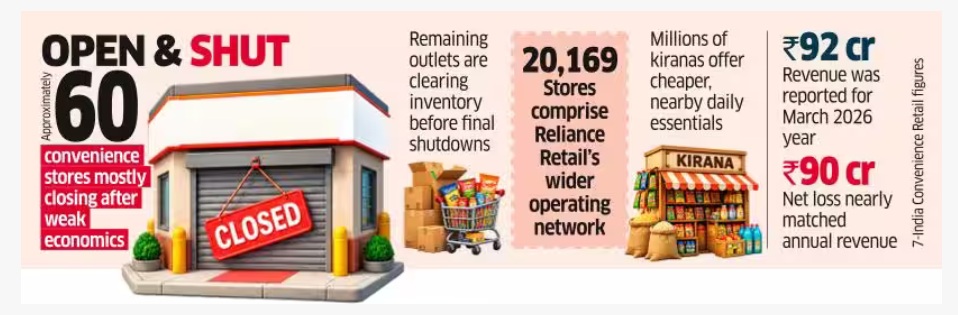
Reliance Retail and 7-Eleven are ending their five-year franchisee deal in India, closing most of the nearly 60 convenience stores they operated under the partnership, after struggling to make the format profitable, people familiar with the matter said.
A handful of outlets are clearing the inventory before shutting, they said. 7-Eleven may look for another Indian partner to keep a foothold in the market, although no decision has been made, the people said.
The exit highlights an unusual squeeze that convenience stores are facing in India, with millions of small kirana stores that have long served consumers’ immediate needs on one side and quick-commerce companies that are bringing the same snacks, groceries and daily essentials to doorsteps within minutes on the other.
Reliance and 7-Eleven did not respond to ET’s queries.
The partnership, struck in 2021, was intended to bring the world’s largest convenience-store chain to India through Reliance’s retail network. But the business struggled to achieve the scale needed to offset the relatively high costs of running branded stores.
The 7-India Convenience Retail venture reported revenue of about ₹92 crore ($10.6 million) and a net loss of nearly ₹90 crore in the year ended March 2026, according to its financial statements.
“Reliance wants to reach consumers across every channel, but sustainability ultimately matters. Convenience stores have faced increasing pressure from quick commerce since the pandemic, with both formats offering similar assortments and serving the same immediate-needs occasions,” said Devangshu Dutta, founder and CEO of Third Eyesight, a consumer-sector consultancy.
“Kiranas operate with far lower overheads and different margin expectations than corporate-run convenience stores. Reliance’s exit could therefore signal a broader rethink of the format, particularly in markets where quick commerce has become a strong alternative.”
Globally convenience stores have become powerful retail businesses in several markets despite the expansion of supermarkets and hypermarkets. 7-Eleven in Japan, Taiwan, Thailand and Singapore; Lawson in Japan and Oxxo in Mexico are among the largest retailers in their respective markets.
7-Eleven’s Japanese parent, Seven & i Holdings, operates more than 85,000 stores globally, making it one of the world’s largest retail networks. Yet the company has been restructuring its overseas operations and closing stores in North America as consumer behaviour and store economics change.
In India, however, organised convenience retail has struggled to replicate the success seen in other Asian and emerging markets. EasyDay, More and Spencer’s have either shut stores or shrank their smaller-format networks over the years, underscoring the difficulty of building profitable neighbourhood stores at scale.
Packaged consumer goods companies continue to derive roughly three-fourths of their sales from small neighbourhood stores, underlining the strength of the traditional distribution network. Quick commerce platforms are, meanwhile, expanding rapidly.
That makes it difficult for organised convenience stores to charge a premium or generate sufficient sales density to cover higher rents, staffing, inventory and logistics costs.
Convenience retail works best when operators achieve high store density and productivity, supported by strong supply chains and differentiated offerings such as fresh food and private labels.
Reliance initially expanded the 7-Eleven network in Mumbai and other markets, but the footprint remained small compared with the company’s wider retail operations.
(Published in Economic Times)
admin
September 26, 2026
Kartikay Kashyap, Brand Wagon/Financial Express
25 September 2026
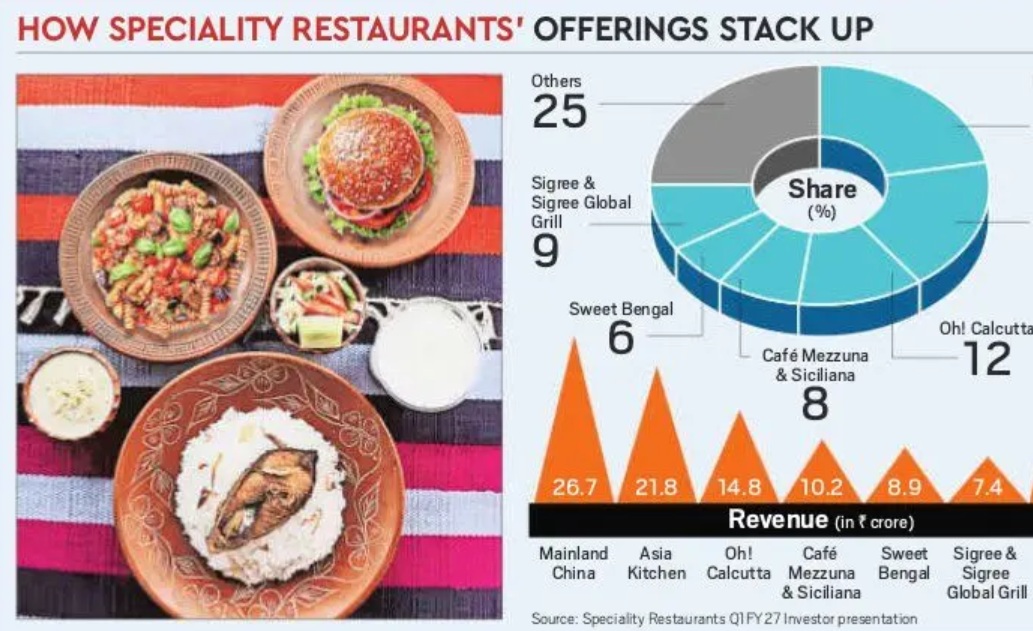
Walters Burger and Sweet Bengal could turn out to be the lynchpin of Speciality Restaurants’ expansion plan this year, helping it capture the fast-growing high-margin quick service restaurant (QSR) and cloud kitchen markets. Known for its sit down fine dining brands like Mainland China and Oh! Calcutta, Speciality Restaurants is working to expand a smaller selection of highly scalable brands. By aggressively rolling out physical stores alongside integrated cloud kitchens, like it has done across Mumbai and Pune, the 34-year old brand is looking to establish a massive delivery footprint with a highly optimised overhead.
Take designed-for-delivery Walters Burgers, for instance. Instead of offering massive, vertically stacked burgers that turn messy during delivery transit, it specialises in pairs of medium-sized, structurally sound gourmet burgers designed for a one-handed, mess-free eating experience.
This structural integrity makes it perfect for both high-volume delivery channels and curbside pickup.
Anjan Chatterjee, CMD, Speciality Restaurants, says Walters Burgers allows the company to “participate in the large and growing QSR/gourmet-burger opportunity through a format that is scalable and can address a younger consumer base”.
For its part, Sweet Bengal, rooted in Bengali culinary heritage, has a significant potential to take traditional sweets and gifting beyond their existing markets.
“Together, they demonstrate that our expansion strategy is not dependent on one format or one price point,” Chatterjee says. “We are building a portfolio across occasions ― from everyday consumption and affordable indulgence to premium dining and traditional gifting ― while leveraging the strength of our existing brands.”
As the food industry grapples with ingredient inflation, high cost of fuel and slowing discretionary spending, the company’s expansion strategy is going to be “cautious and sustainable”. It will open 20-25 new outlets every year.
Devangshu Dutta, founder, Third Eyesight, believes that Speciality Restaurants’ multi-brand portfolio spanning diverse cuisines, price points and formats has given it the opportunity to diversify risk during these uncertain times. “Restaurants are vulnerable to fashionability and economic swings like other discretionary, lifestyle businesses. Catering to varied dining occasions ― from casual impulse buys to premium dining ― the company has a wide consumer base, with a cushion against changing consumer preferences,” says Dutta.
Starting his journey in 1992 with a 40-seater dining outlet, Only Fish (now Oh! Calcutta), in Mumbai, the company’s house of brands now includes Asian and Oriental offerings Mainland China, Asia Kitchen, GONG and HAKA; North Indian and royal Mughal flavours Riyasat and Sigree, and buffet formats Global Grill and Flame & Grill. It launched Siciliana earlier this year to offer Italian flavours. In June, Chatterjee’s son Avik took over as CEO and currently holds the reins of its expansion engine.
Recipe for success
Speciality Restaurants operates 118 outlets and has a large presence in the Eastern and Western parts of the country. It operates Oh! Calcutta and Mainland China in Delhi and is planning to launch Gong in Vasant Kunj, Delhi, soon. The Kolkata-based company sees opportunities across markets like the National Capital Region, Chandigarh, Jaipur, Lucknow, among others. “Our expansion will remain market-led rather than driven by geographical presence. With a diversified portfolio, we have the flexibility to identify the right brand and format for the right market,” says Chatterjee.
But operating a disparate range of brands has its own set of challenges. “Managing separate supply chains for vastly different cuisines introduces complexity and cost,” says Third Eyesight’s Dutta.
Also, every new brand entails developing a separate brand identity. “They cannot follow the same marketing playbook for every brand,” says Ankur Bisen, senior partner, The Knowledge Company.
One might argue that many FMCG companies also have a large portfolio of brands, addressing the needs of different cohorts. But Bisen says product segments and services segments have different business realities. “The fixed cost is fairly low in the case of product companies which is why large FMCG companies can launch or manage multiple brands simultaneously. But the fixed cost in the food services sector is relatively high,” he shares.
Ken Research estimates that India’s food services market was around ₹7.1 lakh crore in 2025 and is expected to grow at a CAGR of 7.7% to touch ₹11.9 lakh crore by 2032. QSR chain majors Jubilant FoodWorks, Devyani International, Sapphire Foods India, Westlife Foodworld and Restaurant Brands Asia dominate the sector.
But Speciality Restaurants proposition of a diverse set of cuisines and formats targeting different sets of consumers might actually be its trump card. Brand building is Speciality Restaurants’ forte, says Naresh Gupta, CSO & managing partner, Bang In The Middle, and it also knows the formula to scale.
(Published in Brand Wagon / Financial Express)
admin
September 1, 2026
Vikash Tripathi, Outlook Business
1 September 2026
Eight decades ago, the ‘nationalist businessman’ GD Birla helped prepare the ‘Bombay Plan’, which asked the state to pro-vide for the bare minimum needs of its people. His plan asked for 2,800 calories of well-balanced food per day, 30 yards of clothing per year and 100sq ft of housing per person.
Today, seventh-generation Aryaman Vikram Birla is betting on an entirely different opportunity: premium dining. “We continue to believe in the remarkable potential of the premium casual dining space, spurred by rising disposable income and evolving lifestyles,” the 29-year-old said after Aditya Birla New Age Hospitality acquired KA Hospitality in 2023.
The Birlas are not alone in trying to cash-in on rising prosperity in India. In the past five years alone, India’s top 10 industrial groups have announced new ventures in consumer-facing sectors or doubled down on existing ones. A rough tally of these investments crosses ₹4.8 lakh crore.
For decades, these same business houses built their dominance in core sectors like steel, power, aluminium, cement and chemicals, laying the industrial backbone of the economy. This helped the nation become a large producer of such goods and, in some cases, an exporter as well.
But as India’s economic conditions changed, so has the focus of its largest conglomerates.
For the likes of Tata, Aditya Birla, Bajaj and Bharti, that journey started way back. “What has changed in recent years is the speed and openness of the amount of capital being invested,” says Jitender Kumar, associate professor and programme chairperson, retail management programme at Birla Institute of Management Technology.
“It is not ‘opportunistic’ reasons, it’s structural reasons.”
Two factors seem to be driving the shift: the first is the arrival of an affluent consuming class that can buy branded and premium goods, and the second is the attraction of consumer businesses as a way to diversify revenue and, in some cases, improve the quality of earnings.
The Rise of Affluence
A couple of decades ago, if an Indian household had some extra cash, it often meant buying more of the same. Today, it increasingly means buying better. Even salt is being upgraded, from iodised to Himalayan pink or rock salt. The same shift is visible in bigger purchases: sports utility vehicles (SUVs) over hatchbacks, and ₹1cr-plus homes over budget flats.
But India isn’t simply consuming more. It is moving from basic consumption towards discretionary, branded and premium consumption. This boom is most clearly seen in the rapid expansion of the financial infrastructure that enables consumption. Formal retail credit penetration has more than doubled over the past decade, according to a TransUnion Cibil report, driven largely by personal loans, credit cards and consumer durable loans. Meanwhile, the government-backed Unified Payments Interface has untethered spending from the cash in a buyer’s wallet.
The signs show up across the broader consumption economy. Homes priced above ₹1cr accounted for 54% of total sales in 2025, up from just 30% in 2023—the market that decorative paints and home solutions are chasing.
Out of 4.7mn cars sold in the financial year 2025–26, SUVs accounted for more than half.
“The consumer market has grown substantially—not only through rising incomes but also the dramatic expansion of branded consumption across product verticals,” says Devangshu Dutta, founder of management-consulting firm Third Eyesight.
The bets are also getting more varied, from Reliance Retail tying up with global brands like Fenty and Skims to the Bharti Group bringing Olive Garden to India.
The Lure of Returns
For a passenger walking through an airport, the flight is only one part of the journey. There is coffee before boarding, food between flights, a lounge, retail outlets, parking and a host of other things to spend money on. For Adani Airports, those non-aero businesses are increasingly becoming the more lucrative part.
Its non-aero operations already generate about ₹2,500cr, with returns in the high-20% range, against roughly 12% from regulated aeronautical operations.
Jeet Adani, director of Adani Airport Holdings, expects the share of aeronautical revenue to fall to around 10% of total revenue, with non-aero becoming the bigger growth driver. The motivation can be seen as an escape from a return ceiling as much as a bet on rising affluence.
As Kumar puts it, consumer businesses help the conglomerates in two major ways. First, they help insulate them from volatile and often punishing commodity cycles, and second, they often offer far better returns with lower capital intensity and faster cash conversion.
Reliance Industries (RIL) shows how significant that shift can become. By 2025–26, its consumer-facing arms, Jio Platforms, Reliance Retail Ventures and Reliance Consumer Products, together contributed over 40% of group revenue and nearly 60% of operating profit.
And there is another advantage. “A small business, when it wants to build a new venture, faces constant margin pressure and often has to build its supply chain from scratch. A large conglomerate can leverage its existing scale, infrastructure and supply chain to enter a new business far more efficiently,” explains Kranthi Bathini, equity strategist at WealthMills Securities.
Different Strokes
In chasing consumers, some conglomerates are following the fastest-growing categories, while others are using their existing industrial capabilities to enter consumer-facing businesses. One is trying to build an entire ecosystem around it. But the lines between these approaches are not always clean.
Tatas is doing both: building entirely new consumer brands while also using the industrial ecosystem it has built over decades.
For Tatas, the consumer opportunity has largely been about following where spending is moving. Their consumer ventures have followed this arc longest. It began decades ago with Lakmé (1952), Tata Tea (1962) and Titan (1984). Tanishq and the expansion of Trent under brands such as Zudio are only the latest examples.
At Tata Consumer Products, once largely a staples business built around salt, tea and pulses, the focus has been shifting towards value-added foods and beverages, with ₹7,000cr spent on the acquisitions of Capital Foods and Organic India in 2024. Across companies such as Tata Digital, Indian Hotels, Air India and Tata Motors Passenger Vehicles, the group has announced close to ₹93,180cr in investment over the past five years.
Aditya Birla’s jewellery chain Indriya and its move into premium hospitality belong to the same category of ‘pull-based’ diversification.
JSW is taking a different route. It is taking its existing industrial strengths one step closer to the buyer. The group, which has traditionally been focused on areas such as steel, energy and cement, has expanded into consumer-facing areas such as auto, paints and home solutions.
It launched JSW Paints in 2019, and acquired a controlling stake in paintmaker AkzoNobel India for ₹8,986cr last year. Its strategy is to leverage an established network of contractors, dealers, architects and builders to reach consumers.
The same strategy can be seen in its push into autos, acquiring a 35% stake in the Indian unit of China’s MG Motor in 2024, leveraging synergies with its established steel business.
At Tatas, too, group companies like Tata Steel, Tata Power, Tata AutoComp, Tata Technologies and TCS are doing significant businesses with Tata Motors.
Adani is also using an asset it already controls to move further into the consumer’s wallet. Adani Airports announced a ₹20,000cr investment in June to develop hotels, retail, entertainment and commercial infrastructure around its eight airports, and has signed hotel management agreements with IHG Hotels & Resorts for five hotels. City-side developments could contribute 30–40% of Adani Airport Holdings’ non-aero revenue.
Yet another example of the extension strategy is Aditya Birla Group’s attempt to diversify from cement, metals and textiles into decorative paints with Birla Opus.
RIL took a different approach: trying to connect multiple consumer businesses into one ecosystem. It expanded its retail network through new formats and acquisitions, added brands and partnerships, and then built a consumer-goods business around acquisitions such as Campa Cola and Lotus Chocolate.
That expansion was helped by billions of dollars raised by both Jio Infocomm and Retail Ventures from foreign investors in 2020. The group now plans to spend another ₹8,000cr expanding consumer goods manufacturing. The advantage of having that kind of scale is clear. If RIL has Ajio at a mall and, next to it, GAP and Herschel, it can negotiate better rental terms.
For conglomerates, Kumar points out, the next level of competition will not be based on investment, “but on the ability to create different consumer experiences, foster innovation and create lasting brand loyalty through the integration of these capabilities”.
Can Scale Win?
When Reliance Fresh opened its first stores in 2006, it was part of a rush by some of India’s biggest business groups to crack organised retail. Aditya Birla Group, RP-Sanjiv Goenka Group’s Spencer’s and Kishore Biyani’s Future Group were all betting that organised retail could transform the way Indians shopped. What followed was years of experimentation, losses and, for some, eventual retreat.
Birlas essentially gave up on grocery retail after a decade of heavy losses and exited entirely.
Future was pushed into insolvency after a controversial ₹24,713cr deal with RIL. Spencer’s is still trying to find its footing, with ₹249.33cr in net losses in 2025–26.
Conglomerates may have deeper pockets, but that does not automatically make them better at selling to consumers. India has seen some of those bets fail or take years to work. And even among today’s biggest players, the results are still mixed.
Tata Sons has been in this segment longer than the Ambanis, yet its consumer businesses still make up less than 40% of its total revenue —a share that has not changed since 2020.
These groups have what most standalone consumer companies don’t: capital, distribution, infrastructure, brands, scale.
But winning consumers takes something else entirely—reading what people want, building brands, innovating fast and earning loyalty.
“In B2B [business to business], it’s about manufacturing at scale, getting your costs down. Then you can compete. In B2C [business to consumer], it’s all about the product. With the right product at the right price, you have a chance to win in the market,” Parth Jindal, managing director of JSW Cement and JSW Paints, told Outlook Business in 2025.
Tata Sons’ chairman N Chandrasekaran hit the same wall while revamping the group’s consumer unit. “I have the money. But I don’t have the team to run it,” he had told Sunil D’Souza while hiring him to lead Tata Consumer Products in 2020.
Reliance and Tatas have had the longest head start, but even their journeys show how difficult it is to turn scale and capital into consumer businesses. Birla, JSW and Adani are now trying to make that transition in their own ways.
A longer tail—Bajaj in hospitals, L&T in retail finance and education, Mahindra in insurance and hospitality, Murugappa in electric mobility—is playing it safer, going deeper into what it already owns rather than chasing new categories.
What ties them together is a bet on consumers buying not just more but better, and on those consumers being worth more per rupee of capital than the industrial customers who built these houses.
The prize is growing, but so is the competition. Capital and scale may get these conglomerates through the door. They won’t guarantee a seat at the table.
(Published in Outlook Business)
