admin
September 1, 2026
Pritha Pahari, The Core
1 September 2026
Reliance has spent more than a decade bringing together a long list of names such as Burberry and Tiffany & Co. to India. Its latest focus seems to be luxury celebrity brands, adding global pop star Rihanna’s Fenty Beauty and now media personality Kim Kardashian’s shapewear label SKIMS to its luxury brands portfolio.
Isha Ambani, executive director of Reliance Retail, has fronted most of these announcements herself.
Meanwhile, Nykaa, the beauty platform Reliance Retail keeps getting compared to, spent the last year going after some of the same celebrity founders.
In August 2025, Fenty Beauty moved from Nykaa’s platform to an exclusive deal with Reliance’s Sephora India and Tira. In June 2026, Nykaa answered by signing pop star Selena Gomez’s Rare Beauty. A month later, Reliance landed SKIMS.
India’s luxury and celebrity-brand market is split between Reliance’s scale and Nykaa’s beauty expertise, with Fenty, Rare Beauty and SKIMS showing how ownership, reach and brand fit are shaping who gets the biggest names.
Big Brands, Different Bets
Reliance wins brands through scale (20,169 stores, 396 million customers) and ownership ties; Fenty’s move to Sephora India is less a market choice than an internal LVMH routing decision, given LVMH’s stakes in both Fenty and Sephora.
But Nykaa is holding its own by competing on specialism, not size; its beauty-literate audience and curated community pulled in Rare Beauty and Chanel.
The brand fit, not just distribution muscle, still decides who signs where, and some brands (like Birkenstock) skip both platforms entirely.
The economics behind these deals are harder to pin down than the headlines suggest. None of the three — Fenty, Rare Beauty, or SKIMS — have disclosed minimum guarantees, royalty rates, or sales targets for their India entries; these are announced as partnerships, not filed joint ventures.
SKIMS raised $225 million in November 2025 at a $5 billion valuation, nearing $1 billion in annual net sales.
Fenty tells a different story: $450 million in 2024 sales, now valued at $1-2 billion, down sharply from a $2.8 billion estimate in 2021, with Jay-Z’s MarcyPen Capital Partners in talks to buy LVMH’s stake.
Rare Beauty’s India entry rides on Nykaa’s own momentum; the company’s revenue from operations rose 29% year on year (YoY) to Rs 2,782 crore in Q1 FY27, up from Rs 2,154.9 crore a year earlier. In the last quarter of FY26, revenue stood at Rs 2,648.1 crore.
The Core has reached out to Reliance and Nykaa for their response, and will update this report if and when they respond.
Why Fenty Chose Reliance
Fenty’s move looks more like an internal one, according to Suumit Kapoor, a brand growth consultant.
LVMH owns 50% of Fenty Beauty through its beauty incubator Kendo Brands, a stake it has held since co-founding the brand with Rihanna in 2017. LVMH also owns Sephora globally, and Sephora in India is run by Reliance.
“When Fenty enters a new market through Sephora, LVMH is effectively distributing its own equity stake through its own global retail infrastructure,” Kapoor said. For a brand with that kind of ownership overlap, he added, the choice of partner is “close to an internal routing decision” and not a genuine trade-off.
That ownership overlap is itself now in a pickle.
LVMH has been exploring a sale of its 50% Fenty stake since October 2025, working with investment bank Evercore, according to Reuters. As of June 2026, American rapper and businessman, Jay-Z’s investment firm MarcyPen Capital Partners was reported to be among the parties in talks to buy it.
No sale has closed yet, so the Reliance-Sephora-LVMH alignment still holds for now, but it isn’t guaranteed to outlast the current ownership structure.
Fenty’s India journey backs this up. The brand’s first India listing wasn’t through Reliance at all.
It ran on Nykaa’s Cross Border Store, a low-commitment digital shelf that was discontinued before Fenty’s August 2025 relaunch, an exclusive omnichannel deal with Reliance spanning more than 50 stores across 16 cities on day one.
Kapoor doesn’t think of the switch as a deliberate strategic upgrade.
“The Cross Border Store listing may simply have underperformed on its own terms, without much marketing support behind it,” he said, adding that there is no clear evidence that Reliance stole the brand away.
Devangshu Dutta, founder of the research firm Third Eyesight, said celebrity backing only buys a brand little room.
“When a company or an investor buys into an early-stage celebrity brand, they are acquiring instant brand equity which acts as a top-of-the-funnel magnet and potentially lower CAC,” he said. “However, the ‘fame premium’ runs out if product and service execution isn’t compelling enough to drive repeat business and customer retention.”
Ownership decides the biggest deals before “competition” even enters the picture, Fenty landed at Reliance’s Sephora because LVMH owns half of each, though that alignment is shakier than it looks, with Jay-Z’s MarcyPen Capital Partners now the leading bidder for LVMH’s Fenty stake.
Beyond ownership, it’s a straight trade-off.
For brands chasing scale, Reliance’s tens of thousands of stores will get you reach. If brands want to chase community, Rare Beauty did by picking Nykaa specifically to tap its affluent, digitally engaged beauty shoppers and build loyalty. Some brands skip the fight altogether, like Birkenstock, which walked into India solo.
The Distribution Gap
Where Reliance doesn’t need an ownership story to make its case is scale. Reliance Retail closed the quarter ended June 2026 with 20,169 stores across 78.4 million square feet, 396 million registered customers, and 568 million transactions in that single quarter, up 46% year on year, according to the company’s Q1 FY27 earnings release. JioMart alone served 5,500 pincodes through its rapid delivery network in the same period.
Nykaa, by comparison, operated 324 physical stores across 105 cities as of its FY26 numbers, with a cumulative customer base of around 42 million, per its own disclosures and Business Standard’s reporting on the company’s results.
“That gap generally buys a brand not just bigger numbers, but reaches into places where a beauty specialist has no reason to be,” Kapoor said. For brands thinking beyond beauty into wellness, gifting, or lifestyle crossovers, he said that scale “is not a nice-to-have. It is the entire argument for choosing Reliance over a beauty-only platform.”
Satish Meena, founder of Datum Intelligence, a research firm, made a similar point on Reliance’s pull with brands weighing an India entry.
“With the kind of strength they have, they can always give a better deal,” he said, referring to Reliance’s ability to commit capital and guarantee scale that a newer entrant typically cannot promise on its own. He pointed to Reliance’s existing retail relationships, including Marks & Spencer, as part of the track record that makes brands comfortable signing with the group.
Experts say over the past two to three years, Nykaa has been the more prolific launch platform for major international beauty brands, while Reliance has had greater strength in international luxury and fashion.
According to experts, Nykaa reported more than 70 luxury-brand additions over the last three years, including names such as NARS, Prada Beauty, La Prairie, Chanel Beauty, Armani Beauty and Maison Margiela. Reliance, meanwhile, has built a luxury portfolio spanning Valentino, Balenciaga, Bottega Veneta, Tiffany & Co., Burberry and others, and most recently brought SKIMS to India. Reliance’s public disclosures do not provide a comparable 2–3-year count of new international brand entries.
Reliance is arguably a major gateway for international luxury/fashion, but calling it the default gateway for international brands overall is too broad.
Where Nykaa Still Wins
Reliance’s advantage on raw numbers doesn’t fully explain why Nykaa keeps landing brands too.
Nykaa built its beauty audience before it built its stores, using tutorials and curated storytelling to create what Kapoor called “a beauty-literate customer base that arrives already primed to trust the platform’s recommendations.”
That specialism is what pulled in Rare Beauty. Nykaa’s June 2026 launch made the brand available through its website, app, and 30 stores nationwide, and came from a company reporting its highest quarterly profit since listing at the time, per its own disclosures.
In a company statement announcing the launch, Anchit Nayar, Nykaa Beauty’s executive director and CEO, said the brand fit a “new generation of highly informed and globally engaged consumers seeking elevated brand experiences.” Rare Beauty’s chief executive, Scott Friedman, said in the same announcement that India was “a very important market” for the brand, citing Nykaa’s beauty community in the country as the reason to partner with it specifically.
Nykaa has run a similar playbook before. Chanel strengthened its India fragrance and beauty presence on Nykaa in 2025, Obagi Medical entered India through the platform specifically for its clinically driven skincare positioning, and Estee Lauder’s incubation arm has run its India beauty programme, Beauty and You, with Nykaa as lead partner every year since 2022.
Dutta pointed to Kay Beauty, Nykaa’s own celebrity line with actor Katrina Kaif, as an example of why platform fit matters as much as platform size. Contrasting it with 82°E, actor Deepika Padukone’s skincare brand on Tira, he said Kay Beauty had two advantages: it was priced for a much larger audience, and it had “Nykaa’s active participation across channels for merchandising and visibility.”
Not The Only Door
Reliance’s pull is real, but it isn’t the only route into India.
Reliance benefits from international-brand partnerships through retail economics, distribution and, in some cases, ownership or joint-venture economics. The potential conflict emerges because Reliance can simultaneously act as a brand’s market-entry partner and control substantial retail and digital routes to consumers. Public filings, however, do not establish that Reliance uses this position to disadvantage partner brands or competing retailers.
Meena pointed to Birkenstock, which entered by opening its own stores rather than partnering with either platform. Birkenstock and similar labels operate as single-brand retail; they can use India’s foreign direct investment rules to set up shop directly, bypassing the need for a local partner altogether.
“If the brands think that they have enough pull in the market and they can bring customers, they are opening these stores without any partnership,” Meena said. He added that most global brands take the partner route anyway because India, for many of them, is still a small share of global sales, and testing the market with an established partner for a few years is lower risk than building from scratch.
Kapoor flagged one risk worth watching no matter which partner a brand picks. Exclusive deals give a retailer more control. But Tira has also started building its own private-label products, including a colour cosmetics line, and sells them in the same stores as the global brands it distributes.
“A retailer can be a brand’s distribution partner and, on an adjacent shelf, its competitor, at the same time,” he said, a tension he noted that Nykaa’s marketplace model, without a comparable private label push against premium brands, does not carry in the same way.
For brands already tied to Reliance through ownership, like Fenty, there isn’t much of a decision to make. For everyone else, Nykaa signing Rare Beauty and Reliance signing SKIMS within weeks of each other shows this fight for celebrity founders in India is far from over.
(Published in The Core)
admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
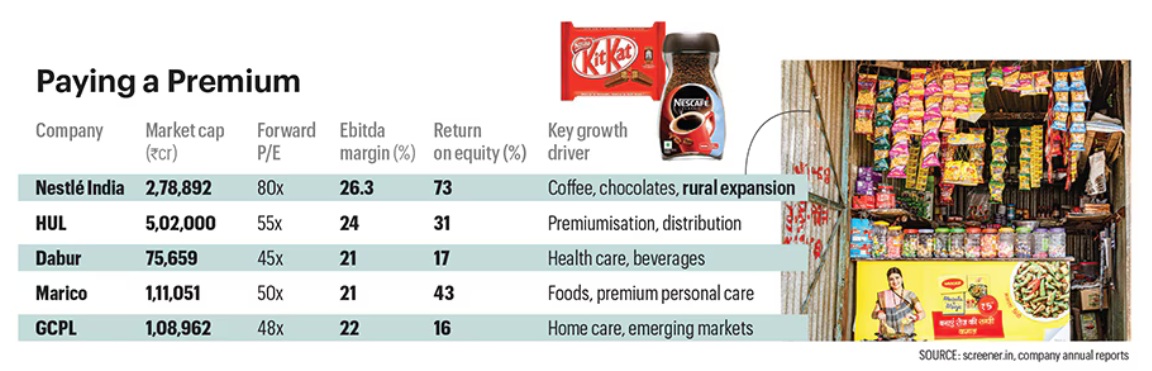
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
admin
June 12, 2026
Christina Moniz, Financial Express/Brand Wagon
12 June 2026
Legacy luggage brand VIP Industries is shedding some of its old baggage. The company, which manufactures Skybags and Aristocrat along with its flagship VIP range, has gone beyond cringey makeovers solely to attract Gen Z, and has embarked on a transformation journey that leverages its legacy to purvey a fresh range of offerings.
The company is modernising its digital presence and supply chain to catch up with competitors.
Managing director Atul Jain admits that the company has been a bit slow on the e-commerce front. It is reinventing its online store, while also making its products available across other e-commerce channels. “Quick commerce is becoming an important channel since there are several use occasions and segments within the luggage market. For instance, consumers often make last-minute purchases for a weekend trip via quick commerce. School bags and backpacks for kids, also great gifting options, are seeing good demand on these platforms,” he says
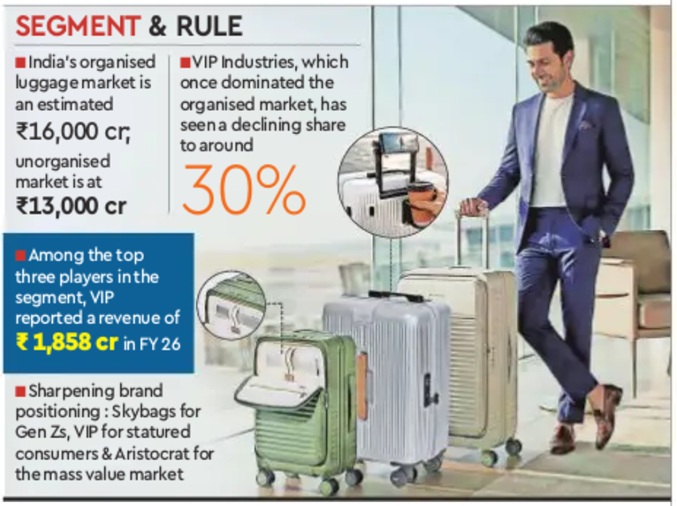
The company, which once dominated the ₹16,000 crore organised luggage market in India, saw a bit of a shakeup last year when the Piramal family sold 32% of its stake to a private equity firm. But it continues to be among the top three players in the category with a 29-30% market share. “Luggage plays the role of a traveller’s companion. We are creating designs to fit that role,” says Jain. “For example, our new VIP suitcases have a coffee cup holder and our cabin trolley bag has an easy access compartment for devices like laptops and iPads.”
The transformation goes beyond the product. VIP’s 350 exclusive physical retail touchpoints in the country are being revamped to offer a new customer experience.
Unpacking opportunities
Overits 55 years, VIP has grown from a briefcase brand into Asia’s largest luggage maker, housing labels like Skybags, Aristocrat, and Carlton (premium segment). While VIP is a premium offering targeted at business and travellers, its Aristocrat brand operates in the mass market and the budget-friendly Alfa targets consumers who typically shop in the unbranded segment. Aristocrat and Alfa together contributed upwards of 40% to the company’s revenue in FY25, followed by Skybags (28%) and VIP (20%).
Like many legacy brands, the VIP Industries’ faces the challenge to ia, stay relevant among Gen Z buyers as a plethora of digital-first brands swamp the market. “VIP has lost ground on relevance and desirability to a generation for whom luggage, like sneakers, is an expression of identity. To them, VIP feels like their parents’ brand,” says Nisha Sampath, managing partner, Bright Angles Consulting. D2C players in the category operate in the business of “lifestyle accessories” and not for “luggage” per se, she points out.
With a design-forward approach, incorporating features like compression systems, silent wheels and charging ports, these new-age brands have embedded themselves in travel “culture”, while also being Instagram worthy, say experts.
Jain says Skybags is VIP’s Gen Z focussed brand, which has over 8,20,000 Instagram followers. “We are sharpening our positioning for Skybags in our design, advertising and marketing outreach, especially on social platforms. The brand has a clear differentiation with youthful colours and prints to attract younger consumers,” he adds.
While D2C players have seen notable growth in recent years, they don’t have the kind of trust and brand equity that VIP has cultivated across its brands, nor do they have the scale or revenue that legacy brands have, he says.
Experts believe there is a significant growth opportunity for legacy players given that the unbranded market still accounts for ₹13,000-14,000 crore. The important lever for legacy brands is to clearly demonstrate value beyond price. “The unorganised market competes heavily on affordability, so organised players need to communicate durability, warranty, after-sales service, and consistent quality – areas where they have a strong inherent advantage over unorganised alternatives,” says Praveen Govindu, partner at Deloitte India. He adds that these brands should also invest in advertising and communicate this value to the end consumer.
Not only are the needs different among different consumer groups, competitive pressures are also diverse. “VIP can segment the market more cleanly with its portfolio of brands if it maintains absolute distinction to ensure clear consumer targeting across not just product attributes and pricing, but also communication and channels,” says Devangshu Dutta, CEO, Third Eyesight.
(Published in Financial Express)
admin
May 27, 2026
Kartikey Kashyap, Financial Express
27 May 2026
Three campaigns took home the Grand Prix awards from Goafest this year: Kansai Nerolac Paints”The Barefoot Journey” by Tribes Commu-nication in the Media category; Mountain Dew’s “Darescore” by Leo in Digital & Technology; and Center fruit (Perfetti Van Melle India)” Kaisi Jeebh Laplapayee”” by Perfetti’s in-house team in the Best Use of Voice/Technology category.
All three were exceptionally creative and scored high on likeability and novelty. There was another common element that tied the three together: How they used creativity to solve real brand problems.
Take PepsiCo’s Mountain Dew Darescore campaign. Nepal’s tourism economy relies heavily on mountaineering, but over 90% of global tourist revenue flows into Mount Everest. As a result, there is overcrowding on Everest, starving the country’s other formidable peaks of income and attention.
Enter Mountain Dew. In partner-ships with the Nepal Tourism Board and the Discovery Channel, the brand built the world’s first algorithmic mountain grading system. Leo aggregated decades of expedition records, terrain complexity maps, seasonal weather hazards, rescue failure rates, and first-hand Sherpa wisdom. They funneled these metrics into an engine and assigned a quantifiable “Dare Score” to individual peaks. This data visually demonstrated that height does not equal danger, giving climbers an scale to gauge terrain toughness.
The genius of the campaign was its consumer utility. Mountain Dew printed smart QR codes on millions of its beverage bottles. When a user scanned the bottle, it unlocked an immersive digital hub, where users could simulate climbs, map out route plans, read real-time weather conditions, and submit expedition inquiries. The campaign took Mountain Dew’s slogan, “Darr Ke Aage Jeet Hai” and algorithmically decoded it for real-world application.
The result: It Swept Goafest 2026 and collected medals across vastly different categories including Integrated, Brand Experience, Social Content, and Video Craft, besides the Grand Prix. “Darescore is a powerful example of how brands are moving from storytelling to measurable participation. For decades, adventure culture celebrated only the final summit. This campaign changed the lens, it quantified courage itself,” says Prabhakar Mundkur, director, advertising & media, Percept. “What made this Grand Prix-worthy was the fusion of technology, gaming logic, data and brand philosophy into one seamless experience.”
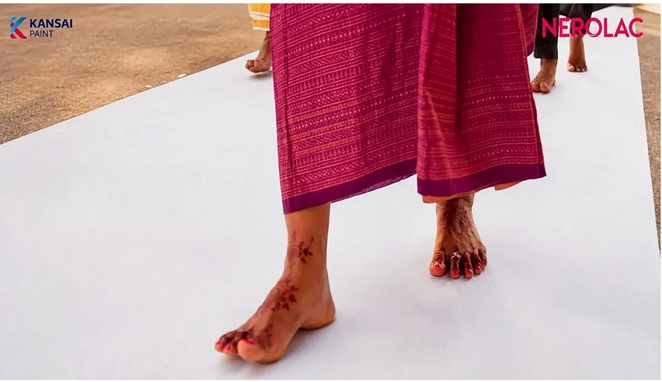
If the Darescore campaign embedded data into storytelling, Nerolac chose to stay away from the beaten path. Its “Barefoot Journey” was a hyper-local activation designed by Tribes Communication for Nerolac Perma NoHeat, an acrylic-based, heat-reflective exterior coating. The campaign focused entirely on real-world product performance.
Every summer devotees visit various religious sites and walk barefoot along sweltering walkways or wait in queues on hot concrete floors.
Along with local authorities, the teams coated thewalkways of several high-footfall temples across south-ern India with Nerolac Perma NoHeat paint. The paint reduced the surface temperature of the pathways by up to 15°C offering relief to devotees.
This campaign won the jury over with its simplicity. According to Devangshu Dutta, founder & CEO, Third Eyesight, “Though the campaign might target a small audience, it made an impact by shifting the frame,” Dutta points out. “The campaign turned advertising into lived experience,” Mundkur says. “People didn’t just hear a claim, they felt it. This is media not as interruption, but as empathy.”
For its part, Centre fruit brought back its hoary “Kaisi Jeebh Lapla-payee” tagline using generative AI. Teaming up with WPP, BharatGPT.ai and Google Cloud, Perfetti created voice-based GenAl interactions in local dialects that turned feature phones smart. “What made the experience special was that it felt less like advertising and more like a conversation,” says Gunjan Khetan, director marketing, Perfetti Van Melle. Al was an enabler of accessibility and a tool to build cultural relevance, Khetan adds. “The brilliance lay in how it con-verted a simple sensory reaction -the uncontrollable craving triggered by taste – into a scalable interactive idea. It was playful, memorable and unmistakably Indian. More importantly, it proved that consistency in -brand codes, when combined with fresh execution, can become a formidable creative asset,” Mundkur says.
There you have it. Winning creative awards is validating, but solving the client’s problems through that creativity remains the bellringer.
(Published in Financial Express)
admin
May 9, 2026
Writankar Mukherjee, Economic Times
Kolkata, 9 May 2026
India’s top retail chains including Reliance Retail, DMart, Trent, Titan Company, Jubilant FoodWorks, and V-Mart Retail opened the highest number of stores in three years in FY26, seeking to capitalise on a demand recovery and a clean-up of unviable outlets added during the post-Covid revenge-spending period.
Entry into smaller towns and cities where many consumers continue to prefer shopping at physical stores over online is also influencing the expansion plans.
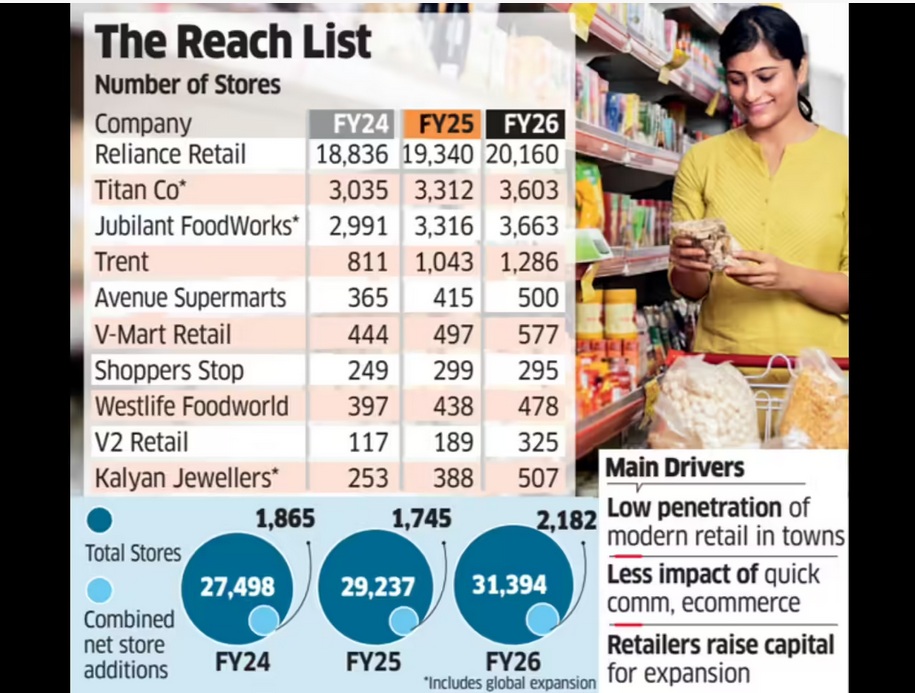
An ET study of the 10 largest listed retailers showed they added 25% more stores in the last fiscal year compared to FY25. Additions are on a net basis after accounting for loss-making outlet closures.
Collectively, the retailers added 2,182 stores in FY26, equivalent to six new stores a day on a net basis. In comparison, they added 1,745 stores in FY25 and 1,865 in FY24.
Retailers attributed the store expansion spree to improving consumer sentiment, helped further by cuts in income tax and goods and services tax (GST) rates last fiscal, along with low penetration of organised retail in smaller towns and cities. Together, the ten retailers had 31,394 stores operational as of March 2026.
Expansion Set to Continue
V-Mart Retail chief executive officer Lalit Agarwal said the ongoing shift from unorganised to organised retail is fuelling this expansion as several companies are meeting their sales growth expectations. “Many retailers have also raised capital, which they are deploying to grow topline,” he said, adding that the “growth phase will continue in the current fiscal as well.”
Companies surveyed by ET also include Shoppers Stop, Westlife Foodworld, V2 Retail and Kalyan Jewellers. Together, the ten retailers had 31,394 stores operational as of March 2026. Their combined store count grew 7% in FY26, ahead of a 6% expansion in the year before.
Reliance Retail alone added 820 net stores last fiscal, rebounding from a slowdown in FY25 when it shut several unviable outlets that were opened immediately post Covid, impacting overall industry growth rates. The country’s largest retailer had added 504 net stores in FY25, 796 in FY24, and 2,844 in FY23.
Similarly, Tata-owned Titan added 532 stores in FY23, but expansion moderated to 280-290 stores annually in FY25 and FY26.
India’s retail industry saw hyper expansion in late FY22 and FY23 as retailers sought to tap a boom in post-pandemic revenge shopping.
“Retail expansion now is more organic and measured as compared to the post Covid phase when there was a huge backlog of demand and over expansion,” said Devangshu Dutta, founder and CEO at Third Eyesight, a consultancy in consumer space.
(Published in Economic Times)
