admin
November 3, 2026
Pritha Pahari, The Core
3 November 2026
India’s packaged food and soap makers are running out of easy choices. Input costs have continued to rise since late February, when the Middle East conflict began disrupting supply chains and pushing up crude-linked costs.
A visible price hike, however, risks sending shoppers to a rival. To offset this, companies have reduced package sizes. However, scope for how much these packs can be reduced is limited, especially for products already sold at low price points. Take the example of a Rs 10 pack of Parle-G biscuits.
At this price, there is little room to reduce the quantity further without risking consumer dissatisfaction. Cutting the pack size could make the product less attractive, while increasing the price may discourage price-sensitive buyers.
India’s FMCG giants have squeezed pack sizes about as far as they can go. With input costs still climbing and shoppers watching every rupee, the choice between eating the cost and raising prices is coming, likely right after Diwali.
The Hikes Are In
Britannia, Hindustan Unilever (HUL), Dabur and Godrej Consumer had already raised prices by around 2-5% in the June quarter, and were weighing more for the September quarter. FMCG companies have continued to raise prices to offset higher input costs.
FMCG companies have continued to raise prices to offset higher input costs.
Tata Consumer Products increased tea prices by 8-10% between the June and September quarters, while it raised the price of its Rs 30 salt pack to Rs 32 in May and again to Rs 34 in October.
Hindustan Unilever also took price increases of around 7.5% during the September quarter, according to media reports.
Godrej Consumer Products said it would continue calibrated price increases, particularly in soaps and liquid detergents, to manage cost pressures.
Dabur has also confirmed taking pricing actions in its October business update, while Britannia had indicated a further 1.5-2% increase, largely through smaller packs. However, the latter two companies’ September-quarter results were still awaited.
Experts said that lower-income households face greater pressure because everyday essentials take up a larger share of their budgets. Affordable products such as biscuits, noodles, soaps, detergents and cooking oils are particularly sensitive to price changes.
According to experts, some manufacturers are weighing selective price increases after Diwali, possibly from December.
Shoppers haven’t walked away yet
So far, demand is holding up. Nestlé India’s sales rose 20.5 per cent to Rs 6,782 crore in the September quarter, with double-digit volume growth.
At HUL, June-quarter underlying sales growth of 10 per cent came equally from volume and price.
The market is still nervous.
Nestlé India shares closed 7.7% lower on results day after management flagged rising input costs, especially packaging, edible oils and farm commodities.
Business Standard quoted chairman Manish Tiwary as saying, “Rising inflation, particularly food inflation, is a reality.”
India’s FMCG volume growth remains mixed, although several companies continue to report resilient demand. Tata Consumer Products’ India branded volume growth eased from 16% in Q4 FY26 to 13% in Q1 FY27 and 11% in Q2 FY27.
Marico reported that India volume growth reached near double digits in Q2 FY27, following 11% in Q1.
Dabur India recorded 5% underlying volume growth in Q1 FY27, while its October update indicated double-digit revenue growth for Q2 but did not disclose a confirmed volume figure.
Overall, demand remains resilient, but revenue growth should not be confused with volume growth, particularly as companies raise prices to offset higher input costs.
Why Smaller Packs?
Satish Meena, founder of research firm Datum Intelligence, said that companies try to absorb costs first. “They can do it for one quarter, they can do it for two quarters, but at a certain point they have to pass it on to the customer,” he said. He expects much of that to happen after the festive season.
Discounts are not an option either, since margins are thin. That leaves pack sizes. “Instead of 150 grams, we are doing 120 grams, keeping the price the same,” Meena said, describing the move.
A visible price rise carries a risk of its own.
“Your positioning in the shop will change, and customers will also perceive you as an expensive product and look for other brands,” he said. Once a rival takes the shelf space, it is hard to win it back.
Devangshu Dutta, founder of research firm Third Eyesight, says price points are hard to move. “Price points are often anchored either in the consumer’s mind or by competitive benchmark pricing, making them difficult to change,” he said.
He also said the practice now carries a reputation risk. “The shrinkflation phenomenon isn’t new, but social media has given it viral visibility, which can potentially damage brand reputation.”
Pricing Pecking Order
Meena said companies will follow a set order. First they improve buying and supply chains, then trim ad spending. Next they raise prices on premium products, where buyers are more willing to pay. Raising prices across all products comes last, so they don’t lose share.
Dutta says companies are “caught in a vice” because input costs are rising while core shoppers are cautious about spending. Companies have “no option but to cut brand-level advertising and also review overheads deeply.”
Indian FMCG companies are facing rising input costs across several product categories.
In October 2026, plastic packaging costs were reported to have increased by 30–40%, putting pressure on snack makers and household-product manufacturers.
Palm oil prices rose 21% year-on-year in September, while sunflower oil increased 14%, soybean oil 9% and mustard oil 8%.
Sugar prices climbed 18% year-on-year, adding pressure on confectionery and packaged-food producers.
Tea prices rose 10% over the same period. Coffee and cocoa also recorded increases, with Arabica coffee up 19% quarter-on-quarter and cocoa rising 48%. These increases affect biscuits, noodles, chocolates, soaps, shampoos and detergents differently.
Now What?
The next test is HUL’s September-quarter results, due after its board meets on 28 October. Meena does not expect much to change in the next one to two quarters.
He says the pressure is not seasonal. “It’s because of the war happening in the Middle East… it’s a much longer issue for them,” and he points to RBI data showing some impact on demand.
Input-cost pressures could persist into early 2027.
S&P Global’s September outlook projected elevated manufacturing costs through 2027, while October data showed plastic packaging costs 30–40% higher and key polymer prices more than 50% above pre-conflict levels.
Although prices may ease if supply routes improve, these figures suggest FMCG companies could face continued cost pressure over the next two quarters.
Dutta said only a few brands will come through easily. “Few brands or products are able to build longer-term loyalty consistently and whose value to the consumer is stickier than the resistance to price movement.”
For everyone else, the room to raise prices or shrink packs is running out.
(Published in The Core)
admin
June 30, 2026
Vaeshnavi Kasthuril, MINT
30 June 2026, Mumbai
Advent International-backed Modenik Lifestyle Pvt. Ltd is doubling down on its portfolio of legacy innerwear brands, planning to scale each label into a sizeable business rather than rely on a single flagship brand.
“Each of the brands must grow big enough to be called a company of its own,” Shekhar Tewari, chief executive and executive director, told Mint.
The company has four brands: premium women’s innerwear label Enamor, value brand Slimz, mass-premium men’s label Dixcy Scott, and premium men’s innerwear brand Levi’s. “These brands are very strong in their respective segments. They complement each other rather than compete,” Tewari said.
Levi’s Innerwear is priced between ₹250 and ₹550, Dixcy Scott and Slimz between ₹100 and ₹350, while Enamor’s products start at ₹500 and go beyond ₹2,500.
The strategy comes as India’s innerwear market, particularly women’s lingerie, has become one of the country’s most fiercely contested apparel categories, with established retailers and digital-first brands vying for market share.
Modenik’s focus on innerwear deepened after private equity firm Advent brought Enamor and Dixcy together under Modenik Lifestyle, following its acquisition of Enamor from Gokaldas Exports in 2019.
Both brands had expanded into adjacent categories such as athleisure, loungewear, sleepwear and outerwear, but struggled to keep pace with rising competition from fashion retailers and digital-first brands. The company has since exited much of its outerwear portfolio, taking a revenue hit.
“We took a conscious hit on the top line because we wanted to become a focused innerwear company,” Tewari said. “If you’re trying to be everything to everyone, you end up not being known for anything. We wanted consumers to think of us first when they think of innerwear.”
Revenue has remained largely flat at around ₹1,200 crore over the past three years, though losses have narrowed sharply. FY25 revenue stood at ₹1,224 crore, while net loss halved to ₹24.8 crore from ₹50.8 crore a year earlier.
Modenik aims to outpace the industry’s single-digit growth by increasing branded penetration in women’s innerwear, expanding its premium portfolio and adding exclusive store network, expected to cross 100 outlets in the near term.
The company sees significant headroom in women’s innerwear, where it estimates the market at more than ₹20,000 crore, but organised brands account for only ₹3,000-4,000 crore. It expects formalization, premiumization and product innovation to accelerate brand adoption.
According to Devangshu Dutta, chief executive of retail consultancy Third Eyesight, the market’s increasing fragmentation makes a multi-brand strategy more effective.
“You can’t have one brand stretching across multiple segments. The product has to be different, pricing strategies are different, the messaging and the distribution channel mix also varies depending on the consumer segment you’re trying to target,” he said.
According to industry estimates, India’s innerwear market is valued at over ₹90,000 crore (about $10.9 billion) and is expected to grow at a 6-7% compound annual growth rate (CAGR) over the next decade.
Advantages and avenues
Tewari believes Modenik has structural advantages over many digital-first rivals. Unlike online-first brands that typically outsource manufacturing, the company controls product development and manufacturing while leveraging decades-old relationships with distributors, department stores, exclusive brand outlets and multi-brand retailers.
“Those capabilities have been built over decades. They cannot be replicated overnight,” he said.
The company is also expanding across channels. Enamor is available through 6,000-7,000 multi-brand outlets, nearly 80 exclusive stores, department stores, including Shoppers Stop, Lifestyle, Central and Pantaloons, besides online marketplaces and quick commerce platforms. E-commerce contributes over 30% of Enamor’s revenue.
Although digital commerce is growing rapidly, Tewari believes physical retail will continue to play a critical role in the category.
“Innerwear is a category that requires understanding of fit, size and functionality. Consumers still want to touch, feel and try products before making the switch from unbranded to branded,” he said.
Rather than pursuing acquisitions, the company plans to unlock growth from its existing portfolio.
The strategy comes as competition in India’s innerwear market is intensifying. Page Industries dominates through Jockey, while Reliance Retail, which houses brands such as Clovia, Marks & Spencer and Hunkemöller, acquired digital-first lingerie platform Zivame, and added premium lingerie brand amanté. Aditya Birla Fashion and Retail has expanded Van Heusen Innerwear, while Trent has strengthened its innerwear offering through its private label brands at Westside and Zudio. New-age brands such as Shyaway, Bummer and Nykd by Nykaa have also stepped up investments in their products.
(Published in MINT)
admin
June 22, 2026
Sharleen D’souza & Shivani Shinde, Business Standard
Mumbai, 21 June 2026
Online beauty marketplaces Reliance Retail Ventures’ Tira and Nykaa have a common mantra: growing in-house brands. Successful brand acquisitions and margin growth seem to fuel the push.
“With private labels, margins are better. It also helps both companies plug the gap in the market which other brands are not present in,” Devangshu Dutta, chief executive officer (CEO) of Third Eyesight, told Business Standard. Within in-house brands, products need some investment in research and development (R&D), he explained.
Harish Bijoor, brand and business strategy consultant at Harish Bijoor Consults, said that margins are better for platforms with in-house brands.“Typically most companies are getting insular. The idea is to own brands and own the profits from those brands. When you are a marketplace, you put in effort for other brands, this strategy helps marketplaces lock in on profits instead of losing out to other brands, which sell on the platform,” he said.
At the 49th annual general meeting of Reliance Industries (RIL) on Friday, Isha Ambani, executive director of Reliance Retail Ventures Ltd, and non-executive director of RIL, had laid out plans for Tira. “We will scale our own brands to consumers across India and beyond, ensuring Indian beauty prod-
ucts stand proudly alongside the world’s leading global giants.”
Its in-house brands include Puraveda, Pahadi Local, haircare brand Anomaly, which was recently acquired from actress Priyanka Chopra Jonas, and skincare and make-up brand Akind, which it co-created with Mira Rajput Kapoor. Its portfolio also includes Nails Our Way and Dream Immerse Play.
Ambani’s statement had come a day after Nykaa’s management had also hinted at expanding its in-house brands on its investor day on Thursday. The platform, operated by FSN E-Commerce Ventures, outlined an ambitious road map to become an over $5 billion beauty and lifestyle business.
The growth of Nykaa’s “House of Brands” is expected to be significant. The management aims to be the largest house of brands business in India by financial year 2030 (FY30). Management has guided toward a net sale value (NSV) compounded annual growth rate (CAGR) of 30 per cent over FY26-30, taking the NSV from Rs. 1,700 crore in FY26 to Rs. 5,000 crore by FY30.
The “House of Nykaa” GMV grew over 65 per cent in FY26, with an improvement in profitability. In a report on the company’s focus on in-house brands business, Motilal Oswal said, “House of Brands is expected to grow faster than the core marketplace business and become a meaningfully larger contributor to group revenues and profits by FY30. We believe profit contribution is expected to increase disproportionately, given the higher gross margins, stronger pricing control, and lower dependence on third-party brands.”
Nykaa’s platform creates a structural incubation advantage, it said. “Fashion today serves about 300,000 styles across categories, while customer discovery increasingly happens through content, personalisation, and creator-led commerce. This allows the company to identify emerging brands and categories early, before allocating capital behind them,” the report added.
As of the fourth quarter of financial year (FY26), “House of Nykaa” had 12 brands across Beauty and Fashion categories at various growth stages, and two successful acquisitions of Dot & Key and Earth Rhythm. Dot & Key has grown 13 times over the last three years, while Kay Beauty has grown three times over this period, said the company. During the Q4FY26 results, the company had said that the strong performance of “House of Nykaa” had impacted margins positively. P Ganesh, chief financial officer, FSN E-Commerce while explaining the margin growth said, “…with gross margin improving by 132 basis points
in FY26, led by strong performance of House of Nykaa and improved service income across businesses.”
For FY26, “House of Nykaa” delivered a strong Rs. 3,176 crore of GMV. “That’s an about 50 per cent year-on-year increase. Served more than 17 million consumers and expanded distribution beyond online as well to 150,000 GT doors. As a reminder, this unit includes brands across beauty and fashion, seven brands in Beauty and in Fashion five brands, with an increased focus on one in particular, which is Nykd,” said Adwaita Nayar, executive director, cofounder and chief executive officer, “House of Nykaa Brands”, during the fourth quarter results.
(Published in Business Standard)
admin
June 12, 2026
Christina Moniz, Financial Express/Brand Wagon
12 June 2026
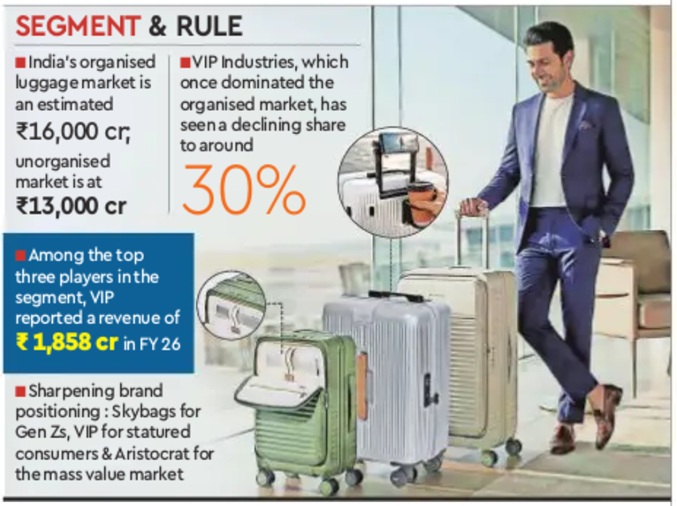
Legacy luggage brand VIP Industries is shedding some of its old baggage. The company, which manufactures Skybags and Aristocrat along with its flagship VIP range, has gone beyond cringey makeovers solely to attract Gen Z, and has embarked on a transformation journey that leverages its legacy to purvey a fresh range of offerings.
The company is modernising its digital presence and supply chain to catch up with competitors.
Managing director Atul Jain admits that the company has been a bit slow on the e-commerce front. It is reinventing its online store, while also making its products available across other e-commerce channels. “Quick commerce is becoming an important channel since there are several use occasions and segments within the luggage market. For instance, consumers often make last-minute purchases for a weekend trip via quick commerce. School bags and backpacks for kids, also great gifting options, are seeing good demand on these platforms,” he says
The company, which once dominated the ₹16,000 crore organised luggage market in India, saw a bit of a shakeup last year when the Piramal family sold 32% of its stake to a private equity firm. But it continues to be among the top three players in the category with a 29-30% market share. “Luggage plays the role of a traveller’s companion. We are creating designs to fit that role,” says Jain. “For example, our new VIP suitcases have a coffee cup holder and our cabin trolley bag has an easy access compartment for devices like laptops and iPads.”
The transformation goes beyond the product. VIP’s 350 exclusive physical retail touchpoints in the country are being revamped to offer a new customer experience.
Unpacking opportunities
Overits 55 years, VIP has grown from a briefcase brand into Asia’s largest luggage maker, housing labels like Skybags, Aristocrat, and Carlton (premium segment). While VIP is a premium offering targeted at business and travellers, its Aristocrat brand operates in the mass market and the budget-friendly Alfa targets consumers who typically shop in the unbranded segment. Aristocrat and Alfa together contributed upwards of 40% to the company’s revenue in FY25, followed by Skybags (28%) and VIP (20%).
Like many legacy brands, the VIP Industries’ faces the challenge to ia, stay relevant among Gen Z buyers as a plethora of digital-first brands swamp the market. “VIP has lost ground on relevance and desirability to a generation for whom luggage, like sneakers, is an expression of identity. To them, VIP feels like their parents’ brand,” says Nisha Sampath, managing partner, Bright Angles Consulting. D2C players in the category operate in the business of “lifestyle accessories” and not for “luggage” per se, she points out.
With a design-forward approach, incorporating features like compression systems, silent wheels and charging ports, these new-age brands have embedded themselves in travel “culture”, while also being Instagram worthy, say experts.
Jain says Skybags is VIP’s Gen Z focussed brand, which has over 8,20,000 Instagram followers. “We are sharpening our positioning for Skybags in our design, advertising and marketing outreach, especially on social platforms. The brand has a clear differentiation with youthful colours and prints to attract younger consumers,” he adds.
While D2C players have seen notable growth in recent years, they don’t have the kind of trust and brand equity that VIP has cultivated across its brands, nor do they have the scale or revenue that legacy brands have, he says.
Experts believe there is a significant growth opportunity for legacy players given that the unbranded market still accounts for ₹13,000-14,000 crore. The important lever for legacy brands is to clearly demonstrate value beyond price. “The unorganised market competes heavily on affordability, so organised players need to communicate durability, warranty, after-sales service, and consistent quality – areas where they have a strong inherent advantage over unorganised alternatives,” says Praveen Govindu, partner at Deloitte India. He adds that these brands should also invest in advertising and communicate this value to the end consumer.
Not only are the needs different among different consumer groups, competitive pressures are also diverse. “VIP can segment the market more cleanly with its portfolio of brands if it maintains absolute distinction to ensure clear consumer targeting across not just product attributes and pricing, but also communication and channels,” says Devangshu Dutta, CEO, Third Eyesight.
(Published in Financial Express)
admin
June 8, 2026
Arushi Jain, The Times of India
8 June 2026
Their faces have launched many campaigns and brought crores to the film industry. But can they sell a moisturiser as successfully? India’s beauty market is the hottest growth story globally, estimated to reach $40 billion from $23 billion (2026) and eyeing the fourth-largest spot by 2030 (currently at number seven).
Last month, Estée Lauder announced the buyout of Forest Essentials, one of India’s oldest, Ayurveda-based brands. In 2025, Hindustan Unilever acquired five-year-old skin and hair care brand, Minimalist. A 2025 McKinsey & Company x Business of Fashion survey found that 78% of global beauty executives see India as the most promising growth market. Even celebrities have shown up with chequebooks, but fans are no longer buying at face value.
While Hailey Bieber’s Rhode built a cult following through what she calls an “outside of the box” strategy, Deepika Padukone’s 82°E reported a 30% revenue dip in FY25. Nykaa is in talks to acquire a stake in the brand.
India’s consumer has evolved faster than the brands serving them. They are reading labels now, not just recognising famous faces on packaging. Star power, it turns out, only gets you so far.
Fame gets you in the door. Formulation keeps you there
If a celebrity is the invitation to the party, formulation is what keeps the guest at the after-party. Despite India’s celebrity beauty segment crossing an estimated `5,000 crore in GMV in FY24, scale has not translated into customer retention. The initial spike, familiar to anyone who has tracked a celebrity launch, gives way to an uncomfortable question: what brings a customer back?
“Celebrity isn’t necessarily a sustainable brand asset,” says Devangshu Dutta, CEO of retail consultancy Third Eyesight. “While celebrities can act as interest-creators and trial-generators, repeat purchases are built on functional reasons, not imagery alone.”
Founders echo the same reality from the ground. “Honestly, people come back for what works,” says Aashka Goradia Goble, co-founder of RENÉE Cosmetics. “If a product performs well, feels easy to use, is priced right, and becomes part of someone’s everyday routine, they’ll keep reaching for it.”
Price, too, remains a decisive filter. Sunny Leone, founder of StarStruck, says, “In India, price is the main component.” The journey from first purchase to loyalty is driven by habit, and habit, in beauty, is built on results.
Positioning over popularity
The gap between a viral campaign and a repeat purchase is wider than most A-listers realise. Brand guru Harish Bijoor locates the problem in what he calls the “spinal cord” of a brand: a single, clear positioning that holds the entire business together.
Rihanna’s Fenty is inseparable from its commitment to shade inclusivity. Kylie Jenner’s Kylie Cosmetics was built around one obsession: lips. “It is extremely important to understand what you want to be and focus on just one thing and not on everything,” Bijoor says. That clarity is precisely where most Indian celebrity beauty brands are still finding their footing.
The old playbook: launch a brand online, wrap it in the language of “clean” or “natural,” and wait for a global conglomerate to come calling has run its course. Today, strategic buyers and consumers alike want a brand that can stand on its own. The question is no longer whether a celebrity can generate awareness. It is whether the brand they have built can survive them.
What the labels that last have in common
The brands breaking through are doing so quietly and methodically. In a category where fame can spark interest but not always guarantee repeat purchase, Katrina Kaif’s Kay Beauty, launched with Nykaa in 2019, has emerged as one of celebrity beauty’s more consistent success stories.
The main reason is less about star power and more about strategy. “If you contrast Kay Beauty and 82°E (Deepika Padukone’s brand), Kay Beauty has two distinct advantages,” says Dutta. “Firstly, being priced for a much larger audience, and secondly, having the active participation of Nykaa across channels in terms of merchandising and visibility push for the brand.”
Nykaa is candid about what made the difference. “When we co-created Kay Beauty with Katrina, shade ranges and formulations designed for Indian skin tones and climate were severely limited,” a spokesperson shares, adding that the celebrity association “amplified the brand rather than substituted for it.” The strategy appears to have paid off: Kay Beauty is now a ₹500 crore-plus annualised GMV brand, with new launches contributing 21% of revenue as of Q3 FY26.
Why Indian skin demands more than a famous name
For Indian celebrity brands, the challenge is not just performance; it is perception. “Domestically, we see the mentality for buyers is to look at international brands first based on trust, and then try domestic brands based on lower price value,” says Leone.
Indian consumers are also highly specific in what they expect. According to market research firm Mintel, shoppers are increasingly drawn to formulations that are clinically tested and grounded in both science and local familiarity. Products must perform in Mumbai’s humidity and Delhi’s pollution and suit the full spectrum of Indian skin tones.
“Indian consumers love products that do more than one job, last long in our weather, and actually match Indian skin tones,” says Goradia. They are cautious spenders, she adds, but willing to invest when they see real quality and innovation.
Nykaa says this ingredient awareness is now visible across the country, not just metros. “Consumers are reading about niacinamide and retinol, they know what they want from a sunscreen, and are making considered purchase decisions. Brands need to earn their place on merit in every market,” says the spokesperson.
“A brand that addresses these needs well and remains within the customer’s budget succeeds,” says Dutta.
Gen Z will drive 50% of India’s beauty consumption by 2030
By 2030, Gen Z will drive 50% of India’s beauty and personal care consumption, a third of all sales will happen online, and per capita income is forecast to rise 138% in real terms by 2040, according to Euromonitor. Nykaa founder and CEO Falguni Nayar told Bloomberg that comparing India’s beauty routines to South Korea’s famed 14-step regimens is premature, “It is still day zero for beauty consumption in India.”
The global conglomerates have done the math. Estée Lauder, L’Oréal, and Puig are all moving deeper into India, betting on a consumer who is younger, more digitally fluent, and more ingredient-literate than any previous generation. The brands they are acquiring, Forest Essentials, Minimalist, Kama Ayurveda, share a common thread: They are built on something that exists independently of a famous face. “This is an industry that is very crowded and takes a lot of time to grow,” says Leone. “Western brands focus on global distribution and profit and loss. Not just turnover at a loss.” The celebrities who will build something lasting are the ones who understand that the launch is the easiest part. As Bijoor puts it: “Celebrity beauty is not skin deep at all. It is a deep brand science.”
(Published in The Times of India)
