admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
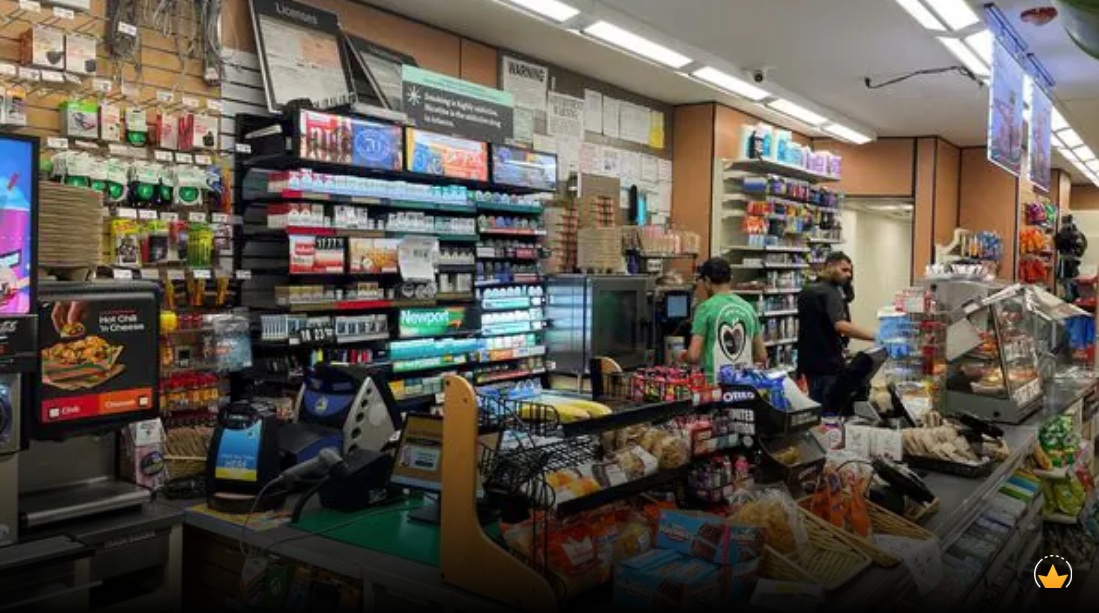
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
October 5, 2026
Sagar Malviya, Economic Times
5 October 2026
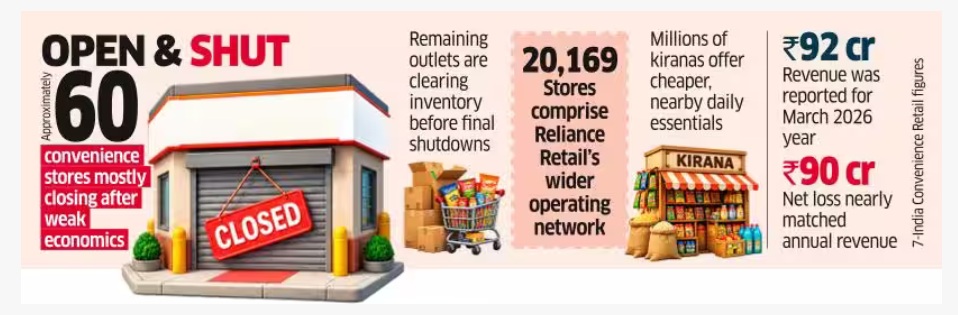
Reliance Retail and 7-Eleven are ending their five-year franchisee deal in India, closing most of the nearly 60 convenience stores they operated under the partnership, after struggling to make the format profitable, people familiar with the matter said.
A handful of outlets are clearing the inventory before shutting, they said. 7-Eleven may look for another Indian partner to keep a foothold in the market, although no decision has been made, the people said.
The exit highlights an unusual squeeze that convenience stores are facing in India, with millions of small kirana stores that have long served consumers’ immediate needs on one side and quick-commerce companies that are bringing the same snacks, groceries and daily essentials to doorsteps within minutes on the other.
Reliance and 7-Eleven did not respond to ET’s queries.
The partnership, struck in 2021, was intended to bring the world’s largest convenience-store chain to India through Reliance’s retail network. But the business struggled to achieve the scale needed to offset the relatively high costs of running branded stores.
The 7-India Convenience Retail venture reported revenue of about ₹92 crore ($10.6 million) and a net loss of nearly ₹90 crore in the year ended March 2026, according to its financial statements.
“Reliance wants to reach consumers across every channel, but sustainability ultimately matters. Convenience stores have faced increasing pressure from quick commerce since the pandemic, with both formats offering similar assortments and serving the same immediate-needs occasions,” said Devangshu Dutta, founder and CEO of Third Eyesight, a consumer-sector consultancy.
“Kiranas operate with far lower overheads and different margin expectations than corporate-run convenience stores. Reliance’s exit could therefore signal a broader rethink of the format, particularly in markets where quick commerce has become a strong alternative.”
Globally convenience stores have become powerful retail businesses in several markets despite the expansion of supermarkets and hypermarkets. 7-Eleven in Japan, Taiwan, Thailand and Singapore; Lawson in Japan and Oxxo in Mexico are among the largest retailers in their respective markets.
7-Eleven’s Japanese parent, Seven & i Holdings, operates more than 85,000 stores globally, making it one of the world’s largest retail networks. Yet the company has been restructuring its overseas operations and closing stores in North America as consumer behaviour and store economics change.
In India, however, organised convenience retail has struggled to replicate the success seen in other Asian and emerging markets. EasyDay, More and Spencer’s have either shut stores or shrank their smaller-format networks over the years, underscoring the difficulty of building profitable neighbourhood stores at scale.
Packaged consumer goods companies continue to derive roughly three-fourths of their sales from small neighbourhood stores, underlining the strength of the traditional distribution network. Quick commerce platforms are, meanwhile, expanding rapidly.
That makes it difficult for organised convenience stores to charge a premium or generate sufficient sales density to cover higher rents, staffing, inventory and logistics costs.
Convenience retail works best when operators achieve high store density and productivity, supported by strong supply chains and differentiated offerings such as fresh food and private labels.
Reliance initially expanded the 7-Eleven network in Mumbai and other markets, but the footprint remained small compared with the company’s wider retail operations.
(Published in Economic Times)
admin
May 9, 2026
Writankar Mukherjee, Economic Times
Kolkata, 9 May 2026
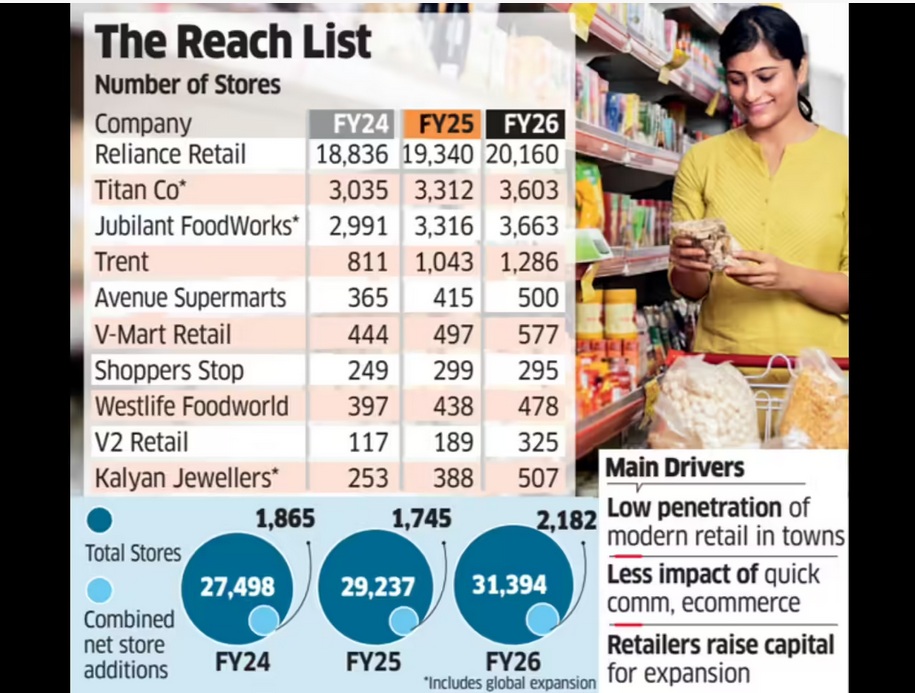
India’s top retail chains including Reliance Retail, DMart, Trent, Titan Company, Jubilant FoodWorks, and V-Mart Retail opened the highest number of stores in three years in FY26, seeking to capitalise on a demand recovery and a clean-up of unviable outlets added during the post-Covid revenge-spending period.
Entry into smaller towns and cities where many consumers continue to prefer shopping at physical stores over online is also influencing the expansion plans.
An ET study of the 10 largest listed retailers showed they added 25% more stores in the last fiscal year compared to FY25. Additions are on a net basis after accounting for loss-making outlet closures.
Collectively, the retailers added 2,182 stores in FY26, equivalent to six new stores a day on a net basis. In comparison, they added 1,745 stores in FY25 and 1,865 in FY24.
Retailers attributed the store expansion spree to improving consumer sentiment, helped further by cuts in income tax and goods and services tax (GST) rates last fiscal, along with low penetration of organised retail in smaller towns and cities. Together, the ten retailers had 31,394 stores operational as of March 2026.
Expansion Set to Continue
V-Mart Retail chief executive officer Lalit Agarwal said the ongoing shift from unorganised to organised retail is fuelling this expansion as several companies are meeting their sales growth expectations. “Many retailers have also raised capital, which they are deploying to grow topline,” he said, adding that the “growth phase will continue in the current fiscal as well.”
Companies surveyed by ET also include Shoppers Stop, Westlife Foodworld, V2 Retail and Kalyan Jewellers. Together, the ten retailers had 31,394 stores operational as of March 2026. Their combined store count grew 7% in FY26, ahead of a 6% expansion in the year before.
Reliance Retail alone added 820 net stores last fiscal, rebounding from a slowdown in FY25 when it shut several unviable outlets that were opened immediately post Covid, impacting overall industry growth rates. The country’s largest retailer had added 504 net stores in FY25, 796 in FY24, and 2,844 in FY23.
Similarly, Tata-owned Titan added 532 stores in FY23, but expansion moderated to 280-290 stores annually in FY25 and FY26.
India’s retail industry saw hyper expansion in late FY22 and FY23 as retailers sought to tap a boom in post-pandemic revenge shopping.
“Retail expansion now is more organic and measured as compared to the post Covid phase when there was a huge backlog of demand and over expansion,” said Devangshu Dutta, founder and CEO at Third Eyesight, a consultancy in consumer space.
(Published in Economic Times)
admin
July 28, 2024

Writankar Mukherjee, Economic Times
Kolkata, 28 July 2024
Top retail chains such as Reliance Retail, Shoppers Stop and Spencer’s Retail are facing a prolonged slowdown in consumption, pushing them to exit unprofitable markets, raise debt and control costs.
India’s largest retailer Reliance Retail shuttered 249 stores in the three months ended June. The company is also going slow on expansion, opening 331 new stores in the quarter compared to 470-800 stores opened every quarter in FY22, FY23 and FY24. The closures mean the retail business of Reliance Industries made 82 net new store additions last quarter–the lowest in 15 quarters.
Spencer’s Retail has decided to completely exit North and South India markets by closing 49 stores in the National Capital Region (NCR), Andhra Pradesh and Telangana. The step will erase Rs 490 crore of annual revenue, but the company is hopeful it will improve profitability.
Shoppers Stop chief executive officer Kavindra Mishra told investors last week that it may have to defer a few store openings this fiscal due to regulatory and other issues. The company will also borrow Rs 100 crore for expansion with demand remaining soft.
Meanwhile, V-Mart Retail has closed 22 stores in the first six months of 2024, as per its latest investor presentation.
“Pruning underperforming locations is a natural reaction during times of demand stress,” said Devangshu Dutta, CEO of retail sector consulting firm Third Eyesight.
Pure Economics
“Demand forecasting can never be perfect due to a lag between demand assessment and supply. Retailers now try to do away with underperforming stores at the bottom of the pile quickly. Earlier there were prestige issues in shutting down stores, but now it’s acceptable industry practice and pure economics,” said Third Eyesight’s Dutta.
Analysts say most retailers expanded rapidly after the pandemic, banking on pent-up demand and revenge shopping at the time. With demand turning sluggish, the industry is now being forced to take various steps to sustain operations. At Reliance Retail, net profit rose by a modest 4.6% from a year earlier in the June quarter to Rs 2,549 crore while revenue grew 6.6% to Rs 66,260 crore. It was the slowest pace of revenue growth and came after a 9.8% increase in Q4FY24. Net profit and revenue from operations fell sequentially in the June quarter.
Spencer’s Retail CEO Anuj Singh told analysts on Thursday the 49 stores it is closing make up nearly 22% of revenue, but also Rs 56 crore of losses at the regional Ebitda level in North and South India. “They were a drag on the balance sheet. We will now focus on Uttar Pradesh and the East where there is a sizable consumption opportunity with a 250 million population,” he added.
Singh said the store rationalisation exercise and about 35% headcount reduction at corporate offices will reduce overheads from 8% operating cost to 6.3% of total sales. “We now expect to achieve Ebitda breakeven by March 2025 which will give us the option to raise capital,” he said.
Mishra at Shoppers Stop said demand remained subdued last quarter due to fewer wedding dates, long election season with polling dates on weekend, heatwaves, and high level of cumulative inflation. All these factors combined hit growth and volume recovery, except in value fashion and beauty.
More stores shut than opened
In fact, the sustained demand slowdown saw chains like Pantaloons, Spencer’s Retail and Nature’s Basket close more stores than they opened last fiscal. Retailers like V-Mart Retail, W, Aurelia and Titan Eye+ had a higher rate of store closures than openings in the March quarter.
(Published in Economic Times)
Devangshu Dutta
January 10, 2017
In this piece I’ll just focus on one aspect of technology – artificial intelligence or AI – that is likely to shape many aspects of the retail business and the consumer’s experience over the coming years.
To be able to see the scope of its potential all-pervasive impact we need to go beyond our expectations of humanoid robots. We also need to understand that artificial intelligence works on a cycle of several mutually supportive elements that enable learning and adaptation. The terms “big data” and “analytics” have been bandied about a lot, but have had limited impact so far in the retail business because it usually only touches the first two, at most three, of the necessary elements.
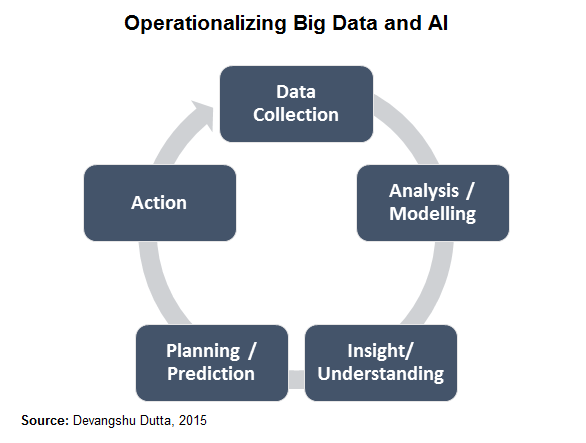
“Big data” models still depend on individuals in the business taking decisions and acting based on what is recommended or suggested by the analytics outputs, and these tend to be weak links which break the learning-adaptation chain. Of course, each of these elements can also have AI built in, for refinement over time.
Certainly retailers with a digital (web or mobile) presence are in a better position to use and benefit from AI, but that is no excuse for others to “roll over and die”. I’ll list just a few aspects of the business already being impacted and others that are likely to be in the future.
On the consumer-side, AI can deliver a far higher degree of personalisation of the experience than has been feasible in the last few decades. While I’ve described different aspects, now see them as layers one built on the other, and imagine the shopping experience you might have as a consumer. If the scenario seems as if it might be from a sci-fi movie, just give it a few years. After all, moving staircases and remote viewing were also fantasy once.
On the business end it potentially offers both flexibility and efficiency, rather than one at the cost of the other. But we’ll have to tackle that area in a separate piece.
(Also published in the Business Standard.)
