admin
August 28, 2026
Sowmya Ramasubramanian, MINT
28 Aug 2026
Quick commerce is here to stay, according to FirstCry managing director and chief executive Supam Maheshwari. He added, however, that the economics will increasingly favour large retailers with established stores, logistics networks, and private labels over niche platforms building from scratch.
“There will be fatalities in this space,” Maheshwari told Mint, referring to specialty quick-commerce platforms. He explained that these platforms face a difficult path to profitability due to high logistics, inventory, working capital, and customer-acquisition costs.
FirstCry (Brainbees Solutions Limited) has developed its own logistics arm, RocketBees, along with FirstCry Qwik, which provides two-to-three-hour delivery in select pin codes. RocketBees, launched in mid-2025, now operates across 72 cities and improved its delivery turnaround by around 20% between launch and the first quarter of FY27. Qwik, launched in December 2025, has expanded to 12 cities and delivered about 125,000 shipments in June, Maheshwari said.
Rather than tracking Qwik’s expansion by city count, FirstCry is targeting about 10% of its online orders through the service over the next few quarters. The model will leverage the company’s existing store network where possible, with dedicated dark stores in select catchments.
Qwik will operate alongside FirstCry’s standard e-commerce offering, providing faster delivery for a narrower local assortment, while the broader catalogue remains available through same-day and next-day delivery.
This strategy comes as FirstCry tries to regain operating leverage after a period of margin pressure. Consolidated revenue rose 13% year-on-year to ₹2,106 crore in Q1FY27, even as adjusted Ebitda declined to ₹89.3 crore from ₹92.7 crore a year earlier, squeezing the margin to 4.2% from 5%. While India multi-channel revenue grew 17.7%, its adjusted Ebitda margin shrank to 5.7% from 8.6%.
Maheshwari’s remarks also coincide with sustained investor interest in vertical quick-commerce platforms focused on the mother-and-baby and kids categories. Kids-focused OZi secured $6.2 million from RTP Global in March, while babycare platform Peeko raised over $7 million in a round led by Chiratae Ventures earlier this month.
Quick commerce edge
Maheshwari said FirstCry isn’t aiming to replicate the standard quick-commerce model. Niche platforms, he noted, lack the scale needed to absorb logistics and supply-chain costs, leaving them more exposed to inventory and working-capital demands. Their reliance on third-party brands also restricts their ability to protect margins.
“If you put all of this together, it just becomes unsustainable in my view,” Maheshwari said, arguing that niche-category quick commerce could take many years and hundreds of millions of dollars to become profitable. In contrast, FirstCry generates over half its gross merchandise value (GMV) from in-house brands and operates a national logistics network, creating what he described as a different economic equation.
FirstCry has more than two million stock keeping units (SKUs), and Qwik can offer products beyond emergency purchases such as diapers or formula, including partywear, ethnicwear, strollers, walkers and tricycles, he added.
Maheshwari also said he does not expect delivery speed to cannibalize FirstCry’s core business. “A lot of mothers are planned shoppers. When they are buying fashion, nursery products or other categories, they do research, they look at the brand and quality. They don’t necessarily need the product in 10 minutes.”
That distinction is reflected in FirstCry’s approach to physical stores. The company has spent the past two quarters changing its offline assortment strategy, moving from an e-commerce-led approach focused on product width to a retail model focused more heavily on depth. Maheshwari said this allows the company to secure better costs, offer better prices, and improve footfall and conversion.
FirstCry plans to add around 90-100 stores in FY27, and Maheshwari expects an even larger number in FY28. The expansion is not being driven by Qwik, he said, although stores in cities where Qwik operates can also be used to fulfill quick-commerce orders.
The offline push is aimed at increasing wallet share in markets where FirstCry doesn’t have stores yet. Maheshwari said 36% of GMV from the top 50 cities in FY26 came from customers who transacted both online and offline.
“Assortment depth, availability, trust, and sustained price-value have been, and will remain, the true differentiation levers. For categories such as medicines and baby products, credibility and compliance outweigh saved minutes, apart from urgent purchases,” Devangshu Dutta, founder of consultancy Third Eyesight, told Mint last month.
Private labels and margins
Home brands accounted for more than 58% of GMV in FY26, up from 37% in FY20, and Maheshwari expects that trajectory to continue. FirstCry’s portfolio includes Babyhug, BabyOasis, CuteWalk and Pine Kids, alongside third-party brands.
“The trust is first with FirstCry as a retail platform and then with the home brands. That is why our curation is so important. We are offering a superior experience through the home brands we have been building,” Maheshwari said. Rather than viewing this curation simply as a lever for higher gross margins, he considers it a key competitive advantage spanning FirstCry’s physical stores, e-commerce platform, and quick-commerce service.
FirstCry’s consolidated gross margin fell to 36.5% in Q1FY27 from 38.5% a year earlier, while India multi-channel adjusted Ebitda margin fell to 5.7%. Maheshwari attributed the pressure primarily to aggressive competition in diapers and higher raw-material costs, which affected FirstCry’s manufacturing business.
He expects the raw-material impact to be fully reflected in pricing by Q3, while diapers could take another two to four quarters to normalise. “This is only a 15% category for us,” he said, noting that the remaining 85% of the portfolio—fashion, baby gear, nursery and toys—continues to perform strongly. He said he expects margins to recover through FY27 and that the company’s longer-term margin trajectory remains upward.
Brainbees Solutions stock was trading around ₹186 at 1 pm on Friday, down around 1.35% on the day. The stock is down more than 72% since it was listed in August 2024.
(Published in MINT)
admin
June 12, 2026
Aanya Thakur & Writankar Mukherjee, Economic Times
12 June 2026, Mumbai/Kolkata
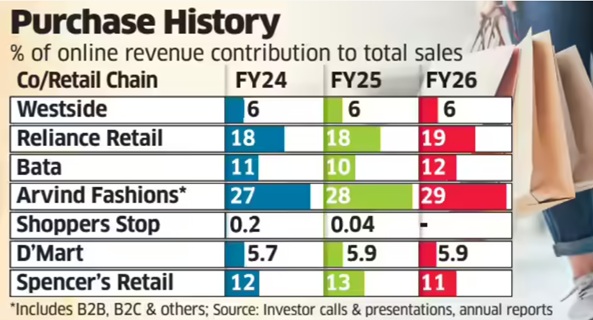
India’s leading retail chains have seen the share of e-commerce in total sales either remain flat or edge up by a sluggish 1-2 percentage points over the past four-five years despite a sustained push towards omnichannel retailing.
An ET analysis of eight major retailers-market leader Reliance Retail, Shoppers Stop, Westside, Arvind Fashions, DMart, Spencer’s Retail, Pantaloons and Bata-showed that the contribution of e-commerce to overall revenue has seen minuscule improvement since 2021-22 even as online sales continue to increase in absolute terms. By contrast, the Covid-19 pandemic spurred explosive growth, with the share of digital sales in total revenue surging three to four times in 2020-21 and 2021-22.
Industry executives attribute the slowdown partly to lower investment levels compared with pure-play digital firms such as Amazon, Flipkart, Swiggy and Blinkit-parent Eternal. Besides, retailers have consistently maintained that they will not pursue online growth at the expense of profitability, keeping prices largely aligned across online and offline channels.
The ET study found Tata-owned Westside’s online contribution stood at 7% in 2021-22 and thereafter remained around 6% till 2025-26. Reliance Retail’s online share ranged between 17% and 19% during the period, while Bata’s remained at 10-12%.
For DMart, e-commerce accounted for 5-6% of sales, while Shoppers Stop’s online arm, Shoppers Stop.Com (India) Ltd, contributed less than 1% to the consolidated revenue between 2021-22 and 2024-25. The company has not disclosed 2025-26 online sales figures yet.
“The DNA of these retailers is rooted in the physical world-infrastructure, processes and systems are not inherently designed for e-commerce, which requires a different operating model,” said Devangshu Dutta, chief executive of consultancy Third Eyesight.
“Most retailers calling themselves omnichannel are effectively multi-channel. Online retail is capital-intensive and hyper-competitive. Given the significant scope for physical store expansion, especially in tier-2 and tier-3 cities, retailers are reluctant to invest aggressively online,” he said.
Even so, Avenue Supermarts, which runs DMart, invested Rs 150 crore in online grocery platform DMart Ready this week, following a Rs 174-crore infusion a year earlier.
By comparison, Eternal infused Rs 2,600 crore into Blinkit in 2025 and another Rs 450 crore in March this year. Similarly, Swiggy approved a Rs 1,000-crore investment in supply-chain subsidiary Scootsy last year as both companies expanded their dark-store networks.
The chief executive of Aditya Birla-owned departmental chain Pantaloons, Sangeeta Tanwani, recently told analysts that online sales accounted for just 3-4% of the business. She said the company had earlier refrained from investing in the channel because profitability remained elusive.
“But over the last year, we called out omnichannel as one of our priorities… The reason why we had paused that business was because we wanted to make sure that we can get the unit economics right and make this business profitable… With all the shifts we have made this year, we feel confident of scaling up this business,” Tanwani said.
Reliance Retail, meanwhile, reported lower earnings before interest, taxes, depreciation and amortisation (EBITDA) margin growth in both the January-March quarter and entire 2025-26 as investments in quick commerce weighed on profitability. Chief financial officer Dinesh Taluja recently told analysts that margins depend on the pace at which online and business-to-business segments grow relative to the core offline business.
“If we slow down online growth, margins will improve. It is a mix as far as the online business continues to grow faster,” he had said.
An industry executive said the online contribution may go up modestly in this financial year due to high investment in scaling up dark stores for quick commerce.
Queries emailed to Reliance Retail did not elicit a response till press time. The company had in December last year appointed former Flipkart executive Jeyandran Venugopal as its new chief executive for the retail business.
(Published in Economic Times)
admin
January 6, 2026
Saumyangi Yadav, Entrepreneur India
Jan 6, 2026
After years of rapid growth and a sharp reset, India’s direct-to-consumer (D2C) sector is expected to settle into a more balanced phase. The period of easy funding, aggressive customer acquisition and scale-at-all-costs expansion is clearly over, experts suggest. Now, what lies ahead in 2026 is a shift towards steadier growth driven by better execution, stronger retention and clearer brand positioning.
According to Bain and Flipkart, India’s e-retail market is projected to reach $170–190 billion in GMV by 2030, driven by a growing online shopper base and evolving commerce models. As adoption deepens across Tier-2 and Tier-3 cities, high-frequency categories such as grocery and lifestyle are expected to drive a larger share of growth, making repeat purchase and habit formation critical for D2C brands.
Against this backdrop, 2026 is shaping up as the year when D2C brands are judged less on ambition and more on outcomes.
A Post-Hype Phase of D2C
Industry observers say the D2C ecosystem has clearly moved beyond its hype-driven phase. Devangshu Dutta, Founder and Chief Executive of retail consultancy Third Eyesight, describes the current moment as one of structural correction rather than contraction.
“India’s D2C ecosystem is in a post-hype phase where growth may be slower but structurally healthier,” Dutta says, adding, “Earlier growth cycles prioritised visibility and sales at the expense of profitability and consistency. Now, success is being measured by repeat rates, contribution margins and the ability to fund growth internally.”
Tighter funding is also driving this shift. With D2C investments slowing and overall capital remaining cautious, brands are now being pushed to show predictability rather than promise. Tracxn data shows Indian D2C startups raised USD 757 million in 2024, significantly lower than previous years, while overall PE-VC investments in India remained flat at USD 33 billion in 2025, according to Venture Intelligence.
As a result, Dutta notes that many D2C companies are rationalising portfolios, tightening inventory cycles and optimising supply chains. Marketing strategies, too, are evolving, with greater emphasis on retention, community-building and owned channels instead of discount-led growth.
Uniqueness Will Define Winners
If capital discipline is one defining force, speed is another. Harish Bijoor, business and brand strategy expert, argues that D2C’s next phase will be shaped by how brands respond to a faster, more fragmented commerce environment.
“The e-commerce revolution led to a more refined orientation of D2C, and that has now given way to a q-commerce revolution that is even faster,” Bijoor says, adding, “The D2C revolution is going to be leveraged by speed. A whole host of players will invest time, energy and innovation into this.”
In Bijoor’s view, traditional e-commerce is now the slowest layer in a spectrum where quick commerce is the fastest, and D2C sits in between. In such a landscape, competing purely on price is no longer sustainable. He believes differentiation will increasingly come from uniqueness and premium positioning rather than ubiquity.
“When you know that you get a particular great-tasting biryani at just one place with no branches, you will go to that place. That uniqueness is what will distinguish D2C commerce in the future,” he says.
Bijoor adds that many D2C brands have been trapped in price wars under the guise of differentiation. He also argued that brands that premiumise and resist excessive omnichannel dilution are more likely to build desirability and long-term value.
Consumers Move Beyond Metros
Structural shifts in demand are reshaping how and where D2C brands grow. India now has one of the world’s largest and most diverse online consumer bases, with growth increasingly driven by Tier-2, Tier-3 and smaller towns rather than metros alone. Internet adoption continues to deepen across rural and semi-urban India, expanding the addressable market well beyond early digital buyers.
This widening base is changing the nature of growth. Consumers are becoming more deliberate in how they spend, weighing value, quality and trust more carefully than before.
As Devangshu Dutta notes, Indian consumers have always been discerning, but rising living costs and economic uncertainty have made them even more thoughtful, pushing brands to earn repeat demand rather than rely on impulse or discount-led purchases.
“Value is not just about discounts,” he says. “It’s a balance of price, performance and trust. For D2C brands, repeat consumption has to be earned through consistent quality, transparent pricing and dependable service.”
High-frequency categories such as grocery, lifestyle and general merchandise are expected to drive much of this expansion. Bain estimates these segments will account for two out of every three e-retail dollars by 2030, reinforcing the importance of habit formation and retention-led models.
Quick Commerce Expands Discovery, Not Profitability
Quick commerce has emerged as a powerful but complex growth lever for D2C brands. The format now accounts for a significant share of India’s e-grocery demand and has scaled into a multi-billion-dollar market, becoming a key discovery channel for food and everyday consumption brands.
However, expansion beyond metros remains challenging. RedSeer data shows non-metro markets contribute just over 20 per cent of quick commerce GMV, even as platforms scale to over 150 cities, with breakeven economics in smaller towns requiring significantly higher throughput.
Praveen Govindu, partner at Deloitte India, cautions that while quick commerce has helped many D2C brands gain discovery, particularly in food and beverage, it is not a sustainable growth engine on its own.
“From a customer acquisition standpoint, quick commerce is not fundamentally different from traditional e-commerce,” Govindu says, adding, “It is an expensive channel, and competition will only intensify. Over the long term, brands cannot rely on burning capital there.”
Omnichannel Enters Its Toughest Phase Yet
As digital acquisition costs rise, India’s ad market is projected to grow nearly 8 per cent in 2025 to Rs 1.37 lakh crore, with digital accounting for almost half of the spends, brands are being pushed to diversify distribution. Yet omnichannel presence alone is no longer enough.
“Many brands talk about omnichannel, personalisation and seamless journeys, but in practice these efforts are still disjointed. In 2026, the focus will shift from intent to execution,” Govindu says.
RedSeer projects India’s retail market to cross USD 2 trillion by 2030, with nearly 90 per cent of consumption still happening offline. For D2C brands, this makes offline expansion unavoidable, but success will depend on consistent execution across pricing, inventory, service and communication.
Consumers, Govindu notes, do not consciously differentiate between online, offline or social platforms. “They simply want a consistent experience,” he says. “Even small inconsistencies can erode trust.”
AI-Led Discovery and Experience
Perhaps the most transformative force shaping 2026 will be the evolution of buying journeys themselves. Govindu sees the rise of AI-led and agentic commerce as a major inflection point.
“Conversational platforms and AI-driven assistants will increasingly influence discovery, purchase, fulfilment and post-sales experiences. What earlier happened across multiple touchpoints is now beginning to happen in one place,” he says.
This convergence amplifies the importance of content-led discovery, owned data and deep consumer understanding. Brands that can unify storytelling, commerce and service into a coherent narrative are more likely to build loyalty in an environment where switching costs are low and alternatives are abundant.
Whether growth comes through D2C websites, marketplaces, quick commerce or offline stores, experts agree that the real differentiator will be a brand’s ability to build durable consumer relationships. As investors shift focus from short-term metrics to long-term value creation like retention, margins and brand strength, the next phase of India’s D2C story is less about rapid expansion and more about refinement.
(Published in Entrepreneur India)
Saumyangi is a Senior Correspondent at Entrepreneur India with over three years of experience in journalism. She has reported on education, social, and civic issues, and currently covers the D2C and consumer brand space.
admin
December 15, 2025
By Saumyangi Yadav, Entrepreneur India
Dec 15, 2025
India’s D2C ecosystem has grown rapidly over the past five years, but scale remains elusive. While thousands of brands have launched and many have crossed early revenue milestones, only a small fraction manage to break past INR 100 crore in annual revenue. According to a new report by DSG Consumer Partners, based on a survey of over 100 Indian D2C founders and operators, the problem is not demand or product-market fit, it is how brands attempt to scale.
The report shows that around 60–65 per cent of Indian D2C brands remain stuck in the INR 1–50 crore revenue band, with very few reaching the INR 100 crore mark. This stage marks the point where early traction exists, but growth begins to strain unit economics, teams, and operating systems.
Insights from over 100 D2C founders reveal that India’s fastest-growing brands win on fundamentals rather than speed alone. Clear product-market fit, disciplined data tracking, strong unit economics, creative velocity, and an early focus on retention consistently separate scalable brands from those that plateau. Founders also admit that performance marketing mistakes, pricing missteps, and weak creative systems slow growth far more than budget constraints. In a booming D2C landscape, capability gaps in operations, brand-building, and supply-chain depth are widening the divide between breakout brands and those stuck in the performance plateau.
Industry observers argue that this is where many brands mistake rapid online growth for sustainable scale.
As Devangshu Dutta, Founder & CEO, Third Eyesight, explains, “Scaling up online can be very rapid, but is also capital-hungry in terms of CAC. Given the intense competition, the lack of customer stickiness and the power of platforms, there is a constant churn of marketing spend which is a huge bleed for growing brands.”
CAC Inflation is The Real Constraint
One of the clearest findings from the playbook is that acquisition efficiency, rising CAC and unstable ROAS, is the single biggest blocker to growth, cited by more founders than funding or category expansion. Moreover, over 70 per cent of brands rely on Meta as their primary acquisition channel, increasing vulnerability to auction pressure and platform-driven volatility.
Dutta links this directly to the limits of a digital-only mindset. “Limited offline expansion can trap brands in narrow urban digital markets, blocking broader scale,” he said.
This over-reliance on online performance marketing often leads to growth that looks strong on dashboards but weak on cash flow.
Highlighting their report, Pooja Shirali, Vice President, DSG Consumer Partners, said, “Across over 90 consumer brands we’ve partnered with at DSGCP, one truth is clear: brands that master Meta’s ecosystem don’t just grow, they change their entire trajectory through strategic clarity and disciplined execution. The real drivers of scale have less to do with viral moments, and everything to do with the long-term fundamentals that make milestones like the first INR 100 crore predictable, not accidental.”
Why Omnichannel is Unavoidable
The report suggests that brands that scale sustainably are those that reduce overdependence on paid digital acquisition and expand their distribution footprint. However, offline expansion brings its own complexity.
Dutta stresses that omnichannel is not an optional add-on, but a strategic shift. “D2C brands must adopt an omnichannel approach, blending online with offline retail for sustainable and scalable reach. Clearly the channels work very differently and management teams have to be prepared and capitalised for the long haul to tackle acquiring customers with channel-appropriate strategies,” he adds.
This aligns with the DSGCP report’s broader insight that scale breaks down when brands fail to adapt operating models as they grow.

Even within digital channels, performance weakens over time. The playbook finds that 62 per cent of founders report creative fatigue, where repeated creatives fail to sustain ROAS despite higher spends. At the same time, 55 per cent admit to under-investing in CRM and retention, with most brands reporting repeat purchase rates of just 10–30 per cent.
Both the data and expert opinion point to a common theme: brands that cross the INR 100 crore mark are structurally different. They obsess over unit economics, processes, and capital efficiency rather than topline growth alone.
As Dutta puts it, “Scalable brands that cross the growth hump have leadership obsessed with unit economics and omnichannel execution rather than chasing vanity metrics. Cash always was and is king, especially at early stages of growth.”
He adds that execution strength matters as much as strategy. “They are able to grow and steer teams that build and replicate processes fast rather than spending time, effort and money reinventing all the time, and do so without constant CXO intervention.”
As competition intensifies and capital becomes more selective, the next generation of INR 100 crore D2C brands is likely to be defined not by speed, but by the ability to compound cash flows, institutionalise processes, and scale distribution beyond digital platforms.
Saumyangi is a Senior Correspondent at Entrepreneur India with over three years of experience in journalism. She has reported on education, social, and civic issues, and currently covers the D2C and consumer brand space.
(Published in Entrepreneur India)
admin
November 13, 2025

Saumyangi Yadav,Entrepreneur
Nov 13, 2025
India’s consumer landscape is undergoing a decisive shift in 2025. While D2C brands that once thrived on digital-only distribution are now aggressively building an offline footprint, legacy FMCG majors are simultaneously acquiring digital-first brands to strengthen their portfolios and tap into new consumer behaviours.
As analysts suggest, these trends signal a maturing phase for India’s D2C ecosystem, one that blends physical retail and strategic consolidation.
Offline Push Accelerates
According to a recent CBRE report, ‘India’s D2C Revolution: The New Retail Order’, D2C brands leased nearly 5.95 lakh sq ft of retail space between January and June 2025, accounting for 18 per cent of all retail leasing during this period, up sharply from 8 per cent in the first half of 2024. Fashion and apparel dominated the expansion, contributing close to 60 per cent of D2C leasing, followed by homeware and furnishings and jewellery at about 12 per cent each, while health and personal care brands accounted for roughly six per cent. The shift is equally visible in the choice of retail formats: 46 per cent of D2C leasing went to high streets, 40 per cent to malls, and the remaining to standalone stores, reflecting the category’s growing focus on visibility, trial and experiential discovery.
Experts suggest that it represents a strategic pivot to blended engagement.
As Devangshu Dutta, CEO of Third Eyesight, notes, “India’s D2C surge is powered by digital-first consumers, tremendous improvement in seamless logistics, and low-cost market entry, supported subsequently by substantial amounts of investor capital chasing those startups that stand out from the competition. Yet, lasting success demands a more holistic view: the divide between online and offline is a business construct, not a consumer reality. The larger chunk of retail sales still happens through physical channels and, for brands that want to be mainstream, an omnichannel presence is absolutely essential.”
This also aligns with the broader market outlook. The India Brand Equity Foundation (IBEF), in its Indian FMCG Industry Analysis (October 2025), estimates the value of India’s D2C market at USD 80 billion in 2024, with expectations of crossing USD 100 billion in 2025. Much of this growth is being led by categories that combine frequent purchase cycles with strong digital discovery, beauty, personal care, and food and beverage segments where consumers are open to experimentation but demand authenticity, transparency, and a compelling product narrative.
“The Gen Z and millennial consumer cohorts value newness but also authenticity and unique product stories, which are best communicated in spaces that are controlled by the brand,” Dutta added, “In the launch and growth phases, this could be the brand’s digital presence including website and social media, but over time this can include pop-up stores, kiosks, shop-in-shops and even exclusive brand stores.”
CBRE’s data reflects this shift clearly, with D2C brands increasingly opting for flexible store formats and high-street locations to maximise traffic and visibility.
M&A Gains Momentum
Parallel to the offline push is a noticeable wave of consolidation. Large FMCG companies are accelerating acquisitions to capture emerging consumer niches and strengthen their digital-native capabilities.
In recent years, Hindustan Unilever has acquired Minimalist; Marico has bought Beardo, Just Herbs, True Elements, and Plix; ITC has taken over Yoga Bar; and Emami has secured full ownership of The Man Company. These deals, reported widely across business media in 2024 and 2025, point to the need for established companies to fast-track entry into high-growth, ingredient-forward, and youth-focused categories without the lead time of in-house incubation.
“Legacy FMCG companies are acquiring D2C brands to rapidly gain access to new consumer segments, product innovation, and digital-native capabilities, including direct engagement and insights. Such deals enable large companies to diversify portfolios, accelerate entry into trending segments by-passing the initial launch risks, and rejuvenate their brands with modern digital marketing expertise,” Dutta explained.
Challenges and Risks
But the acquisitions do not come without risk and challenges, analysts warned.
“However, integrating D2C operations also poses challenges, including cultural differences, the risk of stifling entrepreneurial agility, and the need to harmonise data and omnichannel strategies. The ability to nurture acquired brands without diluting their distinctive appeal will determine acquisition success,” Dutta added.
Yet even as the ecosystem expands, challenges remain. Offline stores add operational complexity, inventory planning, staffing, last-mile logistics, and real-time data integration. Still, the bottom line is that India’s D2C sector is moving into a hybrid era defined by tighter omnichannel integration, sharper product storytelling, and portfolio realignment through acquisitions.
(Published in Entrepreneur)
