admin
November 3, 2026
Pritha Pahari, The Core
3 November 2026
India’s packaged food and soap makers are running out of easy choices. Input costs have continued to rise since late February, when the Middle East conflict began disrupting supply chains and pushing up crude-linked costs.
A visible price hike, however, risks sending shoppers to a rival. To offset this, companies have reduced package sizes. However, scope for how much these packs can be reduced is limited, especially for products already sold at low price points. Take the example of a Rs 10 pack of Parle-G biscuits.
At this price, there is little room to reduce the quantity further without risking consumer dissatisfaction. Cutting the pack size could make the product less attractive, while increasing the price may discourage price-sensitive buyers.
India’s FMCG giants have squeezed pack sizes about as far as they can go. With input costs still climbing and shoppers watching every rupee, the choice between eating the cost and raising prices is coming, likely right after Diwali.
The Hikes Are In
Britannia, Hindustan Unilever (HUL), Dabur and Godrej Consumer had already raised prices by around 2-5% in the June quarter, and were weighing more for the September quarter. FMCG companies have continued to raise prices to offset higher input costs.
FMCG companies have continued to raise prices to offset higher input costs.
Tata Consumer Products increased tea prices by 8-10% between the June and September quarters, while it raised the price of its Rs 30 salt pack to Rs 32 in May and again to Rs 34 in October.
Hindustan Unilever also took price increases of around 7.5% during the September quarter, according to media reports.
Godrej Consumer Products said it would continue calibrated price increases, particularly in soaps and liquid detergents, to manage cost pressures.
Dabur has also confirmed taking pricing actions in its October business update, while Britannia had indicated a further 1.5-2% increase, largely through smaller packs. However, the latter two companies’ September-quarter results were still awaited.
Experts said that lower-income households face greater pressure because everyday essentials take up a larger share of their budgets. Affordable products such as biscuits, noodles, soaps, detergents and cooking oils are particularly sensitive to price changes.
According to experts, some manufacturers are weighing selective price increases after Diwali, possibly from December.
Shoppers haven’t walked away yet
So far, demand is holding up. Nestlé India’s sales rose 20.5 per cent to Rs 6,782 crore in the September quarter, with double-digit volume growth.
At HUL, June-quarter underlying sales growth of 10 per cent came equally from volume and price.
The market is still nervous.
Nestlé India shares closed 7.7% lower on results day after management flagged rising input costs, especially packaging, edible oils and farm commodities.
Business Standard quoted chairman Manish Tiwary as saying, “Rising inflation, particularly food inflation, is a reality.”
India’s FMCG volume growth remains mixed, although several companies continue to report resilient demand. Tata Consumer Products’ India branded volume growth eased from 16% in Q4 FY26 to 13% in Q1 FY27 and 11% in Q2 FY27.
Marico reported that India volume growth reached near double digits in Q2 FY27, following 11% in Q1.
Dabur India recorded 5% underlying volume growth in Q1 FY27, while its October update indicated double-digit revenue growth for Q2 but did not disclose a confirmed volume figure.
Overall, demand remains resilient, but revenue growth should not be confused with volume growth, particularly as companies raise prices to offset higher input costs.
Why Smaller Packs?
Satish Meena, founder of research firm Datum Intelligence, said that companies try to absorb costs first. “They can do it for one quarter, they can do it for two quarters, but at a certain point they have to pass it on to the customer,” he said. He expects much of that to happen after the festive season.
Discounts are not an option either, since margins are thin. That leaves pack sizes. “Instead of 150 grams, we are doing 120 grams, keeping the price the same,” Meena said, describing the move.
A visible price rise carries a risk of its own.
“Your positioning in the shop will change, and customers will also perceive you as an expensive product and look for other brands,” he said. Once a rival takes the shelf space, it is hard to win it back.
Devangshu Dutta, founder of research firm Third Eyesight, says price points are hard to move. “Price points are often anchored either in the consumer’s mind or by competitive benchmark pricing, making them difficult to change,” he said.
He also said the practice now carries a reputation risk. “The shrinkflation phenomenon isn’t new, but social media has given it viral visibility, which can potentially damage brand reputation.”
Pricing Pecking Order
Meena said companies will follow a set order. First they improve buying and supply chains, then trim ad spending. Next they raise prices on premium products, where buyers are more willing to pay. Raising prices across all products comes last, so they don’t lose share.
Dutta says companies are “caught in a vice” because input costs are rising while core shoppers are cautious about spending. Companies have “no option but to cut brand-level advertising and also review overheads deeply.”
Indian FMCG companies are facing rising input costs across several product categories.
In October 2026, plastic packaging costs were reported to have increased by 30–40%, putting pressure on snack makers and household-product manufacturers.
Palm oil prices rose 21% year-on-year in September, while sunflower oil increased 14%, soybean oil 9% and mustard oil 8%.
Sugar prices climbed 18% year-on-year, adding pressure on confectionery and packaged-food producers.
Tea prices rose 10% over the same period. Coffee and cocoa also recorded increases, with Arabica coffee up 19% quarter-on-quarter and cocoa rising 48%. These increases affect biscuits, noodles, chocolates, soaps, shampoos and detergents differently.
Now What?
The next test is HUL’s September-quarter results, due after its board meets on 28 October. Meena does not expect much to change in the next one to two quarters.
He says the pressure is not seasonal. “It’s because of the war happening in the Middle East… it’s a much longer issue for them,” and he points to RBI data showing some impact on demand.
Input-cost pressures could persist into early 2027.
S&P Global’s September outlook projected elevated manufacturing costs through 2027, while October data showed plastic packaging costs 30–40% higher and key polymer prices more than 50% above pre-conflict levels.
Although prices may ease if supply routes improve, these figures suggest FMCG companies could face continued cost pressure over the next two quarters.
Dutta said only a few brands will come through easily. “Few brands or products are able to build longer-term loyalty consistently and whose value to the consumer is stickier than the resistance to price movement.”
For everyone else, the room to raise prices or shrink packs is running out.
(Published in The Core)
admin
October 30, 2026
Kartikay Kashyap, Financial Express
30 October 2026
Brands are ready to roll the red carpet for consumers this festive season. But for jewellery brands this Diwali will likely be a tad different from previous ones.
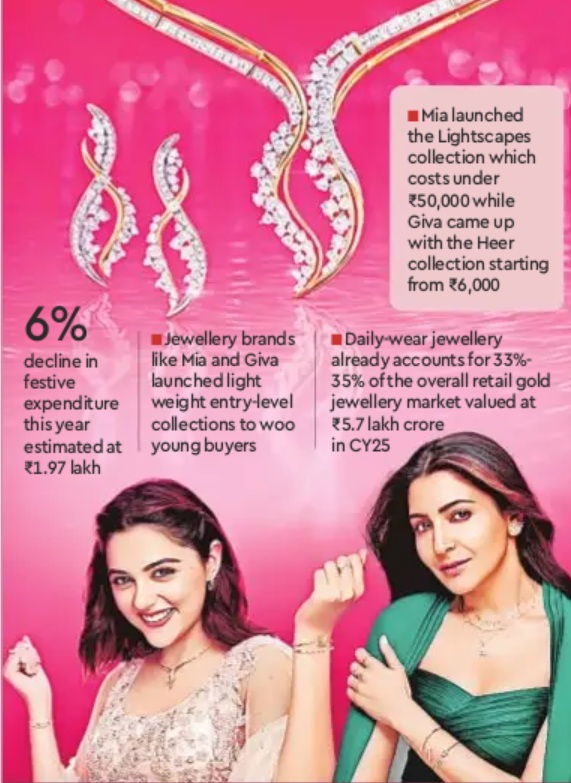
For context, consumer spending during Diwali is expected to see a decline according to Mood Of The Consumer, a survey released earlier this week by LocalCircles. On an average, urban households are looking to spend ₹20,000 in discretionary purchases this festive season, with the total spending to decline 6% from last year. The estimate puts festive expenditure at ₹1.97 lakh crores in 2026 compared with ₹2.1 lakh crores in 2025.
For jewellery brand Mia, which retails lightweight everyday jewellery, this is yet another opportunity to cast its net wider. The Titan Company-owned brand has launched Lightscapes, a new collection featuring more than 230 designs across plain gold, natural diamonds and coloured stones. The collection features a range of jhumkis, sculptural danglers, necklaces, pendants, rings and bracelets in 9KT and 14KT gold and is priced under ₹50,000 to woo first-time jewellery buyers. The supporting campaign takes forward Mia’s promise to offer women a conduit for self-expression. At the same time, the new campaign aims to push the idea of buying jewellery for festive gifting.
Mia is not the only one. Giva, which entered the gold jewellery segment during 2023 Akshay Tritiya, has introduced the Heer by Giva collection featuring polki jewellery crafted in 14 KT gold, while its Vivid Gemstone collection offers gemstone designs in 9KT and 14 КТ gold, besides a range of lab-grown diamonds. The range starts from 6,000 and goes up to ₹90,000.
The advertising pitch for jewellery brands is changing in tan-dem. If earlier they used emotion and heritage as triggers, recent advertising highlights self-expression, self-gifting and gender-neutral collections.
“The strategy to bet on affordable jewellery seems to be prompted by the surging price of gold and the hope that consumers would be keen on buying lightweight affordable jewellery this festive season,” says Devangshu Dutta, founder, Third Eyesight.
To be sure, gold prices have been volatile all of 2026. Though it has fallen more than 26% from its January record high, it is still 11.6% higher than last Diwali. For jewellery brands lightweight pieces have become the primary solution to maintaining retail volume, says Sanjeev Shukla, business advisor to fashion retailer Vinusto.in.
Lightweight jewellery has also gained traction among younger consumers in recent years. “Today’s consumers, particularly younger women, are increasingly seeking jewellery that reflects their personal style, offers versatility and fits within their budgets,” says Ajay Maurya, head of marketing & category, Mia by Tanishq. “Our focus is on making contemporary fine jewellery more accessible without compromising on design, quality or craftsmanship.”
Naresh Gupta, managing partner & chief strategy officer, Bang In The Middle, believes that younger generations especially Gen 2 buyers are drastically changing what and how they buy. Instead of heavy, occasion-led, or locker-stashed gold pieces meant strictly for weddings and festivals, they are pivoting toward lightweight, design-forward, and everyday wear. They want Indo-Western pieces that pair as well with a Diwali lehenga as they do with an office-event blazer. “The Diwali campaign strategy aligns with the jewellery retailers’ strategy to catch on the younger lot and recruit them into the ecosystem early in their stage,” says Gupta.
Daily-wear jewellery already accounts for 33%-35% of the overall retail gold jewellery market valued at 15.7 lakh crore in CY25. Organised retailers held about 37% of this market in CY25.
Apart from self-expression, light-weight jewellery also makes a good case for gifting. “Entry-level fine jewellery and budget-friendly pieces work particularly well for gifting, which makes them relevant during the festive season,” tells Disha Shah, founder, DiAi Designs.
A golden opportunity
Will Mia’s decision to take the affordability route cannibalise stable brands like Zoya and Carat Lane? If young buyers form the habit of wearing lightweight jewellery, they might do that during wedding as well, says Gupta.
One might argue that brands like Mia enable new buyers enter the fine jewellery ecosystem and move up the ladder to become the customers of brands like Tanishq and Zoya. But Vinusto’s Shukla argues repeat buying might still be a challenge for the affordable jewellery players.
For Mia, which crossed the ₹2,000-сrоге revenue milestone in the financial year 2025-26, the festive season represents a crucial window to turn up the volume. Experts say the season makes up 15-20% of the annual jewellery sales and some brands have gone on record to say they have already seen a 50% surge over pre-Diwali sales.
DiAi’s Shah remains optimistic. “We are seeing new customers explore jewellery, alongside existing customers who are looking to redesign or upgrade pieces they already own. Festive occasions provide a natural reason to enter the category, while contemporary, everyday fine jewellery can help build that relationship beyond the festive period,” she says.
(Published in Financial Express)
admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
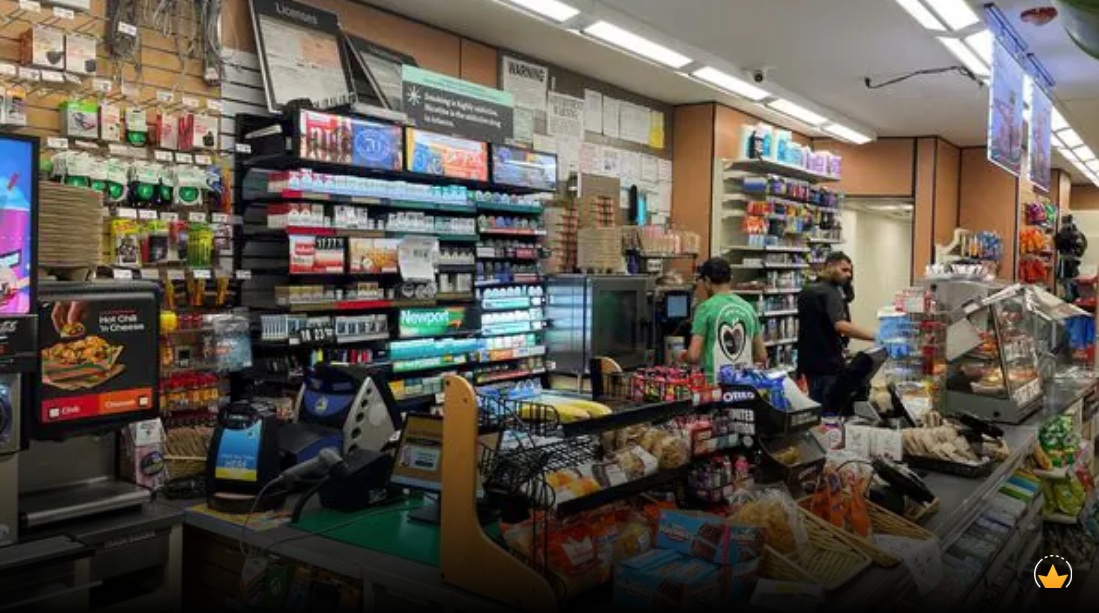
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
September 1, 2026
Vikash Tripathi, Outlook Business
1 September 2026
Eight decades ago, the ‘nationalist businessman’ GD Birla helped prepare the ‘Bombay Plan’, which asked the state to pro-vide for the bare minimum needs of its people. His plan asked for 2,800 calories of well-balanced food per day, 30 yards of clothing per year and 100sq ft of housing per person.
Today, seventh-generation Aryaman Vikram Birla is betting on an entirely different opportunity: premium dining. “We continue to believe in the remarkable potential of the premium casual dining space, spurred by rising disposable income and evolving lifestyles,” the 29-year-old said after Aditya Birla New Age Hospitality acquired KA Hospitality in 2023.
The Birlas are not alone in trying to cash-in on rising prosperity in India. In the past five years alone, India’s top 10 industrial groups have announced new ventures in consumer-facing sectors or doubled down on existing ones. A rough tally of these investments crosses ₹4.8 lakh crore.
For decades, these same business houses built their dominance in core sectors like steel, power, aluminium, cement and chemicals, laying the industrial backbone of the economy. This helped the nation become a large producer of such goods and, in some cases, an exporter as well.
But as India’s economic conditions changed, so has the focus of its largest conglomerates.
For the likes of Tata, Aditya Birla, Bajaj and Bharti, that journey started way back. “What has changed in recent years is the speed and openness of the amount of capital being invested,” says Jitender Kumar, associate professor and programme chairperson, retail management programme at Birla Institute of Management Technology.
“It is not ‘opportunistic’ reasons, it’s structural reasons.”
Two factors seem to be driving the shift: the first is the arrival of an affluent consuming class that can buy branded and premium goods, and the second is the attraction of consumer businesses as a way to diversify revenue and, in some cases, improve the quality of earnings.
The Rise of Affluence
A couple of decades ago, if an Indian household had some extra cash, it often meant buying more of the same. Today, it increasingly means buying better. Even salt is being upgraded, from iodised to Himalayan pink or rock salt. The same shift is visible in bigger purchases: sports utility vehicles (SUVs) over hatchbacks, and ₹1cr-plus homes over budget flats.
But India isn’t simply consuming more. It is moving from basic consumption towards discretionary, branded and premium consumption. This boom is most clearly seen in the rapid expansion of the financial infrastructure that enables consumption. Formal retail credit penetration has more than doubled over the past decade, according to a TransUnion Cibil report, driven largely by personal loans, credit cards and consumer durable loans. Meanwhile, the government-backed Unified Payments Interface has untethered spending from the cash in a buyer’s wallet.
The signs show up across the broader consumption economy. Homes priced above ₹1cr accounted for 54% of total sales in 2025, up from just 30% in 2023—the market that decorative paints and home solutions are chasing.
Out of 4.7mn cars sold in the financial year 2025–26, SUVs accounted for more than half.
“The consumer market has grown substantially—not only through rising incomes but also the dramatic expansion of branded consumption across product verticals,” says Devangshu Dutta, founder of management-consulting firm Third Eyesight.
The bets are also getting more varied, from Reliance Retail tying up with global brands like Fenty and Skims to the Bharti Group bringing Olive Garden to India.
The Lure of Returns
For a passenger walking through an airport, the flight is only one part of the journey. There is coffee before boarding, food between flights, a lounge, retail outlets, parking and a host of other things to spend money on. For Adani Airports, those non-aero businesses are increasingly becoming the more lucrative part.
Its non-aero operations already generate about ₹2,500cr, with returns in the high-20% range, against roughly 12% from regulated aeronautical operations.
Jeet Adani, director of Adani Airport Holdings, expects the share of aeronautical revenue to fall to around 10% of total revenue, with non-aero becoming the bigger growth driver. The motivation can be seen as an escape from a return ceiling as much as a bet on rising affluence.
As Kumar puts it, consumer businesses help the conglomerates in two major ways. First, they help insulate them from volatile and often punishing commodity cycles, and second, they often offer far better returns with lower capital intensity and faster cash conversion.
Reliance Industries (RIL) shows how significant that shift can become. By 2025–26, its consumer-facing arms, Jio Platforms, Reliance Retail Ventures and Reliance Consumer Products, together contributed over 40% of group revenue and nearly 60% of operating profit.
And there is another advantage. “A small business, when it wants to build a new venture, faces constant margin pressure and often has to build its supply chain from scratch. A large conglomerate can leverage its existing scale, infrastructure and supply chain to enter a new business far more efficiently,” explains Kranthi Bathini, equity strategist at WealthMills Securities.
Different Strokes
In chasing consumers, some conglomerates are following the fastest-growing categories, while others are using their existing industrial capabilities to enter consumer-facing businesses. One is trying to build an entire ecosystem around it. But the lines between these approaches are not always clean.
Tatas is doing both: building entirely new consumer brands while also using the industrial ecosystem it has built over decades.
For Tatas, the consumer opportunity has largely been about following where spending is moving. Their consumer ventures have followed this arc longest. It began decades ago with Lakmé (1952), Tata Tea (1962) and Titan (1984). Tanishq and the expansion of Trent under brands such as Zudio are only the latest examples.
At Tata Consumer Products, once largely a staples business built around salt, tea and pulses, the focus has been shifting towards value-added foods and beverages, with ₹7,000cr spent on the acquisitions of Capital Foods and Organic India in 2024. Across companies such as Tata Digital, Indian Hotels, Air India and Tata Motors Passenger Vehicles, the group has announced close to ₹93,180cr in investment over the past five years.
Aditya Birla’s jewellery chain Indriya and its move into premium hospitality belong to the same category of ‘pull-based’ diversification.
JSW is taking a different route. It is taking its existing industrial strengths one step closer to the buyer. The group, which has traditionally been focused on areas such as steel, energy and cement, has expanded into consumer-facing areas such as auto, paints and home solutions.
It launched JSW Paints in 2019, and acquired a controlling stake in paintmaker AkzoNobel India for ₹8,986cr last year. Its strategy is to leverage an established network of contractors, dealers, architects and builders to reach consumers.
The same strategy can be seen in its push into autos, acquiring a 35% stake in the Indian unit of China’s MG Motor in 2024, leveraging synergies with its established steel business.
At Tatas, too, group companies like Tata Steel, Tata Power, Tata AutoComp, Tata Technologies and TCS are doing significant businesses with Tata Motors.
Adani is also using an asset it already controls to move further into the consumer’s wallet. Adani Airports announced a ₹20,000cr investment in June to develop hotels, retail, entertainment and commercial infrastructure around its eight airports, and has signed hotel management agreements with IHG Hotels & Resorts for five hotels. City-side developments could contribute 30–40% of Adani Airport Holdings’ non-aero revenue.
Yet another example of the extension strategy is Aditya Birla Group’s attempt to diversify from cement, metals and textiles into decorative paints with Birla Opus.
RIL took a different approach: trying to connect multiple consumer businesses into one ecosystem. It expanded its retail network through new formats and acquisitions, added brands and partnerships, and then built a consumer-goods business around acquisitions such as Campa Cola and Lotus Chocolate.
That expansion was helped by billions of dollars raised by both Jio Infocomm and Retail Ventures from foreign investors in 2020. The group now plans to spend another ₹8,000cr expanding consumer goods manufacturing. The advantage of having that kind of scale is clear. If RIL has Ajio at a mall and, next to it, GAP and Herschel, it can negotiate better rental terms.
For conglomerates, Kumar points out, the next level of competition will not be based on investment, “but on the ability to create different consumer experiences, foster innovation and create lasting brand loyalty through the integration of these capabilities”.
Can Scale Win?
When Reliance Fresh opened its first stores in 2006, it was part of a rush by some of India’s biggest business groups to crack organised retail. Aditya Birla Group, RP-Sanjiv Goenka Group’s Spencer’s and Kishore Biyani’s Future Group were all betting that organised retail could transform the way Indians shopped. What followed was years of experimentation, losses and, for some, eventual retreat.
Birlas essentially gave up on grocery retail after a decade of heavy losses and exited entirely.
Future was pushed into insolvency after a controversial ₹24,713cr deal with RIL. Spencer’s is still trying to find its footing, with ₹249.33cr in net losses in 2025–26.
Conglomerates may have deeper pockets, but that does not automatically make them better at selling to consumers. India has seen some of those bets fail or take years to work. And even among today’s biggest players, the results are still mixed.
Tata Sons has been in this segment longer than the Ambanis, yet its consumer businesses still make up less than 40% of its total revenue —a share that has not changed since 2020.
These groups have what most standalone consumer companies don’t: capital, distribution, infrastructure, brands, scale.
But winning consumers takes something else entirely—reading what people want, building brands, innovating fast and earning loyalty.
“In B2B [business to business], it’s about manufacturing at scale, getting your costs down. Then you can compete. In B2C [business to consumer], it’s all about the product. With the right product at the right price, you have a chance to win in the market,” Parth Jindal, managing director of JSW Cement and JSW Paints, told Outlook Business in 2025.
Tata Sons’ chairman N Chandrasekaran hit the same wall while revamping the group’s consumer unit. “I have the money. But I don’t have the team to run it,” he had told Sunil D’Souza while hiring him to lead Tata Consumer Products in 2020.
Reliance and Tatas have had the longest head start, but even their journeys show how difficult it is to turn scale and capital into consumer businesses. Birla, JSW and Adani are now trying to make that transition in their own ways.
A longer tail—Bajaj in hospitals, L&T in retail finance and education, Mahindra in insurance and hospitality, Murugappa in electric mobility—is playing it safer, going deeper into what it already owns rather than chasing new categories.
What ties them together is a bet on consumers buying not just more but better, and on those consumers being worth more per rupee of capital than the industrial customers who built these houses.
The prize is growing, but so is the competition. Capital and scale may get these conglomerates through the door. They won’t guarantee a seat at the table.
(Published in Outlook Business)
admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
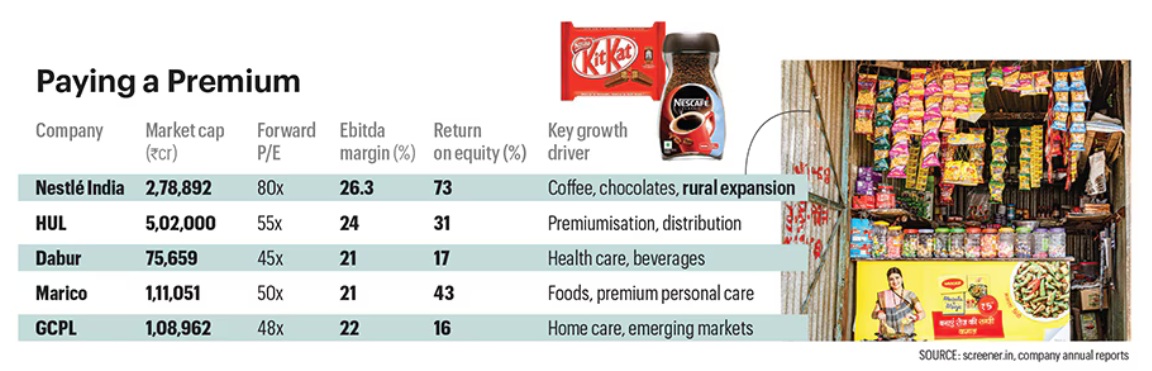
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
