
admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
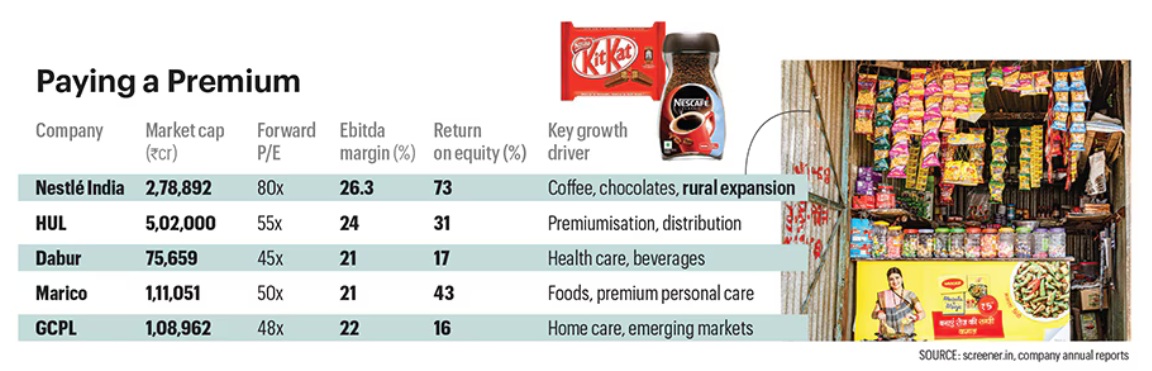
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
admin
June 12, 2026
Christina Moniz, Financial Express/Brand Wagon
12 June 2026
Legacy luggage brand VIP Industries is shedding some of its old baggage. The company, which manufactures Skybags and Aristocrat along with its flagship VIP range, has gone beyond cringey makeovers solely to attract Gen Z, and has embarked on a transformation journey that leverages its legacy to purvey a fresh range of offerings.
The company is modernising its digital presence and supply chain to catch up with competitors.
Managing director Atul Jain admits that the company has been a bit slow on the e-commerce front. It is reinventing its online store, while also making its products available across other e-commerce channels. “Quick commerce is becoming an important channel since there are several use occasions and segments within the luggage market. For instance, consumers often make last-minute purchases for a weekend trip via quick commerce. School bags and backpacks for kids, also great gifting options, are seeing good demand on these platforms,” he says
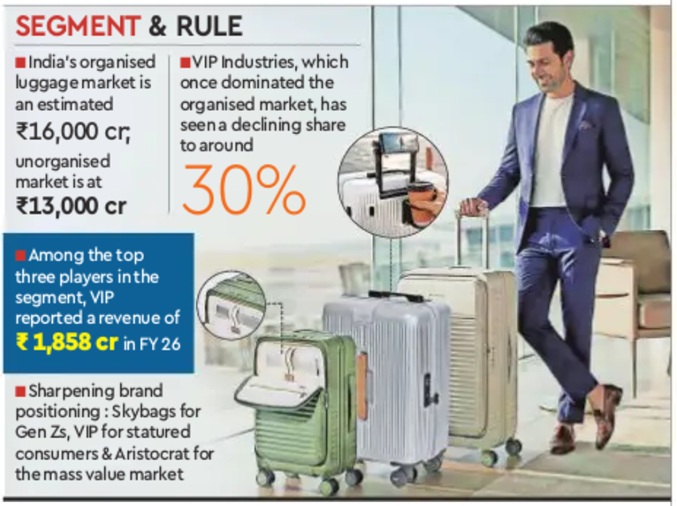
The company, which once dominated the ₹16,000 crore organised luggage market in India, saw a bit of a shakeup last year when the Piramal family sold 32% of its stake to a private equity firm. But it continues to be among the top three players in the category with a 29-30% market share. “Luggage plays the role of a traveller’s companion. We are creating designs to fit that role,” says Jain. “For example, our new VIP suitcases have a coffee cup holder and our cabin trolley bag has an easy access compartment for devices like laptops and iPads.”
The transformation goes beyond the product. VIP’s 350 exclusive physical retail touchpoints in the country are being revamped to offer a new customer experience.
Unpacking opportunities
Overits 55 years, VIP has grown from a briefcase brand into Asia’s largest luggage maker, housing labels like Skybags, Aristocrat, and Carlton (premium segment). While VIP is a premium offering targeted at business and travellers, its Aristocrat brand operates in the mass market and the budget-friendly Alfa targets consumers who typically shop in the unbranded segment. Aristocrat and Alfa together contributed upwards of 40% to the company’s revenue in FY25, followed by Skybags (28%) and VIP (20%).
Like many legacy brands, the VIP Industries’ faces the challenge to ia, stay relevant among Gen Z buyers as a plethora of digital-first brands swamp the market. “VIP has lost ground on relevance and desirability to a generation for whom luggage, like sneakers, is an expression of identity. To them, VIP feels like their parents’ brand,” says Nisha Sampath, managing partner, Bright Angles Consulting. D2C players in the category operate in the business of “lifestyle accessories” and not for “luggage” per se, she points out.
With a design-forward approach, incorporating features like compression systems, silent wheels and charging ports, these new-age brands have embedded themselves in travel “culture”, while also being Instagram worthy, say experts.
Jain says Skybags is VIP’s Gen Z focussed brand, which has over 8,20,000 Instagram followers. “We are sharpening our positioning for Skybags in our design, advertising and marketing outreach, especially on social platforms. The brand has a clear differentiation with youthful colours and prints to attract younger consumers,” he adds.
While D2C players have seen notable growth in recent years, they don’t have the kind of trust and brand equity that VIP has cultivated across its brands, nor do they have the scale or revenue that legacy brands have, he says.
Experts believe there is a significant growth opportunity for legacy players given that the unbranded market still accounts for ₹13,000-14,000 crore. The important lever for legacy brands is to clearly demonstrate value beyond price. “The unorganised market competes heavily on affordability, so organised players need to communicate durability, warranty, after-sales service, and consistent quality – areas where they have a strong inherent advantage over unorganised alternatives,” says Praveen Govindu, partner at Deloitte India. He adds that these brands should also invest in advertising and communicate this value to the end consumer.
Not only are the needs different among different consumer groups, competitive pressures are also diverse. “VIP can segment the market more cleanly with its portfolio of brands if it maintains absolute distinction to ensure clear consumer targeting across not just product attributes and pricing, but also communication and channels,” says Devangshu Dutta, CEO, Third Eyesight.
(Published in Financial Express)
admin
March 1, 2026

Apoorva Mittal, Economic Times
1 March 2026
Resshmi Nair, 31, had grown used to the dotted red bumps on her arms. Her dermatologist diagnosed it as keratosis pilaris aka strawberry skin. It is a harmless skin condition that often affects legs and arms but Nair, a Mumbai-based marketing consultant, wanted it gone. She slathered lotions and salves but to no avail. Then she chanced upon an Instagram reel which showed an oil-based in-shower spray that promised to take care of her problem. “It was very tempting as it resonated with a personal concern,” she says. She is now on her third bottle. The bumps haven’t disappeared entirely, but they have become smaller, she says.
Like Nair, there are many who seek solutions tailormade for their beauty bugbears. Consumers who once searched for moisturisers and shampoos now look for niche products for hair and skin. They want to repair skin barrier, tame baby hairs and minimise facial pores.
A new generation of Indian beauty and personal care (BPC) brands are both listening to them and leading them. Focused products, they realise, could help them stand out in a crowded sector dominated by FMCG giants. While problems like acne, frizzy hair and rough skin have always been around, experts say the commercial importance of solving them narrowly and packaging that specificity as a brand strategy have become more intense of late.
India’s direct-to-consumer (D2C) beauty and personal care market—which is heavily invested in micro-problem targeting—is estimated to be $4.5 billion in FY2025, according to consulting firm Redseer. The new-age brands could account for 25-35% of total BPC spends by 2030. “Three major factors have contributed to this: one, the rise of digital medium for both commerce and marketing, which created a segue for new brands to launch and scale; two, younger consumers (Gen Z and young millennials) have become ingredient literate and look for results over broad promises; and three, competitive intensity in the market is pressing brands to position as per the right niches,” says Kushal Bhatnagar, associate partner, Redseer.
The shift is measurable on beauty retailer Nykaa’s platform. “Consumer vocabulary is far more evolved,” says a company spokesperson. Searches driven by specic concerns or ingredients are growing faster than broad category items. While foundational concerns like acne and brightening remain relevant, the platform is seeing strong growth in queries around pigmentation, barrier repair, pore care and specic hair issues. “This fragmentation is actually a sign of a more informed and aware consumer base,” the spokesperson adds.
ZOOMING IN
For young D2C brands, this behavioural shift has opened a narrow but potent entry point. Instead of launching another shampoo or moisturiser, they launch a product targeting a single problem and market it in an easily demonstrable short-video format. In the current beauty landscape, the market has shifted from general solutions to hyper-targeted efficacy.
Moxie Beauty, founded by Nikita Khanna in 2023, illustrates the playbook. Khanna, who previously worked at McKinsey, began with a focus on wavy and frizzy hair, a segment she herself belongs to. But it was one particular styling product, the flyaway hair stick, that went viral, propelling the brand into visibility. She says, “The wavy hair routine required us to educate people, which took time. But one can understand the flyaway wand in five seconds.” And it targeted what she calls a “widely held pain point”. That helped Moxie cut through crowded feeds and end up on consumer shelves. “Being synonymous with a category helps,” she says. “When people want a wax stick or flyaway stick, they search for our brand.”
That shift—from paying for visibility to being searched for directly—is critical in a market where customer acquisition costs (CAC) can be punishingly high. For many D2C brands, launching a sharply defined product is a way to reduce discovery friction and lower early-stage CAC. But a brand cannot be built or scaled on gimmicks, says Khanna. “If you solve only for what will look good in a video and will go viral, you won’t be able to scale. And if it’s a gimmick, people won’t repeat the purchase,” she adds.
Divanshee Jindal, cofounder of the brand The Solved Skin, says companies have to get the “product-communication fit” right. Her brand’s liquid pimple patch, which is designed to mask acne under makeup, is quickly emerging as its hero product. “People get excited when a product feels relatable and authentic,” says Jindal. “A new, convenient format that solves a real pain point makes consumers willing to try a new brand. But if it’s a standard product, say, a salicylic acid face wash, they will often default to a brand they already trust.”
SMALL IS BEAUTIFUL
The idea is to start small but evolve. Moxie, for instance, has moved beyond textured hair into solving broader “Indian hair problems” like damage repair and anti-dandruff that has brought in male consumers as well. “Curly or wavy hair was a huge, underserved problem,” says Khanna. “But the thought was always to solve other problems as well.” Moxie, which recently raised $15 million in a funding round led by Bessemer Venture Partners, says it has crossed Rs. 100 crore in annual recurring revenue on its two-year mark, and is seeing roughly 50% consumers coming back in six months across platforms. However, it says profitability is harder to crack because of intense competition from new brands and changing channel mix.
Mani Singhal, MD of the consulting firm Alvarez & Marsal, points out that most successful D2C brands started out with a sharply defined hero product. “Earlier it was natural vs chemical or price disruption; today it’s much more about efficacy proof, ingredient transparency, visible results and credible
storytelling,” she says.
From the manufacturer’s side, Nishit Dedhia of Kain Cosmeceuticals, a cosmetics manufacturing company, says, “It is easier today for brands to target special concerns. That specificity helps them build a differentiated product earlier on.” Most brands, he explains, x a major problem such as acne, dryness, pigmentation and then layer in a niche twist. Strawberry skin, once not a mainstream concern, is now a category. “People didn’t know the term. Once you give it a name, they identify with it,” he adds.
Dedhia describes the portfolio strategy as 8-2 or 9-1 where eight or nine products are general, incremental variations of core needs, while one or two are “category-building products” that require significant consumer education or product communication but create their own search demand. “That is the only way you get out of the vicious cycle of paying for visibility,” he says. “When people search for your brand directly, CAC comes down.”
Devangshu Dutta, founder of management consulting firm Third Eyesight, says micro-problem framing is “co-created” by consumers and companies. “The fragmentation is real, but the language used to describe it is heavily brand-driven,” he says. Terms like “strawberry skin” or “glass skin” correlate with influencer campaigns but label pre-existing dissatisfactions that mass products did not address sharply.
However, sometimes, in the race to differentiation, brands go for outlandish ideas. Dedhia says brands increasingly approach manufacturers with amusing asks in the quest to stand out. For instance, beard fillers packaged like mascara or plumpers for face and neck.
PRODUCE & PERISH
The problem is that the mortality rate of skincare brands is very high in India. Dedhia estimates that around 60% companies shut down in three years. Many brands burn through capital chasing ads and trends without building repeat customers or a community.
“For a brand to cross over from being a curiosity-driven purchase to being part of a regimen needs a minimum 25-30% of customers showing up as repeats after three months, while truly successful brands reach higher repeat numbers,” says Dutta.
Subscriptions are an even stronger test. “Generic formulations, me-too products and influencer spends can get you first users, but repeats will happen only from the user getting demonstrated value,” says Dutta.
But growth does not equal stability. CAC typically starts low for niche products, rises during scaling-up and stabilises only if organic demand takes over, says Bhatnagar of Redseer. Quick commerce accelerates discovery but compresses margins due to the high commission rates on these platforms, promotional expectations and lower average order values.
Singhal, who says a consolidation phase is underway, adds: “Niche entry can work extremely well if the problem is frequent enough and the solution is demonstrably effective.” Durable brands deliver consistent performance, build adjacencies beyond the first niche and maintain disciplined unit economics.
“If repeat rates don’t stabilise, economics becomes very challenging, very quickly.”
PERSONALISATION AHEAD
For Aparna Saxena, founder of Delhi-based beauty brand Antinorm, the next decade will be defined by even greater personalisation. Her brand has multifunctional products that are timesaving. Saxena says she surveyed about 250 women above 25 years of age and found that five-step routines typically do
not last after two months. Antinorm’s architecture rests on multifunctionality, like a leave-in cream that doubles as heat protectant and promises a “presentable” hair look without a blow-dry. Its most popular product is a spray that cleanses and moisturises, which they dub as “instant shower” or “facial in a flash”.
She says the brand, which launched in July last year, will close next fiscal with about Rs. 25 crore in revenue. Repeat rates are currently under 25% “because the denominator is expanding rapidly”, she adds. “Between 2020 and 2025, customers moved away from incumbents and got used to having options and trying newer brands,” she says. “Now they have routines in place. The next five years will be defined by more and more personalisation and micro-problem solving.” The beauty is about to go really skin deep.
(Published in Economic Times)
admin
February 18, 2026
Kartikay Kashyap, BrandWagon, Financial Express
18 February 2026
IKEA HAS BEEN around in India for about eight years, with another three years before that spent studying the market. It has developed a range that it deems “locally relevant-like the roti maker, the tava (pan), the belan (rolling pin), and the pressure cooker -which now constitute about 50% of the products it offers in the country. It has shifted its communication strategy to sync with local culture and fit into local spaces and has worked hard to beef up its omnichannel sales model with about 30% of its sales originating online. But profitability has remained elusive for the retailer whose global sales reached approximately €45billion in the 2015 financial year (FY25).
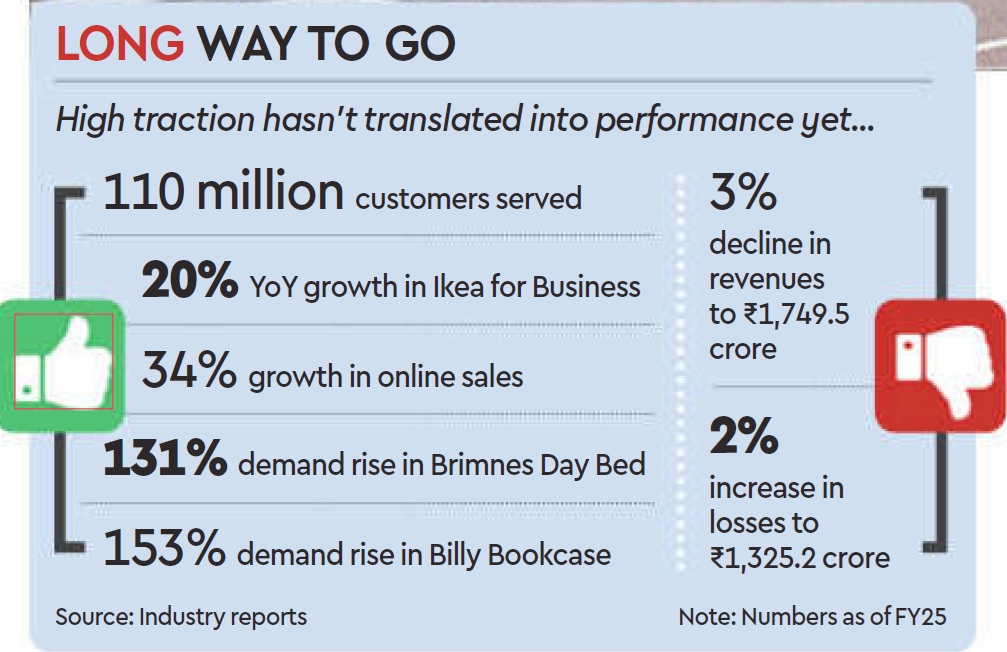
Just for context, the company’s India entity widened its losses by about 29 to 1,325.2 crore in the financial year ending March 31, 2025 (FY25). The revenue also dipped 3 to 1,749.5 crore from 1,809.8 crore in FY25.
So now the brand is taking a leaf out of its China playbook and tweaking its retail formats. Starting last year, it started piloting smaller store sizes ranging from 15,000-20,000 sq ft that are more cost-effective to set up and faster to integrate with its omnichannel model. “The goal is to create a simpler and more efficient shopping experience,” Ingka Group Retail Manager Tolga Oncu had said when the concept was unveiled last August.
Five months on, the furniture retailer is looking to take a step up the ladder – setting up new stores in the 50,000-70,000 sq ft range in the country, which will sit comfortably between its smaller stones (15,000-20,000 sq ft) and big box retail outlets (4 lakh sq ft), Adosh Sharma, country commercial manager at Ikea India told FE recently. Ikea’s broader plan also includes doubling its investments in the country to over 20,000 crore ($2.2 billion) over the next five years and improving local sourcing.
Will all this help the retailer grab a larger share of the highly fragmented furniture and furnishing market in the country? Will the brand achieve profitability in the next two years in keeping with its plans?
Ikea realises copy-pasting its global retail strategy in India is not going to work. That explains its recent moves to tweak store sizes and product design. Over and above the regular 5-M-L strategy, the fourth format the brand is developing comprises no-frills planning and order points, focused on customers who want to design homes or seek complex solutions without distraction.
“Smaller stores, which fulfill purpose-led needs will help them to get closer to their customers,” says Devangshu Dutta, founder & CEO, Third Eyesight.
The furniture and home decor segment has been up against slow purchase cycles in India. Smaller sized stores that are closer to residential arras might help step up the frequency of purchases. “Players are moving towards a higher purchase frequency strategy and smaller stores will help lkea cash in on this opportunity,” says Kushal Bhatnagar, associate partner, Redseer Consultant Strategy. He says quick commerce has helped improve the purchase cycle in the home decor space, and that is something Ikea will likely tap going forwand.
Dutta says Ikea has taken a long-term view on India and the investments in the pipeline is an indication of the opportunity that awaits players.
The brand claims it has served close to 110 million customers in FY25 across channels, and online sales are growing 34% compared to the previous fiscal. While furniture contributed the lion’s share of its revenue, the food business contributed 100% and Ikea for Business (tailored solutions for businesses) another 19% to its topline.
(Published in Financial Express)
admin
January 31, 2026
Surabhi Prasad, Business Today
Print Edition: 01 Feb, 2026
The last two years—2024 and, more notably, 2025—saw a wave of protests by a new generation of students and young professionals looking for political change, better economic conditions and more climate awareness across countries, including Bangladesh, Nepal, Indonesia and the Maldives.
But beyond these uprisings, Gen Z, the term used to describe those born in late 1990s to the early part of the 2010s and currently aged around 13-29 years, are not only questioning but also bringing forth changes in societal norms and economic behaviour. It’s not just a generation gap!
Gen Z are digital natives. They are tech savvy, have grown up with Internet in their homes, iPads as their support system, social media as a constant companion and take digital payments, online and quick commerce for granted. They tend to be night owls, the real gigsters, at home with artificial intelligence (AI) and machine learning, and with a lingo—cap, salty, suss and tea—that make others scratch their heads.
They also have newer challenges—rising unemployment, an uncertain economic environment, the rise of AI that has put a question mark on the future of work, climate change that is turning more real by the day, and skyrocketing real estate prices that mean a dream home could remain just a dream. Still, they are the rising consumer force who, over the next decade, are poised to become the largest chunk of the labour force and the focus of most companies.
For a country like India that is still young, Gen Z will soon be the economic force to reckon with. A recent report by not-for-profit think tank People Research on India’s Consumer Economy (PRICE) estimates that as of 2025, nearly one in five young individuals globally lives in India. “This is a formidable 420-million strong force, constituting approximately 29% of the nation’s total population, and made up of individuals aged between 15 and 29 as defined by India’s National Youth Policy (2014),” it said.
Labour sociologist Ellina Samantroy, Fellow at the V.V. Giri National Labour Institute, says India’s expanding Gen Z or youth workforce offers a significant opportunity for the country to reap the demographic dividend. As per the recent Periodic Labour Force Survey 2023-24, around 46.5% of the labour force is in the 15-29 age group. “There has been an increase in labour force participation in this age group from 42% during 2021-22. One can see the economic growth potential of this cohort,” she says.
However, with transitions and emerging opportunities in the world of work, it is important to harness the potential of this population cohort with adequate access to education and skilling, she says.
Devangshu Dutta, founder and chief executive of Third Eyesight, a boutique management consulting firm focused on the retail and consumer products ecosystem, says Indian Gen Z consumers are not a uniform cohort.
“A critical issue in India is the coexistence of aspiration and constraint, and India’s Gen Z are shaped by a mix of high digital exposure and wide economic disparity. While they are ambitious and globally aware, their purchasing power varies sharply across segments and locations,” he says.
Further, urban, higher-income Gen Z display global consumption behaviours such as brand experimentation, social commerce and premium aspiration, whereas a large proportion of Gen Z in Tier II, Tier III and rural India is highly value-driven and necessity-led, while drawing their inspiration from global and national sources. He also points out that unlike Millennials, Indian Gen Z are also entering the workforce in a more uncertain economic environment, making price sensitivity, smaller pack sizes and flexible payment options important. “Employment patterns such as informal jobs, gig work and delayed income stability are influencing consumption cycles and brand loyalty,” he says. There is a strong preference for digital discovery, vernacular content and peer-led recommendations, with trust built through community and relevance rather than legacy brand status.
Rising aspirations of Indian households and changes in consumption pattern with a marked move from essentials to more premium products have been well documented, most recently in Household Consumption Expenditure Surveys. But more granular, individual-level data from PRICE shows marked changes in education levels and behaviour of Gen Z and other cohorts such as Millennials (those aged between 30 and 45), Gen X (aged 45-60) and Baby Boomers (60+). A 2024 PRICE ICE 360 Survey of 8,200 respondents (18–70 years) in 25 major cities showed that Gen Z is the most educated cohort, spends the most time browsing the Internet and is more engaged with e-commerce and paid digital services.
Multinational and domestic companies are also now waking up to the Gen Z wave and are realising that they need to review strategies to gain the attention and loyalty of Gen Z as consumers and workers.
“Fashion, beauty and personal care, food and beverages, and mobile and consumer electronics are at the forefront of change in India,” says Dutta. Responding to Gen Z requirements, companies are designing products at accessible price points, expanding entry-level ranges and leveraging sachetisation and subscription models. Brands are investing more in regional languages, local influencers and platforms such as short-video and social commerce channels that resonate with young Indian consumers, he says.
But this process is still at a nascent stage, and many companies and analysts are still trying to assess this generation.
For the 34th Anniversary Issue, we at Business Today decided to decode what Gen Z is truly about, what influences them the most, what they aspire to purchase, what they can afford and what this means for India Inc. Over the course of the last few months, our newsroom saw animated discussions as senior editors sat down with younger colleagues to discuss lifestyle choices, brand loyalties and career ambitions, as we drafted an issue brief and a potential survey.
We then got in touch with PRICE, which worked with us on our survey objectives and tweaked the questionnaire. The result—a first-of-its-kind exercise where PRICE surveyed 4,311 Gen Z respondents, who are now entering the workforce with an income of their own, residing in metros and Tier II cities. The survey covered gender, education, employment status, personal income and household income classes. The main focus was urban, educated Gen-Z who has the income to be a strong consumer.
The research examined consumption behaviour across discretionary and essential categories, savings and credit attitudes, digital influence, brand loyalty, aspirations, and future spending intent.
And the results are indeed, surprising! The survey reveals that traditional consumption models that were built around age-based life stages, linear career progression and early credit adoption no longer hold for Gen Z. “This cohort’s behaviour reflects early exposure to economic shocks, greater career volatility and a redefinition of success away from speed toward resilience,” it underlines.

For businesses, misreading delayed demand as permanent weakness risks underinvestment just as Gen Z approaches its next consumption inflection, it warns. For financial services, premature credit push without trust-building will underperform. For consumer brands, price-led acquisition without quality consistency will fail to convert into lifetime value.
Delve into this issue where BT brings to you the in-depth findings of the survey and explains what this means for companies as they vie for a share of this growing consumer segment. Gen Z is not just about rizz and drip, it is giving the main character energy as they come of age.


(Published in Business Today, issue dated 1 February 2026)
