admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
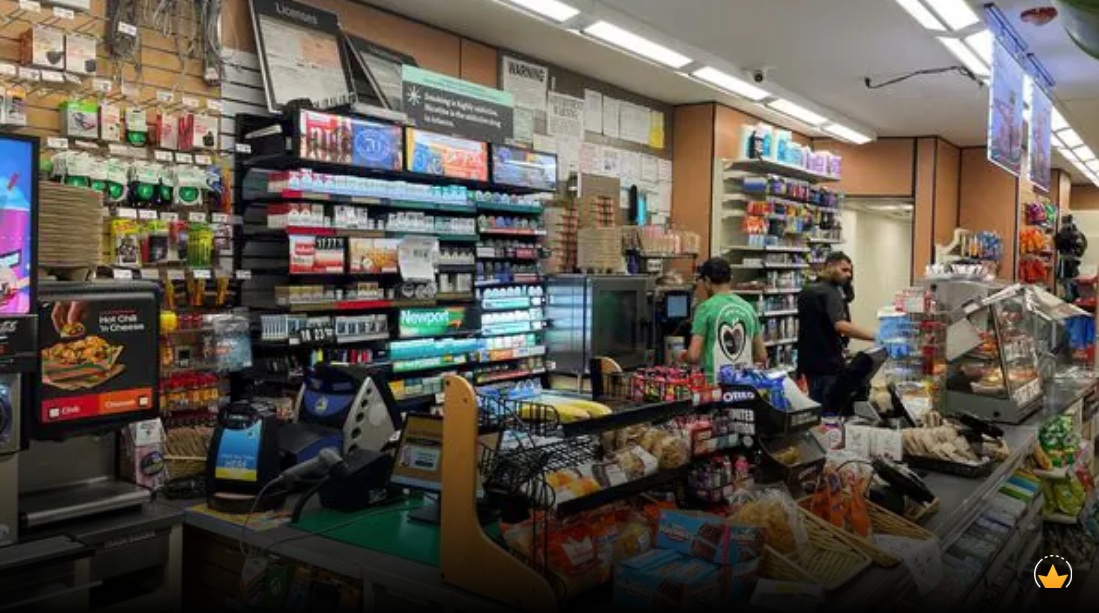
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
October 7, 2026
Vidya Sathyapriyan, ET Brand Equity
7 October 2026
Every single month, leather-goods brand Hidesign changes the storefront of its airport stores. The reason: “You can’t bore the man or woman who’s coming to the airport every week,” says founder Dilip Kapur.
But then what makes the airport shopper any different from someone walking into a high-street or mall store? Affluent? Sure. Willing to spend? Mostly. Time-poor and seeking convenience? Definitely.
That mix presents a particular challenge for brands: understanding what and why travellers will buy, and how quickly they can buy it.
Some have learnt to make the often lopsided economics work. Others are running an expensive billboard with a billing counter attached.
Crunching Numbers
The economics are punishing.
Airport rents, minimum guarantees, revenue-share, staffing and operating costs can make them significantly more expensive than conventional retail. For example, a good mall in Chennai charges roughly Rs. 350-800 per sq ft monthly in retail rent, compared with Rs. 150-200 per sq. ft. on the high street. Airport rentals can rise to as much as Rs. 6,000 per sq. ft. Similar differentials play out in other major cities.
Yet brands keep signing on because the alternative would be an advertising site with no retail attached. “A hoarding is for all and sundry and 1D,” says S. Shriram, founder of Miles2Go Consulting Services. “In the airport, captive audience, engagement is 3D and sometimes even 4D – touch and feel, trial, buy, and even return elsewhere.”
For deep-pocketed brands, spending on airport visibility can be justified even when store-level profitability is modest or even non-existent. Others gotta move on.
Go Colors, for instance, is rationalising stores at airports where the economics are not working. “The opportunity remains strong, but the location must justify the cost of access to the consumer,” says CMO Vatsal Koolwal. “As a broad benchmark, rentals in the range of 15-20% of revenue can work, provided the rest of the cost structure is managed effectively.”
The right sell
Six of Hidesign’s top-10 stores in India are at airports, says Kapur. The average Hidesign airport store generates roughly twice the turnover of an average mall store, while its smaller footprint pushes sales per square foot even higher.
A key reason is the skew in merchandise mix towards gifting.
Around 40% of the products sold in Hidesign’s airport stores are gifts. “If you have a product which can be gifted, can be purchased quickly and is work-oriented, you’ve covered most of the problematic variables.”
An overwhelming majority of domestic air travellers are men, who may not spend two hours browsing a mall, but can quickly buy a premium handbag for someone back home. Time is their scarcest resource, not money.
“Those are breaks (from routine). These are things that they would normally not have time to do,” adds Forest Essentials executive director Samrath Bedi on why premium skincare too commands attention in an airport environment.
But categories such as perfumes, cosmetics, watches, sunglasses, travel accessories and bags have an obvious advantage – they can be bought quickly and generally don’t require fitting rooms or extensive trial. As Pravat Paikray, VP-Commercial, Bangalore International Airport, says, these “one-size-fits-all” categories perform well.
Right-Sizing
Apparel, jewellery and other categories involving multiple sizes, fits or lengthy considerations have a harder job.
“Standalone apparel and niche lifestyle stores would typically be loss-making,” says founder, Third Eyesight, Devangshu Dutta.
Shriram believes even these categories are being held back by conventional merchandising assumptions. He points out that a business traveller does not necessarily need another blazer simply because they are at an airport. What they may need is a pair of track pants for an overnight trip, a gift for someone at home, or a product they discover while waiting for a flight.
For instance, Ramraj Cotton’s proposition works partly because of its local-brand resonance and partly because of its gifting-driven merchandising. “There are a lot of combos which work very well for gifting,” says Radhakrishnan. He says passengers are usually concerned about weight restrictions, so the store even repackages the items as per requirement. The brand declined Brand Equity’s interview request.
Airport merchandise can carry a 20-40% premium, he says, because the customer is paying partly for convenience. The traveller does not necessarily want to step out into the city just to save a few hundred rupees.
Front of the Queue
Paikray says Bengaluru airport explicitly designs its retail proposition around this time constraint. Brands are expected to adapt their store design, assortment, staffing, service and operations rather than simply transplanting their city format. “If a brand has 100 stores, don’t come and open 101st store in an airport, ” he says.
For Forest Essentials, what changes is also the reason the consumer is being shown the product, says Bedi. Hydration for flying, sleep on long journeys, stress relief, gifting, replenishment, etc. “It’s just about how you angle it.”
Bengaluru airport is also lowering the barriers for brands to test the market by using pop-up stores to let newer brands test travel retail without committing to long-term contracts.
Paikray says challenger and D2C brands are increasingly considering airports earlier in their expansion journeys.
But the opportunity is not on auto-pilot. Only those who adapt can turn the minutes before boarding into something more valuable than visibility – a sale.
(Published in ET Brand Equity)
admin
September 1, 2026
Vikash Tripathi, Outlook Business
1 September 2026
Eight decades ago, the ‘nationalist businessman’ GD Birla helped prepare the ‘Bombay Plan’, which asked the state to pro-vide for the bare minimum needs of its people. His plan asked for 2,800 calories of well-balanced food per day, 30 yards of clothing per year and 100sq ft of housing per person.
Today, seventh-generation Aryaman Vikram Birla is betting on an entirely different opportunity: premium dining. “We continue to believe in the remarkable potential of the premium casual dining space, spurred by rising disposable income and evolving lifestyles,” the 29-year-old said after Aditya Birla New Age Hospitality acquired KA Hospitality in 2023.
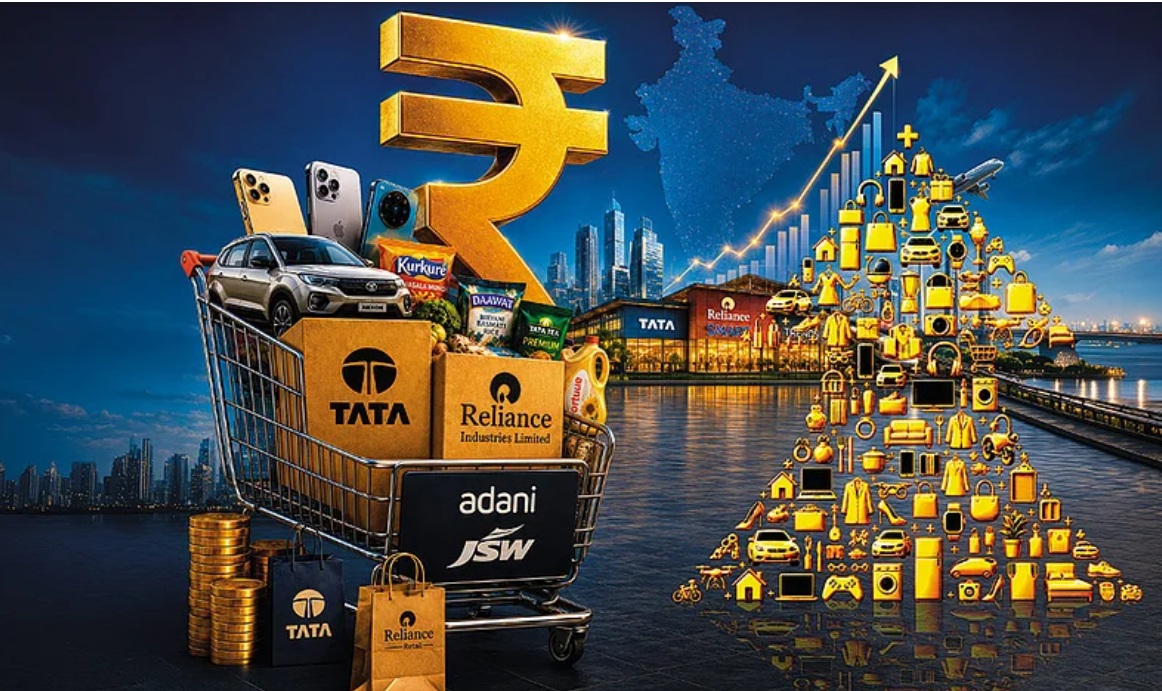
The Birlas are not alone in trying to cash-in on rising prosperity in India. In the past five years alone, India’s top 10 industrial groups have announced new ventures in consumer-facing sectors or doubled down on existing ones. A rough tally of these investments crosses ₹4.8 lakh crore.
For decades, these same business houses built their dominance in core sectors like steel, power, aluminium, cement and chemicals, laying the industrial backbone of the economy. This helped the nation become a large producer of such goods and, in some cases, an exporter as well.
But as India’s economic conditions changed, so has the focus of its largest conglomerates.
For the likes of Tata, Aditya Birla, Bajaj and Bharti, that journey started way back. “What has changed in recent years is the speed and openness of the amount of capital being invested,” says Jitender Kumar, associate professor and programme chairperson, retail management programme at Birla Institute of Management Technology.
“It is not ‘opportunistic’ reasons, it’s structural reasons.”
Two factors seem to be driving the shift: the first is the arrival of an affluent consuming class that can buy branded and premium goods, and the second is the attraction of consumer businesses as a way to diversify revenue and, in some cases, improve the quality of earnings.
The Rise of Affluence
A couple of decades ago, if an Indian household had some extra cash, it often meant buying more of the same. Today, it increasingly means buying better. Even salt is being upgraded, from iodised to Himalayan pink or rock salt. The same shift is visible in bigger purchases: sports utility vehicles (SUVs) over hatchbacks, and ₹1cr-plus homes over budget flats.
But India isn’t simply consuming more. It is moving from basic consumption towards discretionary, branded and premium consumption. This boom is most clearly seen in the rapid expansion of the financial infrastructure that enables consumption. Formal retail credit penetration has more than doubled over the past decade, according to a TransUnion Cibil report, driven largely by personal loans, credit cards and consumer durable loans. Meanwhile, the government-backed Unified Payments Interface has untethered spending from the cash in a buyer’s wallet.
The signs show up across the broader consumption economy. Homes priced above ₹1cr accounted for 54% of total sales in 2025, up from just 30% in 2023—the market that decorative paints and home solutions are chasing.
Out of 4.7mn cars sold in the financial year 2025–26, SUVs accounted for more than half.
“The consumer market has grown substantially—not only through rising incomes but also the dramatic expansion of branded consumption across product verticals,” says Devangshu Dutta, founder of management-consulting firm Third Eyesight.
The bets are also getting more varied, from Reliance Retail tying up with global brands like Fenty and Skims to the Bharti Group bringing Olive Garden to India.
The Lure of Returns
For a passenger walking through an airport, the flight is only one part of the journey. There is coffee before boarding, food between flights, a lounge, retail outlets, parking and a host of other things to spend money on. For Adani Airports, those non-aero businesses are increasingly becoming the more lucrative part.
Its non-aero operations already generate about ₹2,500cr, with returns in the high-20% range, against roughly 12% from regulated aeronautical operations.
Jeet Adani, director of Adani Airport Holdings, expects the share of aeronautical revenue to fall to around 10% of total revenue, with non-aero becoming the bigger growth driver. The motivation can be seen as an escape from a return ceiling as much as a bet on rising affluence.
As Kumar puts it, consumer businesses help the conglomerates in two major ways. First, they help insulate them from volatile and often punishing commodity cycles, and second, they often offer far better returns with lower capital intensity and faster cash conversion.
Reliance Industries (RIL) shows how significant that shift can become. By 2025–26, its consumer-facing arms, Jio Platforms, Reliance Retail Ventures and Reliance Consumer Products, together contributed over 40% of group revenue and nearly 60% of operating profit.
And there is another advantage. “A small business, when it wants to build a new venture, faces constant margin pressure and often has to build its supply chain from scratch. A large conglomerate can leverage its existing scale, infrastructure and supply chain to enter a new business far more efficiently,” explains Kranthi Bathini, equity strategist at WealthMills Securities.
Different Strokes
In chasing consumers, some conglomerates are following the fastest-growing categories, while others are using their existing industrial capabilities to enter consumer-facing businesses. One is trying to build an entire ecosystem around it. But the lines between these approaches are not always clean.
Tatas is doing both: building entirely new consumer brands while also using the industrial ecosystem it has built over decades.
For Tatas, the consumer opportunity has largely been about following where spending is moving. Their consumer ventures have followed this arc longest. It began decades ago with Lakmé (1952), Tata Tea (1962) and Titan (1984). Tanishq and the expansion of Trent under brands such as Zudio are only the latest examples.
At Tata Consumer Products, once largely a staples business built around salt, tea and pulses, the focus has been shifting towards value-added foods and beverages, with ₹7,000cr spent on the acquisitions of Capital Foods and Organic India in 2024. Across companies such as Tata Digital, Indian Hotels, Air India and Tata Motors Passenger Vehicles, the group has announced close to ₹93,180cr in investment over the past five years.
Aditya Birla’s jewellery chain Indriya and its move into premium hospitality belong to the same category of ‘pull-based’ diversification.
JSW is taking a different route. It is taking its existing industrial strengths one step closer to the buyer. The group, which has traditionally been focused on areas such as steel, energy and cement, has expanded into consumer-facing areas such as auto, paints and home solutions.
It launched JSW Paints in 2019, and acquired a controlling stake in paintmaker AkzoNobel India for ₹8,986cr last year. Its strategy is to leverage an established network of contractors, dealers, architects and builders to reach consumers.
The same strategy can be seen in its push into autos, acquiring a 35% stake in the Indian unit of China’s MG Motor in 2024, leveraging synergies with its established steel business.
At Tatas, too, group companies like Tata Steel, Tata Power, Tata AutoComp, Tata Technologies and TCS are doing significant businesses with Tata Motors.
Adani is also using an asset it already controls to move further into the consumer’s wallet. Adani Airports announced a ₹20,000cr investment in June to develop hotels, retail, entertainment and commercial infrastructure around its eight airports, and has signed hotel management agreements with IHG Hotels & Resorts for five hotels. City-side developments could contribute 30–40% of Adani Airport Holdings’ non-aero revenue.
Yet another example of the extension strategy is Aditya Birla Group’s attempt to diversify from cement, metals and textiles into decorative paints with Birla Opus.
RIL took a different approach: trying to connect multiple consumer businesses into one ecosystem. It expanded its retail network through new formats and acquisitions, added brands and partnerships, and then built a consumer-goods business around acquisitions such as Campa Cola and Lotus Chocolate.
That expansion was helped by billions of dollars raised by both Jio Infocomm and Retail Ventures from foreign investors in 2020. The group now plans to spend another ₹8,000cr expanding consumer goods manufacturing. The advantage of having that kind of scale is clear. If RIL has Ajio at a mall and, next to it, GAP and Herschel, it can negotiate better rental terms.
For conglomerates, Kumar points out, the next level of competition will not be based on investment, “but on the ability to create different consumer experiences, foster innovation and create lasting brand loyalty through the integration of these capabilities”.
Can Scale Win?
When Reliance Fresh opened its first stores in 2006, it was part of a rush by some of India’s biggest business groups to crack organised retail. Aditya Birla Group, RP-Sanjiv Goenka Group’s Spencer’s and Kishore Biyani’s Future Group were all betting that organised retail could transform the way Indians shopped. What followed was years of experimentation, losses and, for some, eventual retreat.
Birlas essentially gave up on grocery retail after a decade of heavy losses and exited entirely.
Future was pushed into insolvency after a controversial ₹24,713cr deal with RIL. Spencer’s is still trying to find its footing, with ₹249.33cr in net losses in 2025–26.
Conglomerates may have deeper pockets, but that does not automatically make them better at selling to consumers. India has seen some of those bets fail or take years to work. And even among today’s biggest players, the results are still mixed.
Tata Sons has been in this segment longer than the Ambanis, yet its consumer businesses still make up less than 40% of its total revenue —a share that has not changed since 2020.
These groups have what most standalone consumer companies don’t: capital, distribution, infrastructure, brands, scale.
But winning consumers takes something else entirely—reading what people want, building brands, innovating fast and earning loyalty.
“In B2B [business to business], it’s about manufacturing at scale, getting your costs down. Then you can compete. In B2C [business to consumer], it’s all about the product. With the right product at the right price, you have a chance to win in the market,” Parth Jindal, managing director of JSW Cement and JSW Paints, told Outlook Business in 2025.
Tata Sons’ chairman N Chandrasekaran hit the same wall while revamping the group’s consumer unit. “I have the money. But I don’t have the team to run it,” he had told Sunil D’Souza while hiring him to lead Tata Consumer Products in 2020.
Reliance and Tatas have had the longest head start, but even their journeys show how difficult it is to turn scale and capital into consumer businesses. Birla, JSW and Adani are now trying to make that transition in their own ways.
A longer tail—Bajaj in hospitals, L&T in retail finance and education, Mahindra in insurance and hospitality, Murugappa in electric mobility—is playing it safer, going deeper into what it already owns rather than chasing new categories.
What ties them together is a bet on consumers buying not just more but better, and on those consumers being worth more per rupee of capital than the industrial customers who built these houses.
The prize is growing, but so is the competition. Capital and scale may get these conglomerates through the door. They won’t guarantee a seat at the table.
(Published in Outlook Business)
admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
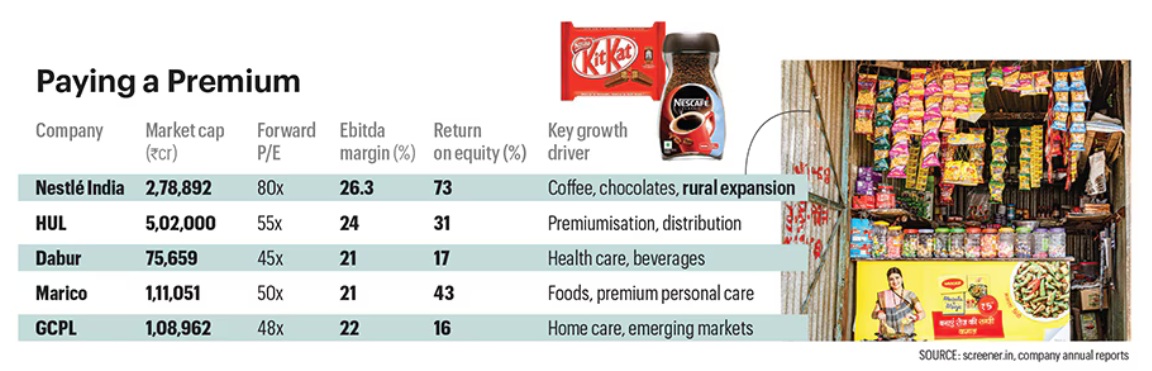
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
admin
July 13, 2026
Sowmya Ramasubramanian, Vaeshnavi Kasthuril (MINT)
Bengaluru, 13 July 2026
India’s vertical quick-commerce startups across categories like baby care, medicines and fashion, backed by venture capital heavyweights, are beginning to redefine what “quick” means.
For some, the race is no longer about cutting delivery times by a few more minutes. Instead, founders are increasingly talking about better assortment, sharper curation, stronger supply chains and healthier unit economics as the factors that will decide whether the model survives.
Baby care platform Ozi, backed by Blume Ventures and RTP Global, has settled on a roughly 60-minute delivery promise. Founder Amit Sah told Mint the company would rather optimise for “quality selection” than chase ultra-fast deliveries, arguing that customers today are looking for reliable availability and curated choices rather than insisting on receiving products in 10 minutes.
Lightspeed-backed fashion startup Slikk is pursuing a similar path. Founder Akshay Gulati said the company’s focus since inception has been building a wide catalogue rather than aggressively acquiring users.
The shift comes as the sector enters a more pragmatic phase. Quick fashion startup Blip shut down within a year of launch last June, while rival Klydo has recently pivoted its business model, raising questions about the viability of firms in every category.
The crop of vertical quick commerce startups—focused on rapid delivery within a single, specific product category—has largely emerged over the past two years, inspired by the explosive growth of grocery-focused pioneers such as Blinkit, Swiggy Instamart and IPO-bound Zepto, which have accustomed consumers to receiving groceries and everyday essentials within minutes.
Other prominent startups include Plazza for quick delivery of medicines, Instafix for mobile repairs within minutes, and Dazzl for at-home salon services.
Kalaari Capital noted in its 2025 report that quick commerce had already captured about two-thirds of online grocery orders and around 10% of India’s overall e-retail spending in 2024, transforming consumer behaviour and building the infrastructure for specialised vertical players to emerge.
“Speed was never a real moat but became a hygiene factor once every significant player could promise 10-30 minute delivery,” said Devangshu Dutta, founder and chief executive of consultancy Third Eyesight. “Assortment depth, availability, trust, and sustained price-value have been, and will remain, the true differentiation levers. For categories such as medicines and baby products, credibility and compliance outweigh saved minutes, apart from urgent purchases.”
“Unit economics can become healthier only where there’s a clear reason for frequent and repeated purchases. Groceries and medicines are repeat, low consideration categories, while fashion is high consideration, driven by fit, styling and browsing. The best quick commerce categories have low or no returns and high order frequency, whereas rapid fashion delivery faces high return rates due to product mismatch against customer expectations (sizing, fit, fabric and colour),” Dutta said.
Different categories, different playbooks
While fashion startups are investing heavily in discovery and inventory refreshes, Ozi believes the opportunity in baby care lies in curation and premiumisation.
Sah said each sub-category within baby care presents a different operational challenge. Consumables require deep availability of long-tail brands, while fashion depends on filtering products for quality rather than listing everything available. Ozi, which delivers wipes, diapers, and baby food, deliberately curates brands instead of maximising assortment, targeting parents willing to pay slightly more for trusted products.
“The customer behaviour has shifted from discovery first to search first,” Sah said, adding that shoppers today are not necessarily looking for ultra-fast delivery, but nor are they willing to wait several days. “A modern-age customer values quality. They are happy to pay an 8-10% or 12% differential, but they need quicker access to better brands and better assortment.”
Fashion startups argue that their challenge is different altogether.
Gulati said Slikk has built its business around supply rather than customer acquisition, claiming that stronger assortment has helped steadily reduce acquisition costs. The company replaces 30-40% of inventory in every dark store each month and is expanding neighbourhood by neighbourhood instead of spreading rapidly across cities.
Slikk might also consider introducing private brands for apparel, given their higher margins, Gulati said.
Bengaluru-based fast-fashion e-commerce startup Knot, which raised $5 million from 12 Flags and Kae Capital in December 2025, is investing heavily in back-end technology. Its app captures user preferences through swipe-based interactions, while its dark stores carry much wider assortments than horizontal quick commerce operators – offering a vast, multi-category collection of goods – and customise inventory based on local demand.
“We look at fashion as a data science problem and not really an intuition problem,” co-founder and chief executive officer (CEO) Archit Nanda said.
Nanda said fashion’s long-tail nature—which relies on selling small quantities of several unique products rather than depending on a few popular items – means inventory commonality across dark stores is significantly lower than grocery, requiring specialised supply chains and hyperlocal merchandising.
The profitability test
The changing strategies also reflect growing investor scrutiny of unit economics.
Slikk’s Gulati said investors continue to back the category but increasingly want proof that businesses can balance growth with profitability rather than relying on heavy customer acquisition spending. He believes execution in neighbourhood-level operations, assortment and brand partnerships will ultimately determine the winner.
Knot’s Nanda said that fashion combines high average order values with healthy margins, making the category attractive despite its complexity.
However, analysts believe that not every vertical is equally suited to the model.
“Looking ahead, horizontal cross-subsidy will work better, with established, well-capitalised players (Myntra’s M-Now, Nykaa Now) including quick delivery into an existing catalogue and logistics network rather than building it standalone. For narrow, high-trust verticals (medicines, baby care) where the value is availability and authenticity rather than impulse, and where margins can support the delivery cost, quick commerce can work,” Dutta noted.
Kalaari Capital’s 2025 report on vertical quick commerce similarly argued that specialised players will win by solving category-specific pain points, with assortment depth, customer experience, and category expertise emerging as key differentiators.
(Published in MINT)
