admin
August 28, 2026
Sowmya Ramasubramanian, MINT
28 Aug 2026
Quick commerce is here to stay, according to FirstCry managing director and chief executive Supam Maheshwari. He added, however, that the economics will increasingly favour large retailers with established stores, logistics networks, and private labels over niche platforms building from scratch.
“There will be fatalities in this space,” Maheshwari told Mint, referring to specialty quick-commerce platforms. He explained that these platforms face a difficult path to profitability due to high logistics, inventory, working capital, and customer-acquisition costs.
FirstCry (Brainbees Solutions Limited) has developed its own logistics arm, RocketBees, along with FirstCry Qwik, which provides two-to-three-hour delivery in select pin codes. RocketBees, launched in mid-2025, now operates across 72 cities and improved its delivery turnaround by around 20% between launch and the first quarter of FY27. Qwik, launched in December 2025, has expanded to 12 cities and delivered about 125,000 shipments in June, Maheshwari said.
Rather than tracking Qwik’s expansion by city count, FirstCry is targeting about 10% of its online orders through the service over the next few quarters. The model will leverage the company’s existing store network where possible, with dedicated dark stores in select catchments.
Qwik will operate alongside FirstCry’s standard e-commerce offering, providing faster delivery for a narrower local assortment, while the broader catalogue remains available through same-day and next-day delivery.
This strategy comes as FirstCry tries to regain operating leverage after a period of margin pressure. Consolidated revenue rose 13% year-on-year to ₹2,106 crore in Q1FY27, even as adjusted Ebitda declined to ₹89.3 crore from ₹92.7 crore a year earlier, squeezing the margin to 4.2% from 5%. While India multi-channel revenue grew 17.7%, its adjusted Ebitda margin shrank to 5.7% from 8.6%.
Maheshwari’s remarks also coincide with sustained investor interest in vertical quick-commerce platforms focused on the mother-and-baby and kids categories. Kids-focused OZi secured $6.2 million from RTP Global in March, while babycare platform Peeko raised over $7 million in a round led by Chiratae Ventures earlier this month.
Quick commerce edge
Maheshwari said FirstCry isn’t aiming to replicate the standard quick-commerce model. Niche platforms, he noted, lack the scale needed to absorb logistics and supply-chain costs, leaving them more exposed to inventory and working-capital demands. Their reliance on third-party brands also restricts their ability to protect margins.
“If you put all of this together, it just becomes unsustainable in my view,” Maheshwari said, arguing that niche-category quick commerce could take many years and hundreds of millions of dollars to become profitable. In contrast, FirstCry generates over half its gross merchandise value (GMV) from in-house brands and operates a national logistics network, creating what he described as a different economic equation.
FirstCry has more than two million stock keeping units (SKUs), and Qwik can offer products beyond emergency purchases such as diapers or formula, including partywear, ethnicwear, strollers, walkers and tricycles, he added.
Maheshwari also said he does not expect delivery speed to cannibalize FirstCry’s core business. “A lot of mothers are planned shoppers. When they are buying fashion, nursery products or other categories, they do research, they look at the brand and quality. They don’t necessarily need the product in 10 minutes.”
That distinction is reflected in FirstCry’s approach to physical stores. The company has spent the past two quarters changing its offline assortment strategy, moving from an e-commerce-led approach focused on product width to a retail model focused more heavily on depth. Maheshwari said this allows the company to secure better costs, offer better prices, and improve footfall and conversion.
FirstCry plans to add around 90-100 stores in FY27, and Maheshwari expects an even larger number in FY28. The expansion is not being driven by Qwik, he said, although stores in cities where Qwik operates can also be used to fulfill quick-commerce orders.
The offline push is aimed at increasing wallet share in markets where FirstCry doesn’t have stores yet. Maheshwari said 36% of GMV from the top 50 cities in FY26 came from customers who transacted both online and offline.
“Assortment depth, availability, trust, and sustained price-value have been, and will remain, the true differentiation levers. For categories such as medicines and baby products, credibility and compliance outweigh saved minutes, apart from urgent purchases,” Devangshu Dutta, founder of consultancy Third Eyesight, told Mint last month.
Private labels and margins
Home brands accounted for more than 58% of GMV in FY26, up from 37% in FY20, and Maheshwari expects that trajectory to continue. FirstCry’s portfolio includes Babyhug, BabyOasis, CuteWalk and Pine Kids, alongside third-party brands.
“The trust is first with FirstCry as a retail platform and then with the home brands. That is why our curation is so important. We are offering a superior experience through the home brands we have been building,” Maheshwari said. Rather than viewing this curation simply as a lever for higher gross margins, he considers it a key competitive advantage spanning FirstCry’s physical stores, e-commerce platform, and quick-commerce service.
FirstCry’s consolidated gross margin fell to 36.5% in Q1FY27 from 38.5% a year earlier, while India multi-channel adjusted Ebitda margin fell to 5.7%. Maheshwari attributed the pressure primarily to aggressive competition in diapers and higher raw-material costs, which affected FirstCry’s manufacturing business.
He expects the raw-material impact to be fully reflected in pricing by Q3, while diapers could take another two to four quarters to normalise. “This is only a 15% category for us,” he said, noting that the remaining 85% of the portfolio—fashion, baby gear, nursery and toys—continues to perform strongly. He said he expects margins to recover through FY27 and that the company’s longer-term margin trajectory remains upward.
Brainbees Solutions stock was trading around ₹186 at 1 pm on Friday, down around 1.35% on the day. The stock is down more than 72% since it was listed in August 2024.
(Published in MINT)
admin
August 26, 2026
Praveen Paramasivam, Reuters
26 August 2026
India’s Tilaknagar Industries, is open to another large deal after its nearly $500 million purchase of the Imperial Blue whisky brand from Pernod Ricard, a top executive said, as consolidation gathers pace in India’s liquor market. Deals, including United Spirits’ purchase of Nao Spirits and Sazerac’s stake in John Distilleries, underscore growing investor interest in India’s spirits industry as liquor makers seek to broaden portfolios and gain scale.
“Definitely we will” consider another deal on that scale if the right opportunity emerges, Chairman and Managing Director Amit Dahanukar said. “Before Imperial Blue, I would have never given a target number which had two times our revenue.”
The maker of Mansion House brandy is open to any spirits category on acquisitions, Dahanukar said. “From an M&A perspective, we remain focused on the craft spirits space within the high-growth super premium and luxury segments,” he added.
Dahanukar did not disclose how much the company had set aside for potential deals. He said Tilaknagar would be “disciplined” in financing future acquisitions, citing the mix of debt and equity used for the Imperial Blue purchase.
The Imperial Blue acquisition has already transformed Tilaknagar’s scale. Revenue nearly tripled to 10.26 billion Indian rupees ($107.46 million) in the first quarter ended June 30, with the whisky brand accounting for nearly two-thirds of total sales volume.
Industry fragmentation and state-level regulations make it difficult for liquor makers to build national scale, creating incentives for consolidation, said Devangshu Dutta, founder of retail consultancy Third Eyesight.
India is expected to become the world’s largest spirits market by volume by 2032, surpassing China as millions of consumers reach legal drinking age each year, according to alcohol industry data provider IWSR. ($1 = 95.4800 Indian rupees)
Reporting by Praveen Paramasivam in Chennai; Editing by Dhanya Skariachan and Anil D’Silva
(Published on Reuters)
admin
July 20, 2026
Kartikay Kashyap, Financial Express / Brandwagon
30 July 2026
Wendy’s first foray into India’s quick service restaurant (QSR) market in 2015 remained a non-starter. Sierra Nevada Restaurants, the then master franchisee, could not scale its retail presence beyond four conventional restaurants concentrated largely in Delhi-NCR. This limited physical availability, brand awareness and ordering frequency.
Ten years on and under a new master franchisee Rebel Foods since 2023, Wendy’s seems to have turned over a new leaf. With more than 250 stores, and ₹200 crore in revenues, the brand wants to be the one-stop destination for the younger generation where consumers come together to celebrate food, music and a sense of community. “The longer-term ambition is to expand to approximately 500 locations by 2028 through a combination of delivery kitchens and physical restaurants,” says Joy Bamania, brand head, Wendy’s India.
As a first step, Rebel Foods recently opened what it calls its “dynamic cultural flagship store” in Delhi’s vibrant student hub of Hudson Lane, GTB Nagar. The two-level youth-centric space blends food, music and anime, offering fans experiences like live rap battles, meet-and-greets, and specialised menu items like the signature Teriyaki Burger range.
“It has been designed to be livelier, more youthful and visually engaging—an Instagram-worthy space. It is a physical expression of how we want consumers to experience Wendy’s in India: bold, fun, culturally relevant and full of energy,” says Bamania.
Even before taking over Wendy’s operations Rebel Foods had been managing its delivery-only cloud kitchens since 2020 and was familiar with the brand’s DNA and what was required to mount a serious challenge in the ₹15,000-plus crore organised burger restaurants market in the country. The low capex delivery-only model has helped to improve its gross margins, but taking on established brands like McDonalds, KFC and Burger King would be a completely new ball game.
Is the latecomer up to a second bout in the ring?
New, improved
Wendy’s has at least three things going against it. It arrived late on India’s shores and couldn’t really stand apart during its last outing. “No matter how big a global brand you are, you need to stand out in the clutter,” says Devangshu Dutta, founder & CEO, Third Eyesight.
So while McDonald’s is the kid-first family restaurant, Burger King is intentionally “imperfect” and rides on humour, pop-culture moments, and viral marketing. Wendy’s, say experts, had no differentiation than just being a global brand.
Its premium pricing was another bugbear. In its first foray, Wendy’s tried to justify its higher prices saying its ingredients were better than that offered by the rest of the pack. So while the price of a Wendy’s entry level burger was ₹100, McDonald’s retailed one at half that price. “In the QSR business, you have to get your price right. There is nothing ‘premium’ in that space,” says Ankur Bisen, senior partner, The Knowledge Company. Rebel Foods addressed these problems with four fundamental shifts.
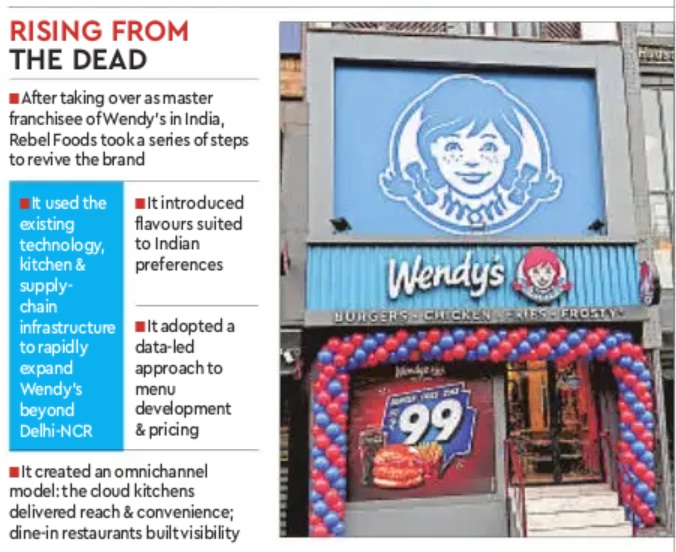
First, it used the existing technology, kitchen and supply-chain infrastructure to rapidly expand Wendy’s beyond Delhi-NCR. Second, it built a stronger and more accessible value architecture while introducing flavours suited to Indian preferences. Third, it created an omnichannel model in which cloud kitchens delivered reach and convenience, while selected dine-in restaurants built visibility and deeper brand experiences. Finally, it adopted a data-led approach to menu development, pricing, consumer feedback and operational performance.
Rebel Foods became Wendy’s master franchisee in India in 2023. At that stage, Wendy’s had approximately 90 locations across 19 cities. By March 2025, the brand had reached 200 locations across more than 50 cities, including 15 dine-in restaurants.
“The fivefold revenue growth has consequently not come from one product or campaign. It is the result of wider distribution, sharper value, continuous menu innovation, stronger operational execution and a much clearer proposition for the Indian consumer,” says Bamania.
(Published in Financial Express)
admin
July 12, 2026
Nivedita Mookerji, Business Standard
12 Jul 2026
Recently, fast moving consumer goods distributors posed some existential questions to the government: Have the rules changed for foreign-owned ecommerce firms? With that, the All India Consumer Products Distribution Federation made a plea to the government to examine if foreign-funded ecommerce and quick commerce players can run inventory-led businesses through warehouses and dark stores.
The question mark is around the operating model of the big daddies of retail — both from America — under the current foreign direct investment (FDI) guidelines. One of them is Bentonville-headquartered Walmart, which holds a controlling stake in e-commerce major Flipkart. And the other is Seattle-based Amazon. Both Flipkart and Amazon are upping their quick commerce play, a development that the Indian retail ecosystem players fear would hit them hard.
For context, foreign e-commerce companies are allowed to do business through the marketplace model as opposed to the inventory-led format. Marketplace operators such as Amazon and Flipkart (Walmart) are permitted to have sellers on their platforms and those sellers own the goods (inventory) which are sold to customers. Indian companies in the e-commerce business can own the goods and sell them directly to the consumers.
This is not the first time that there’s noise around the business practices of foreign majors and their alleged violations of the rulebook in relation to anything from the legality of the operating model to predatory pricing and deep discounting. The protests of the domestic traders against foreign players — that started decades ago with an agitation against the government’s multi-brand retail policy — have resulted in a series of amendments in the FDI rules, intervention of the competition watchdog CCI (Competition Commission of India), Supreme Court observations, making of laws and keeping them in abeyance. But, the complaints — from different quarters of the domestic business — have remained.
Devangshu Dutta, founder and CEO of consulting firm Third Eyesight, argued that since 1996-97, when foreign investment in retail was first banned, governments of different political hues have been walking the regulatory tightrope with respect to foreign investment in retail, whether offline or online. “The government’s caution on retail policy was aimed at protecting domestic interests, though it is arguable whether it was for the small retailer, or the larger corporates who had identified this as a growth sector at the time,’’ Dutta said.
(Published in Business Standard)
admin
July 9, 2026
Neethi Lisa Rojan & Vaeshnavi Kasthuril, MINT
Mumbai/Bengaluru, 8 July 2026
The collapse of the US-Iran peace deal in less than a month has rattled India’s consumer sector, reviving fears that higher oil prices and fresh supply-chain disruptions could squeeze demand just as companies were betting on a broader recovery.
The renewed uncertainty followed US President Donald Trump’s declaration on Wednesday that the peace deal with Iran was effectively over, alongside Washington’s decision to end a sanctions waiver on Iranian energy supplies. The market reaction was swift. The Nifty FMCG Index fell 2.49% on Wednesday, underperforming the broader market as all 15 constituents declined, led by Dabur India, Hindustan Unilever, and Tata Consumer Products, whose shares fell 3-4% each. The benchmark Nifty50 ended 2.12% lower after renewed hostilities in West Asia pushed crude prices higher.
Executives and analysts said companies have little room to respond immediately, leaving them to closely monitor devel opments as risks to costs and consumer spending mount. “I don’t think companies can react on this kind of a short notice,” said Arvind Singhal, chairman of consulting firm The Knowledge Company. “It takes 2-6 months to make any change in your plans and strategy. I think right now the Indian FMCG (fast moving consumer goods) companies will be watching the progress of monsoon more carefully than the Strait of Hormuz.”
Even after the US-Iran peace deal took effect on 18 June, consumer companies were unlikely to have expected immediate relief, analysts said.
“While everyone hoped for a cessation in hostilities, smart management teams would work on the realistic expectation that even with a ceasefire, pent-up supply chain input costs need to be absorbed over time, and pricing plans must be factored accordingly,” Devangshu Dutta, founder and chief executive of consulting firm Third Eyesight, said.
“Given that the conflict zone is active, I don’t think there is any immediate likelihood of pricing freeze or reductions, even though demand in rural areas as well as in lower-income urban segments is likely to be hit from both sides ― earnings and expenses.”
Large consumer goods companies including Dabur, Emami and Godrej Consumer had recently told investors they remained confident about consumer demand, including in rural markets.
But the renewed rise in crude prices, coupled with erratic monsoons marked by rainfall deficit in some regions and flooding in others, threatens to complicate that outlook. Higher fuel costs could lift prices of crude-linked raw materials such as plastic packaging and ingredients used in soaps and creams, while persistent inflation could push consumers to cut discretionary apne ding and trade down even on staples.
Major consumer companies had already raised prices or reduced grammage across packaged food, beverages and personal care products in the March quarter.
“As far as the crude prices are concerned, that is probably the only variable where the government has to decide as far as pricing of crude or the petroleum in India is concerned,” Singhal said.
That comes at an awkward time for India’s largest consumer companies, including Hindustan Unilever, which had earlier this year told analysts they intended to drive growth through higher volumes rather than price increases. A renewed bout of inflation could undermine that strategy.
(Published in MINT)
