admin
November 3, 2026
Pritha Pahari, The Core
3 November 2026
India’s packaged food and soap makers are running out of easy choices. Input costs have continued to rise since late February, when the Middle East conflict began disrupting supply chains and pushing up crude-linked costs.
A visible price hike, however, risks sending shoppers to a rival. To offset this, companies have reduced package sizes. However, scope for how much these packs can be reduced is limited, especially for products already sold at low price points. Take the example of a Rs 10 pack of Parle-G biscuits.
At this price, there is little room to reduce the quantity further without risking consumer dissatisfaction. Cutting the pack size could make the product less attractive, while increasing the price may discourage price-sensitive buyers.
India’s FMCG giants have squeezed pack sizes about as far as they can go. With input costs still climbing and shoppers watching every rupee, the choice between eating the cost and raising prices is coming, likely right after Diwali.
The Hikes Are In
Britannia, Hindustan Unilever (HUL), Dabur and Godrej Consumer had already raised prices by around 2-5% in the June quarter, and were weighing more for the September quarter. FMCG companies have continued to raise prices to offset higher input costs.
FMCG companies have continued to raise prices to offset higher input costs.
Tata Consumer Products increased tea prices by 8-10% between the June and September quarters, while it raised the price of its Rs 30 salt pack to Rs 32 in May and again to Rs 34 in October.
Hindustan Unilever also took price increases of around 7.5% during the September quarter, according to media reports.
Godrej Consumer Products said it would continue calibrated price increases, particularly in soaps and liquid detergents, to manage cost pressures.
Dabur has also confirmed taking pricing actions in its October business update, while Britannia had indicated a further 1.5-2% increase, largely through smaller packs. However, the latter two companies’ September-quarter results were still awaited.
Experts said that lower-income households face greater pressure because everyday essentials take up a larger share of their budgets. Affordable products such as biscuits, noodles, soaps, detergents and cooking oils are particularly sensitive to price changes.
According to experts, some manufacturers are weighing selective price increases after Diwali, possibly from December.
Shoppers haven’t walked away yet
So far, demand is holding up. Nestlé India’s sales rose 20.5 per cent to Rs 6,782 crore in the September quarter, with double-digit volume growth.
At HUL, June-quarter underlying sales growth of 10 per cent came equally from volume and price.
The market is still nervous.
Nestlé India shares closed 7.7% lower on results day after management flagged rising input costs, especially packaging, edible oils and farm commodities.
Business Standard quoted chairman Manish Tiwary as saying, “Rising inflation, particularly food inflation, is a reality.”
India’s FMCG volume growth remains mixed, although several companies continue to report resilient demand. Tata Consumer Products’ India branded volume growth eased from 16% in Q4 FY26 to 13% in Q1 FY27 and 11% in Q2 FY27.
Marico reported that India volume growth reached near double digits in Q2 FY27, following 11% in Q1.
Dabur India recorded 5% underlying volume growth in Q1 FY27, while its October update indicated double-digit revenue growth for Q2 but did not disclose a confirmed volume figure.
Overall, demand remains resilient, but revenue growth should not be confused with volume growth, particularly as companies raise prices to offset higher input costs.
Why Smaller Packs?
Satish Meena, founder of research firm Datum Intelligence, said that companies try to absorb costs first. “They can do it for one quarter, they can do it for two quarters, but at a certain point they have to pass it on to the customer,” he said. He expects much of that to happen after the festive season.
Discounts are not an option either, since margins are thin. That leaves pack sizes. “Instead of 150 grams, we are doing 120 grams, keeping the price the same,” Meena said, describing the move.
A visible price rise carries a risk of its own.
“Your positioning in the shop will change, and customers will also perceive you as an expensive product and look for other brands,” he said. Once a rival takes the shelf space, it is hard to win it back.
Devangshu Dutta, founder of research firm Third Eyesight, says price points are hard to move. “Price points are often anchored either in the consumer’s mind or by competitive benchmark pricing, making them difficult to change,” he said.
He also said the practice now carries a reputation risk. “The shrinkflation phenomenon isn’t new, but social media has given it viral visibility, which can potentially damage brand reputation.”
Pricing Pecking Order
Meena said companies will follow a set order. First they improve buying and supply chains, then trim ad spending. Next they raise prices on premium products, where buyers are more willing to pay. Raising prices across all products comes last, so they don’t lose share.
Dutta says companies are “caught in a vice” because input costs are rising while core shoppers are cautious about spending. Companies have “no option but to cut brand-level advertising and also review overheads deeply.”
Indian FMCG companies are facing rising input costs across several product categories.
In October 2026, plastic packaging costs were reported to have increased by 30–40%, putting pressure on snack makers and household-product manufacturers.
Palm oil prices rose 21% year-on-year in September, while sunflower oil increased 14%, soybean oil 9% and mustard oil 8%.
Sugar prices climbed 18% year-on-year, adding pressure on confectionery and packaged-food producers.
Tea prices rose 10% over the same period. Coffee and cocoa also recorded increases, with Arabica coffee up 19% quarter-on-quarter and cocoa rising 48%. These increases affect biscuits, noodles, chocolates, soaps, shampoos and detergents differently.
Now What?
The next test is HUL’s September-quarter results, due after its board meets on 28 October. Meena does not expect much to change in the next one to two quarters.
He says the pressure is not seasonal. “It’s because of the war happening in the Middle East… it’s a much longer issue for them,” and he points to RBI data showing some impact on demand.
Input-cost pressures could persist into early 2027.
S&P Global’s September outlook projected elevated manufacturing costs through 2027, while October data showed plastic packaging costs 30–40% higher and key polymer prices more than 50% above pre-conflict levels.
Although prices may ease if supply routes improve, these figures suggest FMCG companies could face continued cost pressure over the next two quarters.
Dutta said only a few brands will come through easily. “Few brands or products are able to build longer-term loyalty consistently and whose value to the consumer is stickier than the resistance to price movement.”
For everyone else, the room to raise prices or shrink packs is running out.
(Published in The Core)
admin
October 29, 2026
Pritha Pahari, The Core
29 Oct 2026
When ITC Ltd. launched Aashirvaad in May 2002, it sold one thing — whole wheat flour. The brand now has more than 200 SKUs across staples, spices, fresh foods and frozen foods.
ITC wants to double what Indians spend on Aashirvaad to Rs 20,000 crore in five years. It said growth will come from two places: more premium atta, and new categories around the Indian kitchen. That makes the brand a test of a hard question in packaged food. Can a name built on the purity of an ingredient win in the other segments and break out from its identity built around atta?
Trust in the purity of flour may not translate into trust in ready-to-eat meals, where taste, consistency and repeat purchases matter more. ITC itself has bought brands and built separate ones for some of these jobs.
A Big Target, A Soft Core
Hemant Malik, who runs ITC’s foods division, told PTI the company expects spending on Aashirvaad to double from above Rs 10,000 crore. That figure is what shoppers pay, including taxes and trade margins. It is not ITC’s revenue. The push comes as the core product slows. In the quarter ended June 30, ITC said atta was held back by heat waves, an LPG shortage and low wheat prices.
FMCG-Others revenue rose 12%, or 16% without staples, and dairy, snacks, noodles and frozen snacks each grew more than 20%. Not all of that belongs to Aashirvaad. Snacks, noodles and frozen foods sell under Bingo!, YiPPee! and ITC Master Chef.
The wider backdrop matters too. ITC is trying to rely less on cigarettes, which now face a sharp rise in tax.
Devangshu Dutta, founder of consultancy Third Eyesight, said value-added ready-to-cook and ready-to-eat products earn better gross margins than staples. Selling more of them would also help ITC use its factories more fully, he said.
ITC’s recent annual report shows multigrain atta, vermicelli and besan have grown threefold over five years, and now make up about 16% of the staples portfolio. ITC does not give a brand-level split between premium atta and new categories, or Aashirvaad’s profit.
ITC’s own Q1 FY27 release said atta performance was tempered by transient factors including heat waves, an LPG shortage and benign wheat prices. The FMCG-Others business grew 12% in the quarter.
The Easy Stretch
ITC said its value-added atta variants and staples-related products have grown three-fold in five years, and their share of the portfolio has doubled. They include besan, rava, vermicelli and soya chunks. The newest addition is chana sattu, first sold in Bihar, Jharkhand and West Bengal, with a Rs 10 pack that carries 10 grams of protein.
Suumit Kapoor, a brand growth consultant, calls these safe stretches. Besan and rava barely change what a shopper expects, he said. They are “still about what’s in the bag,” so purity still answers the question.
The Harder Jump
Ready-to-cook and ready-to-eat food asks something different. “Purity is a raw material promise. Ready to eat is a finished experience,” Kapoor said. Nobody buys a packaged curry because the dal was well sourced, he said. They buy it because they are hungry, short of time and hoping it tastes home-cooked.
ITC’s recent launches show it knows this. Its ready-to-cook chapati comes in packs of 10, with no preservatives and a shelf life of five to six days. The chutney and sambar range, launched in June, is made in small batches without preservatives and depends on a cold supply chain.
At launch it was sold only in Bengaluru through quick-commerce apps. The short shelf life answers a real problem.
Dutta said many shoppers prefer freshly cooked, hot meals and are wary of additives that extend shelf life. Cold chains remain patchy even in big cities, he said. A time-pressed household can also cook, order in, eat out or buy a packaged meal, and each choice is judged on price, convenience and taste.
Kapoor added a caution about ITC’s own numbers. They do not show whether shoppers buy the new products because of the Aashirvaad name, or simply because those categories are growing.
ITC’s latest results release names ready-to-cook chapati in a list of products but gives no sales figure for it, or for ready-to-eat meals. That may reflect how ITC groups its figures, not a change in plans.
Why One Name Still Makes Sense
Dutta sees a strong business case for using one name. A familiar brand cuts the cost of getting shoppers to try something new, he said, because Aashirvaad is already in millions of homes. New items can also move through ITC’s existing distribution, including modern trade and quick commerce, and retailers accept extensions from a leading brand more readily than unknown labels.
He also sees a defensive motive. Aashirvaad sits in everyday kitchen use, between ITC’s older gourmet line, Kitchens of India, and its snack-led Sunfeast. A bigger range puts it up against MTR, Haldiram’s and iD Fresh.
Tata Consumer said Tata Sampann grew 69% in Q4 FY26 with strong performance across categories. On the Q1 FY27 earnings call, CEO Sunil D’Souza said the core portfolio of pulses, spices, poha and vermicelli was growing at about 30%, with cold-pressed oils and dry fruits adding to that growth.
Poha and vermicelli are the closest items to convenience foods, but Tata doesn’t separate them out.
AWL Agri Business, which owns Fortune and Kohinoor, reported Q1 FY27 Food & FMCG revenue of Rs 1,726 crore, up 22%, with a segment EBITDA margin of 6%, and management said the Fortune and Kohinoor brands both grew at double-digit rates. AWL’s investor day deck also shows Kohinoor rising from Rs 150 crore in FY23 to over Rs 400 crore in FY26.
Not Betting Only On The Name
ITC’s record suggests it does not rely on one brand for everything.
It launched Kitchens of India in 2001 as a separate premium name, using the dishes of its hotel restaurants. It bought the spices brand Sunrise in 2020. In February 2025, it agreed to buy Prasuma, a frozen and ready-to-cook company, starting with a 43.8% stake. Sproutlife Foods, the Yogabar business, became a subsidiary on April 1.
Mint reported in February 2025, citing two unnamed people, that ITC was in early talks to buy MTR Foods and Eastern Condiments from Norway’s Orkla for about $1.4 billion. Orkla said it does not comment on rumours. ITC did not reply to Mint. No deal followed.
Kapoor reads such moves as ITC buying skills it lacks, not as proof that Aashirvaad cannot stretch.
ITC is also putting weight behind fresh food. Its fresh food business, which includes a brand called ITC Aashirvaad Soul Creations, grew gross order value 90% in the quarter, passed an annual revenue run rate of Rs 300 crore and now runs 75 cloud kitchens in five cities.
What Comes Next
The company’s position is strongest where the brand started. In July, ITC said it had already secured 95% of the wheat of the quality needed for Aashirvaad atta, but it also warned that monsoon rains were short and El Niño could hurt growth.
Value-added atta variants and staples adjacencies have grown three-fold over five years, and Aashirvaad Svasti dairy is among its fastest-growing categories, but neither is a meal category.
The newest meal-type launches, such as ready-to-cook chapatis, frozen naans and parathas, and fresh chutneys and sambar, have no disclosed sales or repeat-purchase data.
ITC launched Aashirvaad ReadyMeals back in 2003 and still describes ready-to-cook as a new bet, and it markets other finished-food lines under separate brands (Kitchens of India, ITC Master Chef, Prasuma), which suggests it doesn’t simply assume the Aashirvaad name carries into every meal category.
Management frames success around product innovation and differentiation, not brand trust alone. The larger test is on the shelf.
Kapoor said staples-linked products can keep drawing on Aashirvaad’s purity, but anything close to a finished meal has to earn a name for taste and consistency. Whether shoppers will pay for that under the Aashirvaad label is what ITC’s Rs 20,000 crore target depends on.
(Published in The Core)
admin
October 7, 2026
Vidya Sathyapriyan, ET Brand Equity
7 October 2026
Every single month, leather-goods brand Hidesign changes the storefront of its airport stores. The reason: “You can’t bore the man or woman who’s coming to the airport every week,” says founder Dilip Kapur.
But then what makes the airport shopper any different from someone walking into a high-street or mall store? Affluent? Sure. Willing to spend? Mostly. Time-poor and seeking convenience? Definitely.
That mix presents a particular challenge for brands: understanding what and why travellers will buy, and how quickly they can buy it.
Some have learnt to make the often lopsided economics work. Others are running an expensive billboard with a billing counter attached.
Crunching Numbers
The economics are punishing.
Airport rents, minimum guarantees, revenue-share, staffing and operating costs can make them significantly more expensive than conventional retail. For example, a good mall in Chennai charges roughly Rs. 350-800 per sq ft monthly in retail rent, compared with Rs. 150-200 per sq. ft. on the high street. Airport rentals can rise to as much as Rs. 6,000 per sq. ft. Similar differentials play out in other major cities.
Yet brands keep signing on because the alternative would be an advertising site with no retail attached. “A hoarding is for all and sundry and 1D,” says S. Shriram, founder of Miles2Go Consulting Services. “In the airport, captive audience, engagement is 3D and sometimes even 4D – touch and feel, trial, buy, and even return elsewhere.”
For deep-pocketed brands, spending on airport visibility can be justified even when store-level profitability is modest or even non-existent. Others gotta move on.
Go Colors, for instance, is rationalising stores at airports where the economics are not working. “The opportunity remains strong, but the location must justify the cost of access to the consumer,” says CMO Vatsal Koolwal. “As a broad benchmark, rentals in the range of 15-20% of revenue can work, provided the rest of the cost structure is managed effectively.”
The right sell
Six of Hidesign’s top-10 stores in India are at airports, says Kapur. The average Hidesign airport store generates roughly twice the turnover of an average mall store, while its smaller footprint pushes sales per square foot even higher.
A key reason is the skew in merchandise mix towards gifting.
Around 40% of the products sold in Hidesign’s airport stores are gifts. “If you have a product which can be gifted, can be purchased quickly and is work-oriented, you’ve covered most of the problematic variables.”
An overwhelming majority of domestic air travellers are men, who may not spend two hours browsing a mall, but can quickly buy a premium handbag for someone back home. Time is their scarcest resource, not money.
“Those are breaks (from routine). These are things that they would normally not have time to do,” adds Forest Essentials executive director Samrath Bedi on why premium skincare too commands attention in an airport environment.
But categories such as perfumes, cosmetics, watches, sunglasses, travel accessories and bags have an obvious advantage – they can be bought quickly and generally don’t require fitting rooms or extensive trial. As Pravat Paikray, VP-Commercial, Bangalore International Airport, says, these “one-size-fits-all” categories perform well.
Right-Sizing
Apparel, jewellery and other categories involving multiple sizes, fits or lengthy considerations have a harder job.
“Standalone apparel and niche lifestyle stores would typically be loss-making,” says founder, Third Eyesight, Devangshu Dutta.
Shriram believes even these categories are being held back by conventional merchandising assumptions. He points out that a business traveller does not necessarily need another blazer simply because they are at an airport. What they may need is a pair of track pants for an overnight trip, a gift for someone at home, or a product they discover while waiting for a flight.
For instance, Ramraj Cotton’s proposition works partly because of its local-brand resonance and partly because of its gifting-driven merchandising. “There are a lot of combos which work very well for gifting,” says Radhakrishnan. He says passengers are usually concerned about weight restrictions, so the store even repackages the items as per requirement. The brand declined Brand Equity’s interview request.
Airport merchandise can carry a 20-40% premium, he says, because the customer is paying partly for convenience. The traveller does not necessarily want to step out into the city just to save a few hundred rupees.
Front of the Queue
Paikray says Bengaluru airport explicitly designs its retail proposition around this time constraint. Brands are expected to adapt their store design, assortment, staffing, service and operations rather than simply transplanting their city format. “If a brand has 100 stores, don’t come and open 101st store in an airport, ” he says.
For Forest Essentials, what changes is also the reason the consumer is being shown the product, says Bedi. Hydration for flying, sleep on long journeys, stress relief, gifting, replenishment, etc. “It’s just about how you angle it.”
Bengaluru airport is also lowering the barriers for brands to test the market by using pop-up stores to let newer brands test travel retail without committing to long-term contracts.
Paikray says challenger and D2C brands are increasingly considering airports earlier in their expansion journeys.
But the opportunity is not on auto-pilot. Only those who adapt can turn the minutes before boarding into something more valuable than visibility – a sale.
(Published in ET Brand Equity)
admin
July 20, 2026
Kartikay Kashyap, Financial Express / Brandwagon
30 July 2026
Wendy’s first foray into India’s quick service restaurant (QSR) market in 2015 remained a non-starter. Sierra Nevada Restaurants, the then master franchisee, could not scale its retail presence beyond four conventional restaurants concentrated largely in Delhi-NCR. This limited physical availability, brand awareness and ordering frequency.
Ten years on and under a new master franchisee Rebel Foods since 2023, Wendy’s seems to have turned over a new leaf. With more than 250 stores, and ₹200 crore in revenues, the brand wants to be the one-stop destination for the younger generation where consumers come together to celebrate food, music and a sense of community. “The longer-term ambition is to expand to approximately 500 locations by 2028 through a combination of delivery kitchens and physical restaurants,” says Joy Bamania, brand head, Wendy’s India.
As a first step, Rebel Foods recently opened what it calls its “dynamic cultural flagship store” in Delhi’s vibrant student hub of Hudson Lane, GTB Nagar. The two-level youth-centric space blends food, music and anime, offering fans experiences like live rap battles, meet-and-greets, and specialised menu items like the signature Teriyaki Burger range.
“It has been designed to be livelier, more youthful and visually engaging—an Instagram-worthy space. It is a physical expression of how we want consumers to experience Wendy’s in India: bold, fun, culturally relevant and full of energy,” says Bamania.
Even before taking over Wendy’s operations Rebel Foods had been managing its delivery-only cloud kitchens since 2020 and was familiar with the brand’s DNA and what was required to mount a serious challenge in the ₹15,000-plus crore organised burger restaurants market in the country. The low capex delivery-only model has helped to improve its gross margins, but taking on established brands like McDonalds, KFC and Burger King would be a completely new ball game.
Is the latecomer up to a second bout in the ring?
New, improved
Wendy’s has at least three things going against it. It arrived late on India’s shores and couldn’t really stand apart during its last outing. “No matter how big a global brand you are, you need to stand out in the clutter,” says Devangshu Dutta, founder & CEO, Third Eyesight.
So while McDonald’s is the kid-first family restaurant, Burger King is intentionally “imperfect” and rides on humour, pop-culture moments, and viral marketing. Wendy’s, say experts, had no differentiation than just being a global brand.
Its premium pricing was another bugbear. In its first foray, Wendy’s tried to justify its higher prices saying its ingredients were better than that offered by the rest of the pack. So while the price of a Wendy’s entry level burger was ₹100, McDonald’s retailed one at half that price. “In the QSR business, you have to get your price right. There is nothing ‘premium’ in that space,” says Ankur Bisen, senior partner, The Knowledge Company. Rebel Foods addressed these problems with four fundamental shifts.
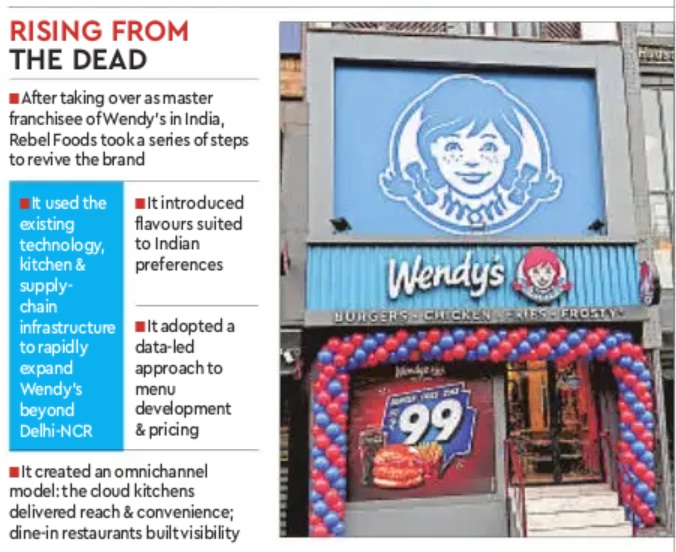
First, it used the existing technology, kitchen and supply-chain infrastructure to rapidly expand Wendy’s beyond Delhi-NCR. Second, it built a stronger and more accessible value architecture while introducing flavours suited to Indian preferences. Third, it created an omnichannel model in which cloud kitchens delivered reach and convenience, while selected dine-in restaurants built visibility and deeper brand experiences. Finally, it adopted a data-led approach to menu development, pricing, consumer feedback and operational performance.
Rebel Foods became Wendy’s master franchisee in India in 2023. At that stage, Wendy’s had approximately 90 locations across 19 cities. By March 2025, the brand had reached 200 locations across more than 50 cities, including 15 dine-in restaurants.
“The fivefold revenue growth has consequently not come from one product or campaign. It is the result of wider distribution, sharper value, continuous menu innovation, stronger operational execution and a much clearer proposition for the Indian consumer,” says Bamania.
(Published in Financial Express)
admin
June 30, 2026
Vaeshnavi Kasthuril, MINT
30 June 2026, Mumbai
Advent International-backed Modenik Lifestyle Pvt. Ltd is doubling down on its portfolio of legacy innerwear brands, planning to scale each label into a sizeable business rather than rely on a single flagship brand.
“Each of the brands must grow big enough to be called a company of its own,” Shekhar Tewari, chief executive and executive director, told Mint.
The company has four brands: premium women’s innerwear label Enamor, value brand Slimz, mass-premium men’s label Dixcy Scott, and premium men’s innerwear brand Levi’s. “These brands are very strong in their respective segments. They complement each other rather than compete,” Tewari said.
Levi’s Innerwear is priced between ₹250 and ₹550, Dixcy Scott and Slimz between ₹100 and ₹350, while Enamor’s products start at ₹500 and go beyond ₹2,500.
The strategy comes as India’s innerwear market, particularly women’s lingerie, has become one of the country’s most fiercely contested apparel categories, with established retailers and digital-first brands vying for market share.
Modenik’s focus on innerwear deepened after private equity firm Advent brought Enamor and Dixcy together under Modenik Lifestyle, following its acquisition of Enamor from Gokaldas Exports in 2019.
Both brands had expanded into adjacent categories such as athleisure, loungewear, sleepwear and outerwear, but struggled to keep pace with rising competition from fashion retailers and digital-first brands. The company has since exited much of its outerwear portfolio, taking a revenue hit.
“We took a conscious hit on the top line because we wanted to become a focused innerwear company,” Tewari said. “If you’re trying to be everything to everyone, you end up not being known for anything. We wanted consumers to think of us first when they think of innerwear.”
Revenue has remained largely flat at around ₹1,200 crore over the past three years, though losses have narrowed sharply. FY25 revenue stood at ₹1,224 crore, while net loss halved to ₹24.8 crore from ₹50.8 crore a year earlier.
Modenik aims to outpace the industry’s single-digit growth by increasing branded penetration in women’s innerwear, expanding its premium portfolio and adding exclusive store network, expected to cross 100 outlets in the near term.
The company sees significant headroom in women’s innerwear, where it estimates the market at more than ₹20,000 crore, but organised brands account for only ₹3,000-4,000 crore. It expects formalization, premiumization and product innovation to accelerate brand adoption.
According to Devangshu Dutta, chief executive of retail consultancy Third Eyesight, the market’s increasing fragmentation makes a multi-brand strategy more effective.
“You can’t have one brand stretching across multiple segments. The product has to be different, pricing strategies are different, the messaging and the distribution channel mix also varies depending on the consumer segment you’re trying to target,” he said.
According to industry estimates, India’s innerwear market is valued at over ₹90,000 crore (about $10.9 billion) and is expected to grow at a 6-7% compound annual growth rate (CAGR) over the next decade.
Advantages and avenues
Tewari believes Modenik has structural advantages over many digital-first rivals. Unlike online-first brands that typically outsource manufacturing, the company controls product development and manufacturing while leveraging decades-old relationships with distributors, department stores, exclusive brand outlets and multi-brand retailers.
“Those capabilities have been built over decades. They cannot be replicated overnight,” he said.
The company is also expanding across channels. Enamor is available through 6,000-7,000 multi-brand outlets, nearly 80 exclusive stores, department stores, including Shoppers Stop, Lifestyle, Central and Pantaloons, besides online marketplaces and quick commerce platforms. E-commerce contributes over 30% of Enamor’s revenue.
Although digital commerce is growing rapidly, Tewari believes physical retail will continue to play a critical role in the category.
“Innerwear is a category that requires understanding of fit, size and functionality. Consumers still want to touch, feel and try products before making the switch from unbranded to branded,” he said.
Rather than pursuing acquisitions, the company plans to unlock growth from its existing portfolio.
The strategy comes as competition in India’s innerwear market is intensifying. Page Industries dominates through Jockey, while Reliance Retail, which houses brands such as Clovia, Marks & Spencer and Hunkemöller, acquired digital-first lingerie platform Zivame, and added premium lingerie brand amanté. Aditya Birla Fashion and Retail has expanded Van Heusen Innerwear, while Trent has strengthened its innerwear offering through its private label brands at Westside and Zudio. New-age brands such as Shyaway, Bummer and Nykd by Nykaa have also stepped up investments in their products.
(Published in MINT)
