admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
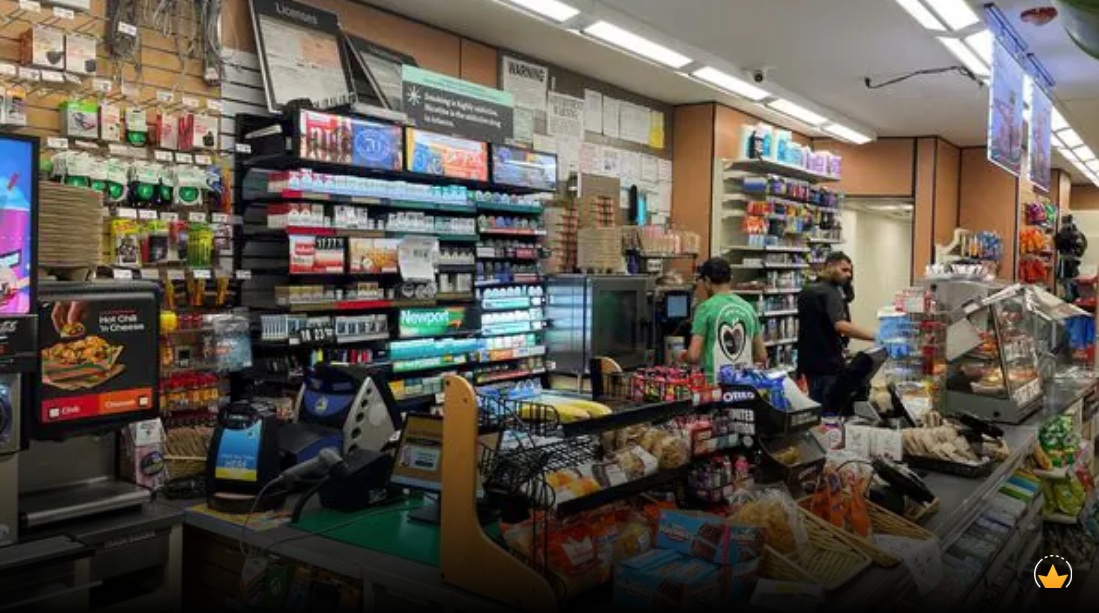
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
October 7, 2026
Vidya Sathyapriyan, ET Brand Equity
7 October 2026
Every single month, leather-goods brand Hidesign changes the storefront of its airport stores. The reason: “You can’t bore the man or woman who’s coming to the airport every week,” says founder Dilip Kapur.
But then what makes the airport shopper any different from someone walking into a high-street or mall store? Affluent? Sure. Willing to spend? Mostly. Time-poor and seeking convenience? Definitely.
That mix presents a particular challenge for brands: understanding what and why travellers will buy, and how quickly they can buy it.
Some have learnt to make the often lopsided economics work. Others are running an expensive billboard with a billing counter attached.
Crunching Numbers
The economics are punishing.
Airport rents, minimum guarantees, revenue-share, staffing and operating costs can make them significantly more expensive than conventional retail. For example, a good mall in Chennai charges roughly Rs. 350-800 per sq ft monthly in retail rent, compared with Rs. 150-200 per sq. ft. on the high street. Airport rentals can rise to as much as Rs. 6,000 per sq. ft. Similar differentials play out in other major cities.
Yet brands keep signing on because the alternative would be an advertising site with no retail attached. “A hoarding is for all and sundry and 1D,” says S. Shriram, founder of Miles2Go Consulting Services. “In the airport, captive audience, engagement is 3D and sometimes even 4D – touch and feel, trial, buy, and even return elsewhere.”
For deep-pocketed brands, spending on airport visibility can be justified even when store-level profitability is modest or even non-existent. Others gotta move on.
Go Colors, for instance, is rationalising stores at airports where the economics are not working. “The opportunity remains strong, but the location must justify the cost of access to the consumer,” says CMO Vatsal Koolwal. “As a broad benchmark, rentals in the range of 15-20% of revenue can work, provided the rest of the cost structure is managed effectively.”
The right sell
Six of Hidesign’s top-10 stores in India are at airports, says Kapur. The average Hidesign airport store generates roughly twice the turnover of an average mall store, while its smaller footprint pushes sales per square foot even higher.
A key reason is the skew in merchandise mix towards gifting.
Around 40% of the products sold in Hidesign’s airport stores are gifts. “If you have a product which can be gifted, can be purchased quickly and is work-oriented, you’ve covered most of the problematic variables.”
An overwhelming majority of domestic air travellers are men, who may not spend two hours browsing a mall, but can quickly buy a premium handbag for someone back home. Time is their scarcest resource, not money.
“Those are breaks (from routine). These are things that they would normally not have time to do,” adds Forest Essentials executive director Samrath Bedi on why premium skincare too commands attention in an airport environment.
But categories such as perfumes, cosmetics, watches, sunglasses, travel accessories and bags have an obvious advantage – they can be bought quickly and generally don’t require fitting rooms or extensive trial. As Pravat Paikray, VP-Commercial, Bangalore International Airport, says, these “one-size-fits-all” categories perform well.
Right-Sizing
Apparel, jewellery and other categories involving multiple sizes, fits or lengthy considerations have a harder job.
“Standalone apparel and niche lifestyle stores would typically be loss-making,” says founder, Third Eyesight, Devangshu Dutta.
Shriram believes even these categories are being held back by conventional merchandising assumptions. He points out that a business traveller does not necessarily need another blazer simply because they are at an airport. What they may need is a pair of track pants for an overnight trip, a gift for someone at home, or a product they discover while waiting for a flight.
For instance, Ramraj Cotton’s proposition works partly because of its local-brand resonance and partly because of its gifting-driven merchandising. “There are a lot of combos which work very well for gifting,” says Radhakrishnan. He says passengers are usually concerned about weight restrictions, so the store even repackages the items as per requirement. The brand declined Brand Equity’s interview request.
Airport merchandise can carry a 20-40% premium, he says, because the customer is paying partly for convenience. The traveller does not necessarily want to step out into the city just to save a few hundred rupees.
Front of the Queue
Paikray says Bengaluru airport explicitly designs its retail proposition around this time constraint. Brands are expected to adapt their store design, assortment, staffing, service and operations rather than simply transplanting their city format. “If a brand has 100 stores, don’t come and open 101st store in an airport, ” he says.
For Forest Essentials, what changes is also the reason the consumer is being shown the product, says Bedi. Hydration for flying, sleep on long journeys, stress relief, gifting, replenishment, etc. “It’s just about how you angle it.”
Bengaluru airport is also lowering the barriers for brands to test the market by using pop-up stores to let newer brands test travel retail without committing to long-term contracts.
Paikray says challenger and D2C brands are increasingly considering airports earlier in their expansion journeys.
But the opportunity is not on auto-pilot. Only those who adapt can turn the minutes before boarding into something more valuable than visibility – a sale.
(Published in ET Brand Equity)
admin
October 5, 2026
Sagar Malviya, Economic Times
5 October 2026
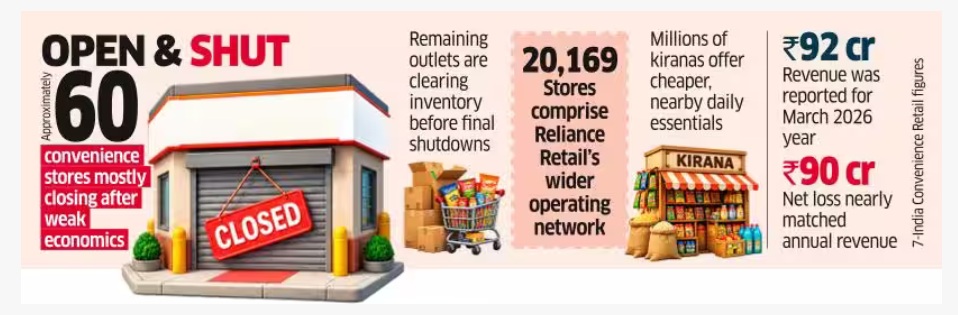
Reliance Retail and 7-Eleven are ending their five-year franchisee deal in India, closing most of the nearly 60 convenience stores they operated under the partnership, after struggling to make the format profitable, people familiar with the matter said.
A handful of outlets are clearing the inventory before shutting, they said. 7-Eleven may look for another Indian partner to keep a foothold in the market, although no decision has been made, the people said.
The exit highlights an unusual squeeze that convenience stores are facing in India, with millions of small kirana stores that have long served consumers’ immediate needs on one side and quick-commerce companies that are bringing the same snacks, groceries and daily essentials to doorsteps within minutes on the other.
Reliance and 7-Eleven did not respond to ET’s queries.
The partnership, struck in 2021, was intended to bring the world’s largest convenience-store chain to India through Reliance’s retail network. But the business struggled to achieve the scale needed to offset the relatively high costs of running branded stores.
The 7-India Convenience Retail venture reported revenue of about ₹92 crore ($10.6 million) and a net loss of nearly ₹90 crore in the year ended March 2026, according to its financial statements.
“Reliance wants to reach consumers across every channel, but sustainability ultimately matters. Convenience stores have faced increasing pressure from quick commerce since the pandemic, with both formats offering similar assortments and serving the same immediate-needs occasions,” said Devangshu Dutta, founder and CEO of Third Eyesight, a consumer-sector consultancy.
“Kiranas operate with far lower overheads and different margin expectations than corporate-run convenience stores. Reliance’s exit could therefore signal a broader rethink of the format, particularly in markets where quick commerce has become a strong alternative.”
Globally convenience stores have become powerful retail businesses in several markets despite the expansion of supermarkets and hypermarkets. 7-Eleven in Japan, Taiwan, Thailand and Singapore; Lawson in Japan and Oxxo in Mexico are among the largest retailers in their respective markets.
7-Eleven’s Japanese parent, Seven & i Holdings, operates more than 85,000 stores globally, making it one of the world’s largest retail networks. Yet the company has been restructuring its overseas operations and closing stores in North America as consumer behaviour and store economics change.
In India, however, organised convenience retail has struggled to replicate the success seen in other Asian and emerging markets. EasyDay, More and Spencer’s have either shut stores or shrank their smaller-format networks over the years, underscoring the difficulty of building profitable neighbourhood stores at scale.
Packaged consumer goods companies continue to derive roughly three-fourths of their sales from small neighbourhood stores, underlining the strength of the traditional distribution network. Quick commerce platforms are, meanwhile, expanding rapidly.
That makes it difficult for organised convenience stores to charge a premium or generate sufficient sales density to cover higher rents, staffing, inventory and logistics costs.
Convenience retail works best when operators achieve high store density and productivity, supported by strong supply chains and differentiated offerings such as fresh food and private labels.
Reliance initially expanded the 7-Eleven network in Mumbai and other markets, but the footprint remained small compared with the company’s wider retail operations.
(Published in Economic Times)
admin
June 12, 2026
Aanya Thakur & Writankar Mukherjee, Economic Times
12 June 2026, Mumbai/Kolkata
India’s leading retail chains have seen the share of e-commerce in total sales either remain flat or edge up by a sluggish 1-2 percentage points over the past four-five years despite a sustained push towards omnichannel retailing.
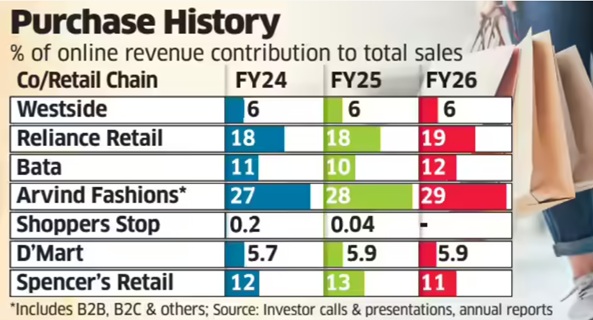
An ET analysis of eight major retailers-market leader Reliance Retail, Shoppers Stop, Westside, Arvind Fashions, DMart, Spencer’s Retail, Pantaloons and Bata-showed that the contribution of e-commerce to overall revenue has seen minuscule improvement since 2021-22 even as online sales continue to increase in absolute terms. By contrast, the Covid-19 pandemic spurred explosive growth, with the share of digital sales in total revenue surging three to four times in 2020-21 and 2021-22.
Industry executives attribute the slowdown partly to lower investment levels compared with pure-play digital firms such as Amazon, Flipkart, Swiggy and Blinkit-parent Eternal. Besides, retailers have consistently maintained that they will not pursue online growth at the expense of profitability, keeping prices largely aligned across online and offline channels.
The ET study found Tata-owned Westside’s online contribution stood at 7% in 2021-22 and thereafter remained around 6% till 2025-26. Reliance Retail’s online share ranged between 17% and 19% during the period, while Bata’s remained at 10-12%.
For DMart, e-commerce accounted for 5-6% of sales, while Shoppers Stop’s online arm, Shoppers Stop.Com (India) Ltd, contributed less than 1% to the consolidated revenue between 2021-22 and 2024-25. The company has not disclosed 2025-26 online sales figures yet.
“The DNA of these retailers is rooted in the physical world-infrastructure, processes and systems are not inherently designed for e-commerce, which requires a different operating model,” said Devangshu Dutta, chief executive of consultancy Third Eyesight.
“Most retailers calling themselves omnichannel are effectively multi-channel. Online retail is capital-intensive and hyper-competitive. Given the significant scope for physical store expansion, especially in tier-2 and tier-3 cities, retailers are reluctant to invest aggressively online,” he said.
Even so, Avenue Supermarts, which runs DMart, invested Rs 150 crore in online grocery platform DMart Ready this week, following a Rs 174-crore infusion a year earlier.
By comparison, Eternal infused Rs 2,600 crore into Blinkit in 2025 and another Rs 450 crore in March this year. Similarly, Swiggy approved a Rs 1,000-crore investment in supply-chain subsidiary Scootsy last year as both companies expanded their dark-store networks.
The chief executive of Aditya Birla-owned departmental chain Pantaloons, Sangeeta Tanwani, recently told analysts that online sales accounted for just 3-4% of the business. She said the company had earlier refrained from investing in the channel because profitability remained elusive.
“But over the last year, we called out omnichannel as one of our priorities… The reason why we had paused that business was because we wanted to make sure that we can get the unit economics right and make this business profitable… With all the shifts we have made this year, we feel confident of scaling up this business,” Tanwani said.
Reliance Retail, meanwhile, reported lower earnings before interest, taxes, depreciation and amortisation (EBITDA) margin growth in both the January-March quarter and entire 2025-26 as investments in quick commerce weighed on profitability. Chief financial officer Dinesh Taluja recently told analysts that margins depend on the pace at which online and business-to-business segments grow relative to the core offline business.
“If we slow down online growth, margins will improve. It is a mix as far as the online business continues to grow faster,” he had said.
An industry executive said the online contribution may go up modestly in this financial year due to high investment in scaling up dark stores for quick commerce.
Queries emailed to Reliance Retail did not elicit a response till press time. The company had in December last year appointed former Flipkart executive Jeyandran Venugopal as its new chief executive for the retail business.
(Published in Economic Times)
admin
February 18, 2026
Kartikay Kashyap, BrandWagon, Financial Express
18 February 2026
IKEA HAS BEEN around in India for about eight years, with another three years before that spent studying the market. It has developed a range that it deems “locally relevant-like the roti maker, the tava (pan), the belan (rolling pin), and the pressure cooker -which now constitute about 50% of the products it offers in the country. It has shifted its communication strategy to sync with local culture and fit into local spaces and has worked hard to beef up its omnichannel sales model with about 30% of its sales originating online. But profitability has remained elusive for the retailer whose global sales reached approximately €45billion in the 2015 financial year (FY25).
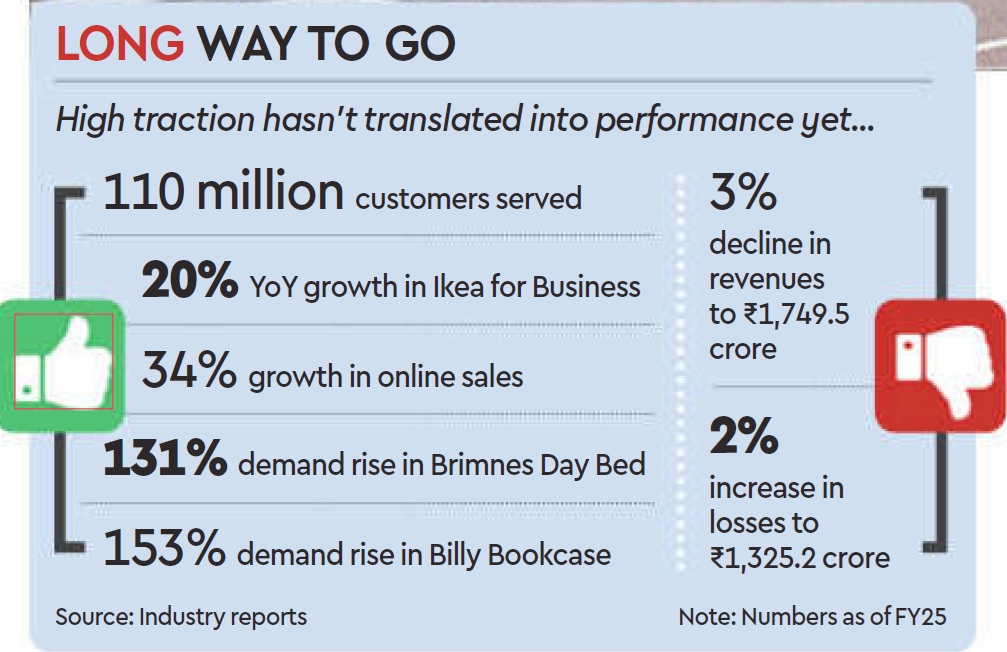
Just for context, the company’s India entity widened its losses by about 29 to 1,325.2 crore in the financial year ending March 31, 2025 (FY25). The revenue also dipped 3 to 1,749.5 crore from 1,809.8 crore in FY25.
So now the brand is taking a leaf out of its China playbook and tweaking its retail formats. Starting last year, it started piloting smaller store sizes ranging from 15,000-20,000 sq ft that are more cost-effective to set up and faster to integrate with its omnichannel model. “The goal is to create a simpler and more efficient shopping experience,” Ingka Group Retail Manager Tolga Oncu had said when the concept was unveiled last August.
Five months on, the furniture retailer is looking to take a step up the ladder – setting up new stores in the 50,000-70,000 sq ft range in the country, which will sit comfortably between its smaller stones (15,000-20,000 sq ft) and big box retail outlets (4 lakh sq ft), Adosh Sharma, country commercial manager at Ikea India told FE recently. Ikea’s broader plan also includes doubling its investments in the country to over 20,000 crore ($2.2 billion) over the next five years and improving local sourcing.
Will all this help the retailer grab a larger share of the highly fragmented furniture and furnishing market in the country? Will the brand achieve profitability in the next two years in keeping with its plans?
Ikea realises copy-pasting its global retail strategy in India is not going to work. That explains its recent moves to tweak store sizes and product design. Over and above the regular 5-M-L strategy, the fourth format the brand is developing comprises no-frills planning and order points, focused on customers who want to design homes or seek complex solutions without distraction.
“Smaller stores, which fulfill purpose-led needs will help them to get closer to their customers,” says Devangshu Dutta, founder & CEO, Third Eyesight.
The furniture and home decor segment has been up against slow purchase cycles in India. Smaller sized stores that are closer to residential arras might help step up the frequency of purchases. “Players are moving towards a higher purchase frequency strategy and smaller stores will help lkea cash in on this opportunity,” says Kushal Bhatnagar, associate partner, Redseer Consultant Strategy. He says quick commerce has helped improve the purchase cycle in the home decor space, and that is something Ikea will likely tap going forwand.
Dutta says Ikea has taken a long-term view on India and the investments in the pipeline is an indication of the opportunity that awaits players.
The brand claims it has served close to 110 million customers in FY25 across channels, and online sales are growing 34% compared to the previous fiscal. While furniture contributed the lion’s share of its revenue, the food business contributed 100% and Ikea for Business (tailored solutions for businesses) another 19% to its topline.
(Published in Financial Express)
