admin
October 7, 2026
Vidya Sathyapriyan, ET Brand Equity
7 October 2026
Every single month, leather-goods brand Hidesign changes the storefront of its airport stores. The reason: “You can’t bore the man or woman who’s coming to the airport every week,” says founder Dilip Kapur.
But then what makes the airport shopper any different from someone walking into a high-street or mall store? Affluent? Sure. Willing to spend? Mostly. Time-poor and seeking convenience? Definitely.
That mix presents a particular challenge for brands: understanding what and why travellers will buy, and how quickly they can buy it.
Some have learnt to make the often lopsided economics work. Others are running an expensive billboard with a billing counter attached.
Crunching Numbers
The economics are punishing.
Airport rents, minimum guarantees, revenue-share, staffing and operating costs can make them significantly more expensive than conventional retail. For example, a good mall in Chennai charges roughly Rs. 350-800 per sq ft monthly in retail rent, compared with Rs. 150-200 per sq. ft. on the high street. Airport rentals can rise to as much as Rs. 6,000 per sq. ft. Similar differentials play out in other major cities.
Yet brands keep signing on because the alternative would be an advertising site with no retail attached. “A hoarding is for all and sundry and 1D,” says S. Shriram, founder of Miles2Go Consulting Services. “In the airport, captive audience, engagement is 3D and sometimes even 4D – touch and feel, trial, buy, and even return elsewhere.”
For deep-pocketed brands, spending on airport visibility can be justified even when store-level profitability is modest or even non-existent. Others gotta move on.
Go Colors, for instance, is rationalising stores at airports where the economics are not working. “The opportunity remains strong, but the location must justify the cost of access to the consumer,” says CMO Vatsal Koolwal. “As a broad benchmark, rentals in the range of 15-20% of revenue can work, provided the rest of the cost structure is managed effectively.”
The right sell
Six of Hidesign’s top-10 stores in India are at airports, says Kapur. The average Hidesign airport store generates roughly twice the turnover of an average mall store, while its smaller footprint pushes sales per square foot even higher.
A key reason is the skew in merchandise mix towards gifting.
Around 40% of the products sold in Hidesign’s airport stores are gifts. “If you have a product which can be gifted, can be purchased quickly and is work-oriented, you’ve covered most of the problematic variables.”
An overwhelming majority of domestic air travellers are men, who may not spend two hours browsing a mall, but can quickly buy a premium handbag for someone back home. Time is their scarcest resource, not money.
“Those are breaks (from routine). These are things that they would normally not have time to do,” adds Forest Essentials executive director Samrath Bedi on why premium skincare too commands attention in an airport environment.
But categories such as perfumes, cosmetics, watches, sunglasses, travel accessories and bags have an obvious advantage – they can be bought quickly and generally don’t require fitting rooms or extensive trial. As Pravat Paikray, VP-Commercial, Bangalore International Airport, says, these “one-size-fits-all” categories perform well.
Right-Sizing
Apparel, jewellery and other categories involving multiple sizes, fits or lengthy considerations have a harder job.
“Standalone apparel and niche lifestyle stores would typically be loss-making,” says founder, Third Eyesight, Devangshu Dutta.
Shriram believes even these categories are being held back by conventional merchandising assumptions. He points out that a business traveller does not necessarily need another blazer simply because they are at an airport. What they may need is a pair of track pants for an overnight trip, a gift for someone at home, or a product they discover while waiting for a flight.
For instance, Ramraj Cotton’s proposition works partly because of its local-brand resonance and partly because of its gifting-driven merchandising. “There are a lot of combos which work very well for gifting,” says Radhakrishnan. He says passengers are usually concerned about weight restrictions, so the store even repackages the items as per requirement. The brand declined Brand Equity’s interview request.
Airport merchandise can carry a 20-40% premium, he says, because the customer is paying partly for convenience. The traveller does not necessarily want to step out into the city just to save a few hundred rupees.
Front of the Queue
Paikray says Bengaluru airport explicitly designs its retail proposition around this time constraint. Brands are expected to adapt their store design, assortment, staffing, service and operations rather than simply transplanting their city format. “If a brand has 100 stores, don’t come and open 101st store in an airport, ” he says.
For Forest Essentials, what changes is also the reason the consumer is being shown the product, says Bedi. Hydration for flying, sleep on long journeys, stress relief, gifting, replenishment, etc. “It’s just about how you angle it.”
Bengaluru airport is also lowering the barriers for brands to test the market by using pop-up stores to let newer brands test travel retail without committing to long-term contracts.
Paikray says challenger and D2C brands are increasingly considering airports earlier in their expansion journeys.
But the opportunity is not on auto-pilot. Only those who adapt can turn the minutes before boarding into something more valuable than visibility – a sale.
(Published in ET Brand Equity)
admin
October 5, 2026
Sagar Malviya, Economic Times
5 October 2026
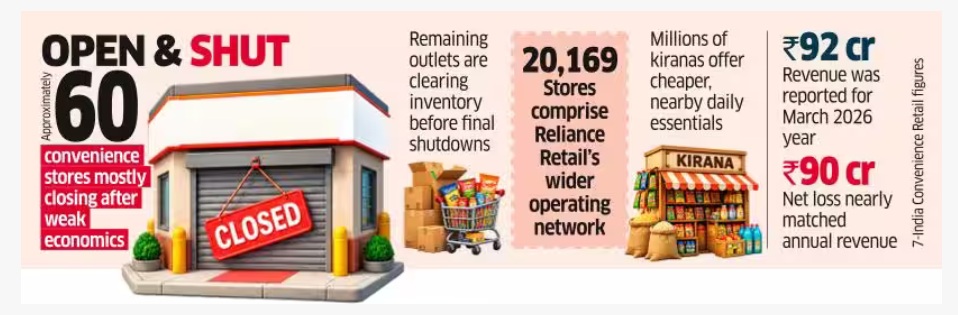
Reliance Retail and 7-Eleven are ending their five-year franchisee deal in India, closing most of the nearly 60 convenience stores they operated under the partnership, after struggling to make the format profitable, people familiar with the matter said.
A handful of outlets are clearing the inventory before shutting, they said. 7-Eleven may look for another Indian partner to keep a foothold in the market, although no decision has been made, the people said.
The exit highlights an unusual squeeze that convenience stores are facing in India, with millions of small kirana stores that have long served consumers’ immediate needs on one side and quick-commerce companies that are bringing the same snacks, groceries and daily essentials to doorsteps within minutes on the other.
Reliance and 7-Eleven did not respond to ET’s queries.
The partnership, struck in 2021, was intended to bring the world’s largest convenience-store chain to India through Reliance’s retail network. But the business struggled to achieve the scale needed to offset the relatively high costs of running branded stores.
The 7-India Convenience Retail venture reported revenue of about ₹92 crore ($10.6 million) and a net loss of nearly ₹90 crore in the year ended March 2026, according to its financial statements.
“Reliance wants to reach consumers across every channel, but sustainability ultimately matters. Convenience stores have faced increasing pressure from quick commerce since the pandemic, with both formats offering similar assortments and serving the same immediate-needs occasions,” said Devangshu Dutta, founder and CEO of Third Eyesight, a consumer-sector consultancy.
“Kiranas operate with far lower overheads and different margin expectations than corporate-run convenience stores. Reliance’s exit could therefore signal a broader rethink of the format, particularly in markets where quick commerce has become a strong alternative.”
Globally convenience stores have become powerful retail businesses in several markets despite the expansion of supermarkets and hypermarkets. 7-Eleven in Japan, Taiwan, Thailand and Singapore; Lawson in Japan and Oxxo in Mexico are among the largest retailers in their respective markets.
7-Eleven’s Japanese parent, Seven & i Holdings, operates more than 85,000 stores globally, making it one of the world’s largest retail networks. Yet the company has been restructuring its overseas operations and closing stores in North America as consumer behaviour and store economics change.
In India, however, organised convenience retail has struggled to replicate the success seen in other Asian and emerging markets. EasyDay, More and Spencer’s have either shut stores or shrank their smaller-format networks over the years, underscoring the difficulty of building profitable neighbourhood stores at scale.
Packaged consumer goods companies continue to derive roughly three-fourths of their sales from small neighbourhood stores, underlining the strength of the traditional distribution network. Quick commerce platforms are, meanwhile, expanding rapidly.
That makes it difficult for organised convenience stores to charge a premium or generate sufficient sales density to cover higher rents, staffing, inventory and logistics costs.
Convenience retail works best when operators achieve high store density and productivity, supported by strong supply chains and differentiated offerings such as fresh food and private labels.
Reliance initially expanded the 7-Eleven network in Mumbai and other markets, but the footprint remained small compared with the company’s wider retail operations.
(Published in Economic Times)
admin
July 13, 2026
Viveat Susan Pinto, S Shanthi (Financial Express)
13 July 2026
India’s new-age coffee chains are accelerating expansion despite continuing losses, as investors bet that the country’s under-penetrated branded cafe market can deliver long-term growth.
Third Wave Coffee plans to open 100 cafes this financial year while targeting company-wide break-even. Blue Tokai aims to expand from 240 outlets to 800 by FY30 and is preparing for an eventual public listing. Nothing Before Coffee (NBC), which has grown to 114 cafes across 45 cities, plans to more than double its network over the next two years.
The expansion comes even as profitability remains elusive. Investors, however, are increasingly prioritising store-level economics over headline profits, arguing that India’s cafe market is still in its early stages of growth.
“The earlier failures in the cafe segment were largely capital-discipline failures, not failures of the category itself,” said Vish Narain, managing partner at Pulsar Capital, which is backing Blue Tokai’s international expansion.
“Chains expanded store count before proving unit economics. Investors today understand that India’s per-capita coffee consumption is still in its early stages. They are reading past shutdowns as wrong execution, not wrong thesis,” he said.
Dissecting the Balance Sheets
The numbers highlight the challenge.
Heissette Beverages, the parent of Third Wave Coffee, accumulated losses of Rs 320 crore between FY21 and FY25, while total assets stood at Rs 538 crore at the end of FY25, according to Tracxn. Muhavra Enterprises, Blue Tokai’s parent, reported accumulated losses of Rs 175 crore over the same period, with total assets of nearly Rs 370 crore. Financials for FY26 are not yet available with Tracxn.
NBC accumulated losses of nearly Rs 3 crore over FY24 and FY25 against total assets of Rs 18 crore. Mumbai-based premium chain Subko Coffee, with 16 outlets in India and one in Dubai, posted losses of Rs 45 crore over five years, while total assets stood at Rs 61 crore at the end of FY25.
Third Wave Coffee said around 90% of its outlets are Ebitda-positive and expects to achieve company-wide break-even during FY27. Blue Tokai, backed by Verlinvest, is targeting profitability by March 2028.
NBC declined to specify a profitability timeline but said it has adopted a franchisee-invested, company-operated (FICO) model to reduce cash burn while retaining operational control.
“FICO lets us expand quickly with franchisee capital while keeping operational control,” said Ankesh Jain, co-founder and chief executive officer, Nothing Before Coffee.
Structural Shifts
Experts attribute the investor interest partly to improving outlet economics as operators shift from large dine-in formats to compact grab-and-go and cloud-kitchen models.
“These formats materially cut capex per outlet and shrink payback timelines, making the category venture-fundable rather than just a slow-and-steady, self-funded business,” said Krishna Dev Pathak, investment banker and advisor to early-stage startups.
Lower capital requirements have strengthened unit economics, reinforcing investor confidence despite delayed company-level profitability.
Investors are also betting on a broader shift in consumer behaviour. Anuj Kejriwal, chief executive officer and managing director of Anarock Retail, said rising incomes, urbanisation and changing preferences are gradually moving India from “a tea economy to a coffee economy”. The shift is widening the addressable market for organised coffee chains beyond the metros into smaller cities.
Consumers increasingly use cafes as workspaces, meeting points and all-day dining destinations, prompting chains to diversify into food, desserts, packaged coffee, vending solutions and merchandise.
“The cafe model is now well established as part of consumers’ lifestyles,” said Devangshu Dutta, founder and chief executive of retail consultancy Third Eyesight.
Challenges remain. Rentals in premium locations have surged, coffee prices remain volatile, and labour and supply-chain costs continue to pressure margins.
For now, investors appear willing to fund rapid expansion, betting that disciplined execution and improving unit economics will eventually turn India’s cafe boom into a profitable business.
(Published in Financial Express)
admin
June 12, 2026
Aanya Thakur & Writankar Mukherjee, Economic Times
12 June 2026, Mumbai/Kolkata
India’s leading retail chains have seen the share of e-commerce in total sales either remain flat or edge up by a sluggish 1-2 percentage points over the past four-five years despite a sustained push towards omnichannel retailing.
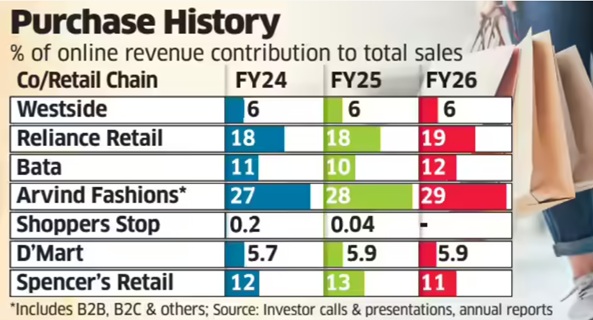
An ET analysis of eight major retailers-market leader Reliance Retail, Shoppers Stop, Westside, Arvind Fashions, DMart, Spencer’s Retail, Pantaloons and Bata-showed that the contribution of e-commerce to overall revenue has seen minuscule improvement since 2021-22 even as online sales continue to increase in absolute terms. By contrast, the Covid-19 pandemic spurred explosive growth, with the share of digital sales in total revenue surging three to four times in 2020-21 and 2021-22.
Industry executives attribute the slowdown partly to lower investment levels compared with pure-play digital firms such as Amazon, Flipkart, Swiggy and Blinkit-parent Eternal. Besides, retailers have consistently maintained that they will not pursue online growth at the expense of profitability, keeping prices largely aligned across online and offline channels.
The ET study found Tata-owned Westside’s online contribution stood at 7% in 2021-22 and thereafter remained around 6% till 2025-26. Reliance Retail’s online share ranged between 17% and 19% during the period, while Bata’s remained at 10-12%.
For DMart, e-commerce accounted for 5-6% of sales, while Shoppers Stop’s online arm, Shoppers Stop.Com (India) Ltd, contributed less than 1% to the consolidated revenue between 2021-22 and 2024-25. The company has not disclosed 2025-26 online sales figures yet.
“The DNA of these retailers is rooted in the physical world-infrastructure, processes and systems are not inherently designed for e-commerce, which requires a different operating model,” said Devangshu Dutta, chief executive of consultancy Third Eyesight.
“Most retailers calling themselves omnichannel are effectively multi-channel. Online retail is capital-intensive and hyper-competitive. Given the significant scope for physical store expansion, especially in tier-2 and tier-3 cities, retailers are reluctant to invest aggressively online,” he said.
Even so, Avenue Supermarts, which runs DMart, invested Rs 150 crore in online grocery platform DMart Ready this week, following a Rs 174-crore infusion a year earlier.
By comparison, Eternal infused Rs 2,600 crore into Blinkit in 2025 and another Rs 450 crore in March this year. Similarly, Swiggy approved a Rs 1,000-crore investment in supply-chain subsidiary Scootsy last year as both companies expanded their dark-store networks.
The chief executive of Aditya Birla-owned departmental chain Pantaloons, Sangeeta Tanwani, recently told analysts that online sales accounted for just 3-4% of the business. She said the company had earlier refrained from investing in the channel because profitability remained elusive.
“But over the last year, we called out omnichannel as one of our priorities… The reason why we had paused that business was because we wanted to make sure that we can get the unit economics right and make this business profitable… With all the shifts we have made this year, we feel confident of scaling up this business,” Tanwani said.
Reliance Retail, meanwhile, reported lower earnings before interest, taxes, depreciation and amortisation (EBITDA) margin growth in both the January-March quarter and entire 2025-26 as investments in quick commerce weighed on profitability. Chief financial officer Dinesh Taluja recently told analysts that margins depend on the pace at which online and business-to-business segments grow relative to the core offline business.
“If we slow down online growth, margins will improve. It is a mix as far as the online business continues to grow faster,” he had said.
An industry executive said the online contribution may go up modestly in this financial year due to high investment in scaling up dark stores for quick commerce.
Queries emailed to Reliance Retail did not elicit a response till press time. The company had in December last year appointed former Flipkart executive Jeyandran Venugopal as its new chief executive for the retail business.
(Published in Economic Times)
admin
May 9, 2026
Writankar Mukherjee, Economic Times
Kolkata, 9 May 2026
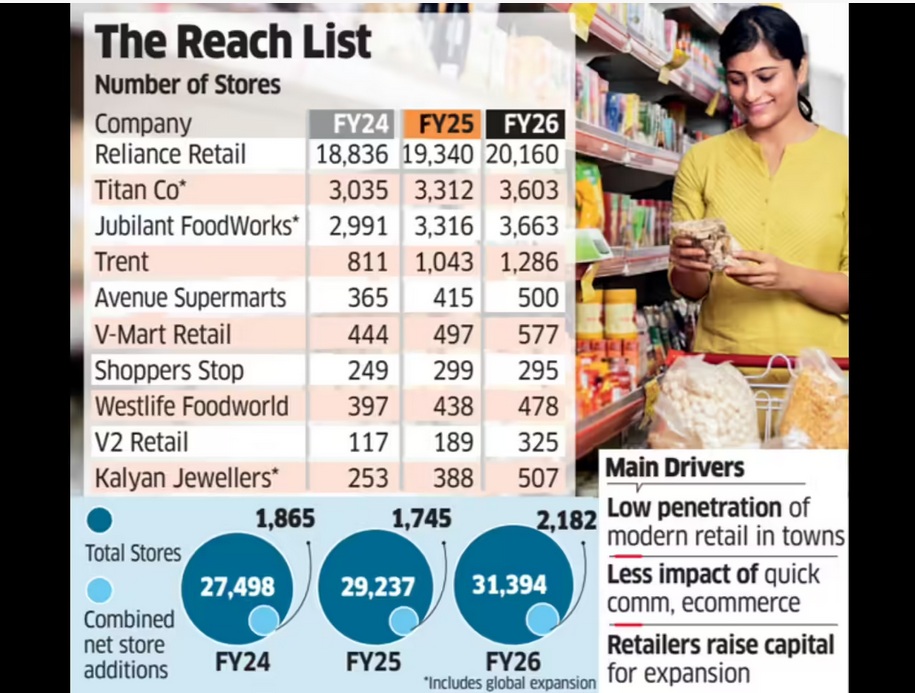
India’s top retail chains including Reliance Retail, DMart, Trent, Titan Company, Jubilant FoodWorks, and V-Mart Retail opened the highest number of stores in three years in FY26, seeking to capitalise on a demand recovery and a clean-up of unviable outlets added during the post-Covid revenge-spending period.
Entry into smaller towns and cities where many consumers continue to prefer shopping at physical stores over online is also influencing the expansion plans.
An ET study of the 10 largest listed retailers showed they added 25% more stores in the last fiscal year compared to FY25. Additions are on a net basis after accounting for loss-making outlet closures.
Collectively, the retailers added 2,182 stores in FY26, equivalent to six new stores a day on a net basis. In comparison, they added 1,745 stores in FY25 and 1,865 in FY24.
Retailers attributed the store expansion spree to improving consumer sentiment, helped further by cuts in income tax and goods and services tax (GST) rates last fiscal, along with low penetration of organised retail in smaller towns and cities. Together, the ten retailers had 31,394 stores operational as of March 2026.
Expansion Set to Continue
V-Mart Retail chief executive officer Lalit Agarwal said the ongoing shift from unorganised to organised retail is fuelling this expansion as several companies are meeting their sales growth expectations. “Many retailers have also raised capital, which they are deploying to grow topline,” he said, adding that the “growth phase will continue in the current fiscal as well.”
Companies surveyed by ET also include Shoppers Stop, Westlife Foodworld, V2 Retail and Kalyan Jewellers. Together, the ten retailers had 31,394 stores operational as of March 2026. Their combined store count grew 7% in FY26, ahead of a 6% expansion in the year before.
Reliance Retail alone added 820 net stores last fiscal, rebounding from a slowdown in FY25 when it shut several unviable outlets that were opened immediately post Covid, impacting overall industry growth rates. The country’s largest retailer had added 504 net stores in FY25, 796 in FY24, and 2,844 in FY23.
Similarly, Tata-owned Titan added 532 stores in FY23, but expansion moderated to 280-290 stores annually in FY25 and FY26.
India’s retail industry saw hyper expansion in late FY22 and FY23 as retailers sought to tap a boom in post-pandemic revenge shopping.
“Retail expansion now is more organic and measured as compared to the post Covid phase when there was a huge backlog of demand and over expansion,” said Devangshu Dutta, founder and CEO at Third Eyesight, a consultancy in consumer space.
(Published in Economic Times)
