admin
July 27, 2026
Vaeshnavi Kasthuril, MINT
Bengaluru, 27 Jul 2026
Over the past six years, Trent Ltd has grown its revenue more than fivefold, outpacing Titan Co. Ltd, Tata Consumer Products Ltd (TCPL) and Voltas Ltd to become the fastest-growing established company in Tata Sons’ consumer and retail portfolio.
Trent, incorporated in 1998, is the youngest among the Tata group’s four major listed consumer businesses. Voltas was incorporated in 1954, TCPL traces its origins to Tata Tea, established in 1962, while Titan was incorporated in 1984.
While Titan remains the group’s largest consumer business by revenue, Trent has overtaken Voltas and nearly caught up with TCPL.
Trent’s revenue rose to ₹20,189 crore in FY26 from ₹3,635 crore in FY20, showed Tata Sons’ FY26 annual report. In comparison, Titan’s revenue expanded 4.2 times, while TCPL and Voltas grew 2.1 times and 1.8 times, respectively. Six years ago, Trent accounted for just 8.6% of the combined revenue of the group’s four major consumer businesses. In FY26, that share has climbed to 14.1%, close to TCPL’s 14.3%.
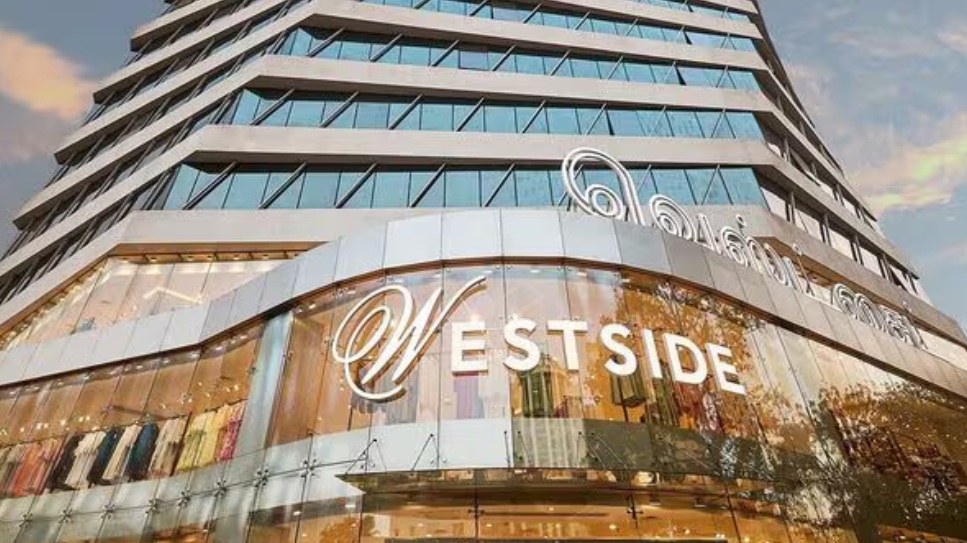
Trent’s portfolio includes Westside and Zudio in fashion, Samoh and Burnt Toast in newer lifestyle formats, and Star in grocery retail.
Zudio effect
The growth has been driven by Trent’s aggressive expansion across value and premium fashion. Zudio has emerged as the retailer’s biggest growth engine, benefiting from rising demand for affordable fashion among middle-income consumers, while Westside has continued to strengthen its presence in the premium apparel and lifestyle segment.
Zudio has been “a phenomenal driver of revenue growth”, with the retailer aggressively expanding the format over the past few years, said Devangshu Dutta, founder of retail consulting firm Third Eyesight.
He said Trent has also benefited from a structural shift in the country’s retail landscape as consumers increasingly move from fragmented, unorganised markets to organised retail. “The conversion from informal to formal happens not so much driven by demand but by availability. So if you open a new outlet… you have something which was not there earlier, which becomes a magnet for footfall,” Dutta said.
He said that Zudio’s combination of fashion-led products and sharp pricing has helped it stand out in the crowded value apparel market.
The retailer has simultaneously expanded beyond apparel into adjacent categories such as beauty and personal care, home décor, footwear, and accessories through Westside, while also nurturing newer concepts, including Samoh, Burnt Toast, and Star.
During FY26, Trent added 289 stores, taking its total network to 1,286 outlets across 321 cities and expanding its retail footprint to more than 17.7 million sq. ft.
The company said it sees opportunities to increase store density in existing markets while expanding into new cities, particularly as demand for organized retail continues to deepen beyond the country’s largest metropolitan areas.
The next phase of growth is likely to be driven by Westside. According to media reports, Trent plans to significantly accelerate the expansion of its flagship premium fashion chain by opening up to 100 stores annually, nearly double its historical pace. The chain, which had 300 stores at the end of FY26, is expected to expand into newer geographies, including the northeastern states, while strengthening its presence in key metropolitan markets.
Dutta said macroeconomic uncertainty, including the impact of geopolitical tensions and softer employment conditions, could weigh on discretionary spending. “If there is uncertainty, then you tend to be a little bit more careful,” he said.
Dutta said that while consumer demand may fluctuate in the short term, the long-term shift towards modern retail remains firmly intact.
Noel Tata’s farewell message
The FY26 annual report also carries Noel Tata’s final message as chairman of Trent, marking the end of an era for the retailer he helped transform into one of India’s largest fashion retailers.
Tata reiterated his long-held ambition of building Trent into a platform capable of creating and scaling multiple consumer businesses rather than relying on a single retail format. “I have long believed that Trent is not intended to be defined by a single brand, but rather by a portfolio of brands,” he wrote, adding that Westside, Zudio and Star continue to have significant runway for growth.
Looking ahead, he said Trent should aspire to build Indian brands with global relevance and generate a material share of revenues from overseas markets.
He also recalled his vision, first articulated in 2023, of making Trent ten times larger in terms of revenue with commensurate profitability, noting that the company’s revenue and profitability run rate have already grown more than 2.5 times since then.
The company has not yet named a successor to Noel Tata, who is set to retire as chairman in November.
(Published in MINT)
admin
February 18, 2026
Kartikay Kashyap, BrandWagon, Financial Express
18 February 2026
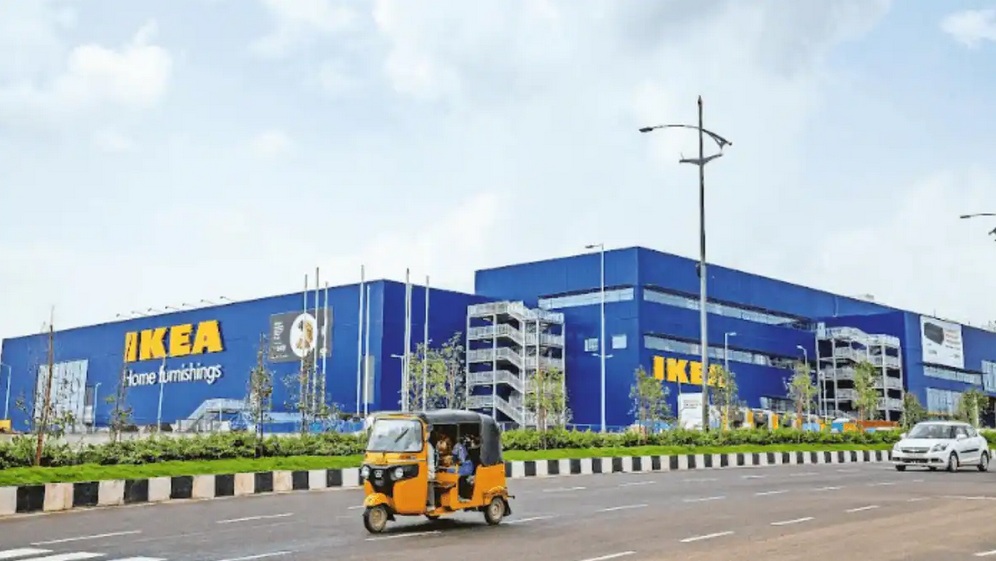
IKEA HAS BEEN around in India for about eight years, with another three years before that spent studying the market. It has developed a range that it deems “locally relevant-like the roti maker, the tava (pan), the belan (rolling pin), and the pressure cooker -which now constitute about 50% of the products it offers in the country. It has shifted its communication strategy to sync with local culture and fit into local spaces and has worked hard to beef up its omnichannel sales model with about 30% of its sales originating online. But profitability has remained elusive for the retailer whose global sales reached approximately €45billion in the 2015 financial year (FY25).
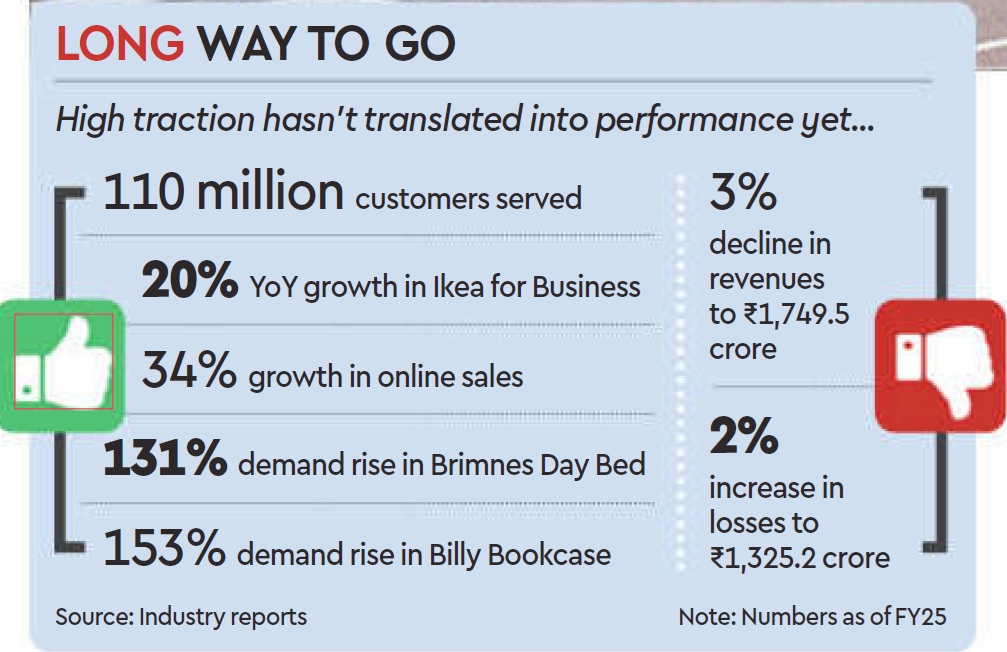
Just for context, the company’s India entity widened its losses by about 29 to 1,325.2 crore in the financial year ending March 31, 2025 (FY25). The revenue also dipped 3 to 1,749.5 crore from 1,809.8 crore in FY25.
So now the brand is taking a leaf out of its China playbook and tweaking its retail formats. Starting last year, it started piloting smaller store sizes ranging from 15,000-20,000 sq ft that are more cost-effective to set up and faster to integrate with its omnichannel model. “The goal is to create a simpler and more efficient shopping experience,” Ingka Group Retail Manager Tolga Oncu had said when the concept was unveiled last August.
Five months on, the furniture retailer is looking to take a step up the ladder – setting up new stores in the 50,000-70,000 sq ft range in the country, which will sit comfortably between its smaller stones (15,000-20,000 sq ft) and big box retail outlets (4 lakh sq ft), Adosh Sharma, country commercial manager at Ikea India told FE recently. Ikea’s broader plan also includes doubling its investments in the country to over 20,000 crore ($2.2 billion) over the next five years and improving local sourcing.
Will all this help the retailer grab a larger share of the highly fragmented furniture and furnishing market in the country? Will the brand achieve profitability in the next two years in keeping with its plans?
Ikea realises copy-pasting its global retail strategy in India is not going to work. That explains its recent moves to tweak store sizes and product design. Over and above the regular 5-M-L strategy, the fourth format the brand is developing comprises no-frills planning and order points, focused on customers who want to design homes or seek complex solutions without distraction.
“Smaller stores, which fulfill purpose-led needs will help them to get closer to their customers,” says Devangshu Dutta, founder & CEO, Third Eyesight.
The furniture and home decor segment has been up against slow purchase cycles in India. Smaller sized stores that are closer to residential arras might help step up the frequency of purchases. “Players are moving towards a higher purchase frequency strategy and smaller stores will help lkea cash in on this opportunity,” says Kushal Bhatnagar, associate partner, Redseer Consultant Strategy. He says quick commerce has helped improve the purchase cycle in the home decor space, and that is something Ikea will likely tap going forwand.
Dutta says Ikea has taken a long-term view on India and the investments in the pipeline is an indication of the opportunity that awaits players.
The brand claims it has served close to 110 million customers in FY25 across channels, and online sales are growing 34% compared to the previous fiscal. While furniture contributed the lion’s share of its revenue, the food business contributed 100% and Ikea for Business (tailored solutions for businesses) another 19% to its topline.
(Published in Financial Express)
admin
December 7, 2025
Gargi Sarkar, Inc42
7 December 2025
The past year has been nothing short of monumental for LensKart — from reporting another operationally profitable quarter in Q2 FY26 to making the public markets leap in November, and crossing a market capitalisation of INR 70,000 Cr despite a muted stock market debut.
A clear shift this year has been Lenskart’s effort to move beyond the image of a ‘basic D2C eyewear’ brand selling prescription glasses and sunglasses. The company is now working to reposition itself as a new-age tech brand.
Further, Lenskart is rethinking where and how its products are manufactured. Currently, around 20–25% of its frames are reportedly manufactured in India. The company is ramping up its domestic production. As a new manufacturing facility in Telangana is a work in progress, Lenskart intends to gradually shift most of its manufacturing operations from China to India.
In many ways, 2025 has been about scaling up for Lenskart, and as it embarks on a fresh journey as a publicly listed company, let’s take stock of the company in 2025 and where it might be headed in 2026.
Lenskart’s Smart Eyewear Bet
Lenskart began its smart eyewear journey last year with the launch of Phonic, its audio glasses. It later deepened its push into the segment by announcing a strategic investment in Ajna Lens, a Mumbai-based deeptech company that develops AI-powered XR glasses. Back then, Peyush Bansal described the move as the “next chapter” in Lenskart’s smart glasses journey.
Cut to December 2025, the company is all set to launch its AI camera smartglasses, B by Lenskart, by the end of this month.
What makes B by Lenskart noteworthy is that it isn’t being marketed as just another pair of smart glasses. The new eyewear features an integrated Sony camera that enables hands-free photo and video capture. The glasses come with a built-in AI assistant powered by Gemini 2.5 Live. They are designed to offer natural, conversational interactions and pack in a range of advanced features — from hands-free UPI payments and live translation to wellness insights and more.
What makes the move even more significant is Lenskart’s decision to open B by Lenskart to India’s developer ecosystem. By making its AI and camera technology accessible to consumer apps and independent developers, the company is enabling integrations across categories such as food delivery, entertainment, and fitness.
“By opening its AI smartglasses to third-party developers, Lenskart is moving from a one-time product-sale model to a platform ecosystem model. In the long run, this could unlock recurring revenue streams and higher margins,” said a product developer.
Besides, the company is aligning itself with a younger customer cohort, aided by affordability, style, and technology.
“That’s what seems to define their current strategy. Over time, they’ve also brought in elements of innovation like virtual try-ons, and any product, feature, or service that brings novelty and appeals to younger customers has become part of their brand approach,” said Devangshu Dutta, the founder of Third Eyesight.
Next, the timing couldn’t be better for Lenskart to place its bet on smart glasses. An IDC report reveals that despite a slowdown in smartwatch and earwear segments in the second half of 2025, smart glass shipments shot off more than 1,000% over the last year.

However, it’s not going to be smooth sailing from here.
At its core, Lenskart is still a consumer-facing company, and it needs new products to keep its revenue growing. But the competition is already heating up. Jio unveiled its own AI-powered smart glasses, Jio Frames, at Reliance Industries’ 48th annual general meeting. And of course, Meta continues to lead the global smart glasses market.
At this point, smart eyewear is a niche category, which comes with a hefty price tag.
“Unless cost drops dramatically, mass adoption is still a distant dream. As of now, the product will only attract early adopters and tech enthusiasts, rather than the mainstream consumer,” Dutta adds.
Lenskart’s Make In India Push
Lenskart is not only widening its product range but also ramping up its manufacturing. The company currently operates centralised manufacturing facilities in India (Bhiwadi in Rajasthan and Gurugram in Haryana), Singapore, and the UAE. It also has manufacturing operations in China.

Back home, Lenskart has also signed a non-binding MoU with the Government of Telangana for setting up a greenfield manufacturing facility for optical glasses. The proposed investment stands at INR 1,500 Cr and will be supported by certain incentives and assistance from the state government.
The new production facility is expected to strengthen Lenskart’s domestic manufacturing capabilities while reducing its exposure to foreign exchange fluctuations and import-related volatility.
However, the expansion comes with its own set of challenges. While the new manufacturing plant in Telangana is expected to strengthen Lenskart’s vertical integration, it will come with a hefty cost burden.
Profitability Still A Troubling Question
The cost structure is becoming increasingly important for Lenskart. Despite its headline-grabbing profitability, the company is still operating on fairly thin margins.

Lenskart reported a net profit of INR 297 Cr in FY25, a notable turnaround from a loss of INR 10 Cr in FY24. However, market analysts caution that the business’ core operations were unprofitable. It was largely “other income” or investment income that drove the FY25 bottom line.
“Though Lenskart has increased its revenue from INR 3,789 Cr in FY23 to INR 6,651 Cr in FY25, the company’s profitability has largely improved due to a rise in other income. While it reported a PAT of INR 297 Cr in FY25, a closer look shows that the profit was driven significantly by an increase in other income, which jumped to INR 356 Cr in FY25,” SimranJeet Singh Bhatia, senior research analyst for equity at Almondz Group.
The point of concern here is that Lenskart turned operationally profitable only after its market debut. Bhatia believes that at least three to four quarters of consecutive profitability will be needed to prove the company’s underlying strength.
However, making matters worse are the company’s climbing expenses, which stood at INR 1,980.3 Cr in Q2 FY26, up 18.5% YoY.
What Lies Ahead?
The year was equally sour for the eyewear major. While its IPO generated significant buzz and saw strong subscription levels, its market debut turned out to be a muted affair.
At the upper end of its INR 382 to INR 402 IPO price band, the public issue implied a price-to-earnings (P/E) multiple of roughly 235–238 times its FY25 profits, placing it among the most expensive consumer tech listings in India.
On its first day of trading, Lenskart Solutions Ltd. was listed on the NSE at INR 395 per share, a discount of 1.74% to the issue price of INR 402. The stock, however, fell close to 9% shortly thereafter. On the BSE, it debuted at INR 390, marking a discount of nearly 3%.
After the IPO, Bhatia adds, the biggest concern surrounding Lenskart is the store-level unit economics, particularly because a significant share of the IPO proceeds is being directed toward expanding its company-owned, company-operated store network.
Entering the new year as a public company, Lenskart will have to prove that its scale-up plans are justified and that it has greater control over its balance sheet. 2026 will be a critical juncture for the company, as the next three to four quarters will be closely watched for signs of sustainable growth, improved margins, and stronger operational discipline.
[Edited by Shishir Parasher]
(Published in Inc42)
admin
September 24, 2025

Shabori Das & Sagar Malviya, Economic Times
Bengaluru/Mumbai, 24 September 2025
Chinese fast-fashion platform Shein plans to triple the number of launches in India and shrink its design-to-launch timeline by a third to deepen its push into an increasingly competitive market, a top official said.
The company, which re-entered India through a partnership with Reliance Retail in February this year, said it is overhauling its supply chain to enable faster turnaround times. To achieve this, it has moved away from large-scale manufacturing hubs to smaller production lines with each line focused on creating a single new design daily.
“Our current timelines, measured from ‘thought to site’, stand at 46 days. We are targeting 30 days,” said Vineeth Nair, chief executive of Reliance’s fashion platform Ajio that steers Shein in India. “We currently deliver 320 styles a day – about 10,000 a month – and plan to scale that to over 30,000 styles monthly in the coming months,” he told ET.
Speaking about the speed of manufacturing, Nair said, “We quantify our options in terms of production lines, with each line optimised to deliver one design option per day, rather than factories. Some of our large production units have been repurposed into multiple lines.”
Shein first launched in India in 2018 with its own online shop. However, the app was banned by the Ministry of Electronics and Information Technology (MeitY) along with TikTok, WeChat and over 55 other Chinese apps.
One of the primary issues and controversies surrounding Shein’s India operations was the use of the consumer data by the Chinese apparel retailer.
Under the current partnership model, Reliance Retail is operating Shein under licensing agreement and ensures complete customer data ownership as per the company.
Unlike international markets, Shein India products are made in India.
“It’s still early days – just about three months since we introduced Shein to the India Gen Z,” Nair said. “And we are still in the process of adding multiple products, which we intend to do in the next few months.”
He said the brand is witnessing two million daily average users, dominated by 21-year-old women who account for 62% of the traffic.
Shein, the world’s biggest ecommerce-centred fashion retailer, however, may find it hard to replicate its global success in India, according to Devangshu Dutta, founder of retail consulting firm Third Eyesight.
“Shein’s edge internationally has been its speed of dropping its products, and the width of its product category. The India model is not the same. The India model of fashion is slower, and the product category width is not as large,” he noted. “Hence, the brand will in all probability end up competing with the already established market like Myntra, Zudio and the likes.”

(Published in Economic Times)
admin
September 22, 2025

Christina Moniz, Financial Express
22 September 2025
It is already the largest player among organised fumiture makers with over 15% of the market. With 1,000 stores, it has the widest retail store footprint among organised players. The 102-year-old brand is also the second-largest revenue con-tributor to the parent enterprise.
So why is Interio tinkering with its name, logo and colour attributes?
“We want to move away from being viewed as a functional brand to more of a design-led lifestyle one. We have a wider range of offerings that are more modular and aesthetic,” says Reshu Saraf, head of marketing communications at Interio by Godrej.
As a first step, it has a new logo and name change – from Godrej Interio to Interio by Godrej. The brand has earmarked ₹50 crore towards an integrated campaign across TV, digital, outdoor and in-store branding to promote its new proposition over the next year. Overall, it will invest ₹300 crore in expansion and technology with the goal to more than double revenues to ₹10,000 crore by FY29.
Younger consumers don’t see furniture as utility but as lifestyle, observes Puneet Pandey, strategy head and managing partner, OPEN Strategy & Design. “By moving from ‘solid and sturdy’ to ‘stylish and aesthetic’, the brand earns the right to play at higher price points as well. Design-led positioning will also unlock repeat purchase since people no longer wait a decade to change their furniture based on utility; they want constant upgrades to refresh their living spaces as their tastes evolve,” he notes, adding that Interio needs to make the marketing leap from “catalogue to culture”.
Saraf says the brand is also building differentiation with its customer experience. “We’re using digital tools for store walkthroughs and visualisers to help visualise our products in the home. Our product portfolio, which is deeply personalised ane tailored for Indian sensibilities, it is a major differentiator that few other brands offer,” she points out.
E-commerce is also a focus area with the brand looking to increase the revenue share from 15% to 20-22% by 2029. The company is leveraging Al to improve the search functionand sharpen personalisation. Saraf adds the that offline too, the brand will have large format experience centres to help people envision what their rooms could look like, along with mid-size and small-format stores.
Interio also plans to widen its retail store footprint from 1,000 to 1,500 by 2029.
As per industry estimates, the Indian furniture market is set to grow at 11% annually to reach $64.1 billion by 2032 from $30.6 billion in 2025. It is this growth momentum that Interio is looking to cash in on.
Built-in differentiation
Although a significant chunk of Interio’s business comes from its home remodelling services, within the furniture category, it competes with global players like IKEA and digital-first brands like Pepperfry. The challenge for Interio in this market is to embed the design-led positioning in its productsandcus-tomer experience, says Nisha Sam-path, managing partner at Bright Angles Consulting.
One of its biggest advantages is the Godrej brand. “The Godrej brand stands for many values prized in interiors such as quality, trust, reliability and durability with a ‘Made in India’ tag. However, the brand has not been so successful in building an image of cutting-edge design and innovation. These are new values that can make the brand more contemporary,” she remarks.
Devangshu Dutta, CEO of Third Eyesight concurs, pointing out aside from nimble competition, Interio’s key challenges also come from the dual pressures of increasing consumer expectations for rapid delivery and customisation on the one hand, with aggressive price competition on the other.
(Published in Financial Express – Brandwagon)
