admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
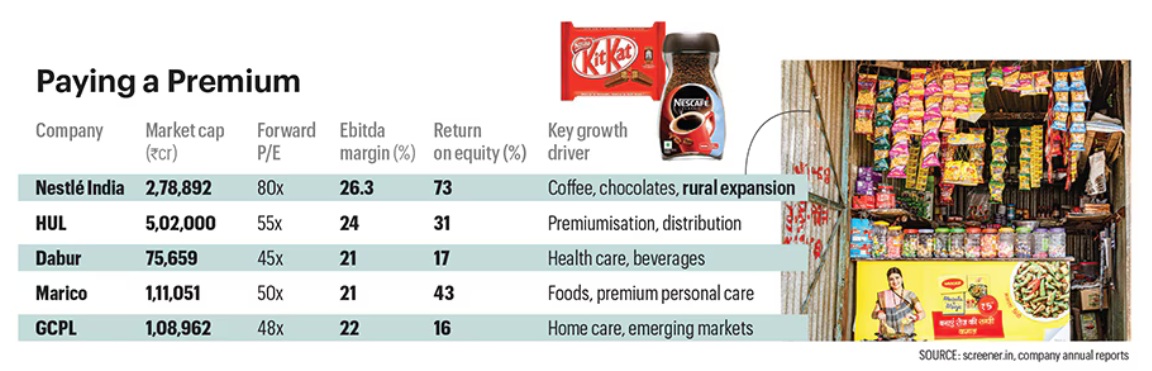
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
admin
June 8, 2026
Arushi Jain, The Times of India
8 June 2026
Their faces have launched many campaigns and brought crores to the film industry. But can they sell a moisturiser as successfully? India’s beauty market is the hottest growth story globally, estimated to reach $40 billion from $23 billion (2026) and eyeing the fourth-largest spot by 2030 (currently at number seven).
Last month, Estée Lauder announced the buyout of Forest Essentials, one of India’s oldest, Ayurveda-based brands. In 2025, Hindustan Unilever acquired five-year-old skin and hair care brand, Minimalist. A 2025 McKinsey & Company x Business of Fashion survey found that 78% of global beauty executives see India as the most promising growth market. Even celebrities have shown up with chequebooks, but fans are no longer buying at face value.
While Hailey Bieber’s Rhode built a cult following through what she calls an “outside of the box” strategy, Deepika Padukone’s 82°E reported a 30% revenue dip in FY25. Nykaa is in talks to acquire a stake in the brand.
India’s consumer has evolved faster than the brands serving them. They are reading labels now, not just recognising famous faces on packaging. Star power, it turns out, only gets you so far.
Fame gets you in the door. Formulation keeps you there
If a celebrity is the invitation to the party, formulation is what keeps the guest at the after-party. Despite India’s celebrity beauty segment crossing an estimated `5,000 crore in GMV in FY24, scale has not translated into customer retention. The initial spike, familiar to anyone who has tracked a celebrity launch, gives way to an uncomfortable question: what brings a customer back?
“Celebrity isn’t necessarily a sustainable brand asset,” says Devangshu Dutta, CEO of retail consultancy Third Eyesight. “While celebrities can act as interest-creators and trial-generators, repeat purchases are built on functional reasons, not imagery alone.”
Founders echo the same reality from the ground. “Honestly, people come back for what works,” says Aashka Goradia Goble, co-founder of RENÉE Cosmetics. “If a product performs well, feels easy to use, is priced right, and becomes part of someone’s everyday routine, they’ll keep reaching for it.”
Price, too, remains a decisive filter. Sunny Leone, founder of StarStruck, says, “In India, price is the main component.” The journey from first purchase to loyalty is driven by habit, and habit, in beauty, is built on results.
Positioning over popularity
The gap between a viral campaign and a repeat purchase is wider than most A-listers realise. Brand guru Harish Bijoor locates the problem in what he calls the “spinal cord” of a brand: a single, clear positioning that holds the entire business together.
Rihanna’s Fenty is inseparable from its commitment to shade inclusivity. Kylie Jenner’s Kylie Cosmetics was built around one obsession: lips. “It is extremely important to understand what you want to be and focus on just one thing and not on everything,” Bijoor says. That clarity is precisely where most Indian celebrity beauty brands are still finding their footing.
The old playbook: launch a brand online, wrap it in the language of “clean” or “natural,” and wait for a global conglomerate to come calling has run its course. Today, strategic buyers and consumers alike want a brand that can stand on its own. The question is no longer whether a celebrity can generate awareness. It is whether the brand they have built can survive them.
What the labels that last have in common
The brands breaking through are doing so quietly and methodically. In a category where fame can spark interest but not always guarantee repeat purchase, Katrina Kaif’s Kay Beauty, launched with Nykaa in 2019, has emerged as one of celebrity beauty’s more consistent success stories.
The main reason is less about star power and more about strategy. “If you contrast Kay Beauty and 82°E (Deepika Padukone’s brand), Kay Beauty has two distinct advantages,” says Dutta. “Firstly, being priced for a much larger audience, and secondly, having the active participation of Nykaa across channels in terms of merchandising and visibility push for the brand.”
Nykaa is candid about what made the difference. “When we co-created Kay Beauty with Katrina, shade ranges and formulations designed for Indian skin tones and climate were severely limited,” a spokesperson shares, adding that the celebrity association “amplified the brand rather than substituted for it.” The strategy appears to have paid off: Kay Beauty is now a ₹500 crore-plus annualised GMV brand, with new launches contributing 21% of revenue as of Q3 FY26.
Why Indian skin demands more than a famous name
For Indian celebrity brands, the challenge is not just performance; it is perception. “Domestically, we see the mentality for buyers is to look at international brands first based on trust, and then try domestic brands based on lower price value,” says Leone.
Indian consumers are also highly specific in what they expect. According to market research firm Mintel, shoppers are increasingly drawn to formulations that are clinically tested and grounded in both science and local familiarity. Products must perform in Mumbai’s humidity and Delhi’s pollution and suit the full spectrum of Indian skin tones.
“Indian consumers love products that do more than one job, last long in our weather, and actually match Indian skin tones,” says Goradia. They are cautious spenders, she adds, but willing to invest when they see real quality and innovation.
Nykaa says this ingredient awareness is now visible across the country, not just metros. “Consumers are reading about niacinamide and retinol, they know what they want from a sunscreen, and are making considered purchase decisions. Brands need to earn their place on merit in every market,” says the spokesperson.
“A brand that addresses these needs well and remains within the customer’s budget succeeds,” says Dutta.
Gen Z will drive 50% of India’s beauty consumption by 2030
By 2030, Gen Z will drive 50% of India’s beauty and personal care consumption, a third of all sales will happen online, and per capita income is forecast to rise 138% in real terms by 2040, according to Euromonitor. Nykaa founder and CEO Falguni Nayar told Bloomberg that comparing India’s beauty routines to South Korea’s famed 14-step regimens is premature, “It is still day zero for beauty consumption in India.”
The global conglomerates have done the math. Estée Lauder, L’Oréal, and Puig are all moving deeper into India, betting on a consumer who is younger, more digitally fluent, and more ingredient-literate than any previous generation. The brands they are acquiring, Forest Essentials, Minimalist, Kama Ayurveda, share a common thread: They are built on something that exists independently of a famous face. “This is an industry that is very crowded and takes a lot of time to grow,” says Leone. “Western brands focus on global distribution and profit and loss. Not just turnover at a loss.” The celebrities who will build something lasting are the ones who understand that the launch is the easiest part. As Bijoor puts it: “Celebrity beauty is not skin deep at all. It is a deep brand science.”
(Published in The Times of India)
admin
May 2, 2026
Neethi Lisa Rojan, Mint
2 May 2026, Mumbai
Fast-moving consumer goods makers are leaning on a mix of price increases, smaller pack sizes and tighter cost controls to navigate raw-material volatility triggered by the ongoing US-Iran war, while still reporting robust volume growth for the March quarter. The ongoing war blew up end February this year, disrupting global supply chains.
Executives at top firms said calibrated pricing and ‘shrinkflation’ are helping them protect margins. The trend shows staples demand have held up, but also points to a gradual pass-through of higher commodity and packaging costs to consumers as geopolitical disruptions keep input prices elevated.
At Hindustan Unilever Ltd, the strategy is already in motion. The company has implemented calibrated price hikes and adjusted grammage across products. “We are taking calibrated pricing action in the range of 2-5%,” chief financial officer Niranjan Gupta said in a post-earnings briefing on Thursday. “We use a combination of both the put-down price as well as optimizing the fill levels,” said Gupta. The management also noted that its products in the homecare segment such as soaps (Lux, Pears, Dove, etc.) and detergents (Surf Excel, Rin, etc.) will be the first to be affected by price hikes. Interestingly, this happened at a time when HUL’s volumes grew the fastest in 15 quarters.
Companies have anticipated how consumers will behave.
“In times of inflation, income uncertainty, etc. essentials such as packaged foods, biscuits, and household cleaning products tend to see trade-down behaviour rather than outright disappearance of demand,” said Devangshu Dutta, founder of management consultancy, Third Eyesight. “Consumers tend to shift to smaller pack sizes or private labels, rather than abandoning categories altogether,” he adds.
India’s retail inflation rose from 2.75% in January 2026 to a 10-month high of 3.40% in March, driven largely by food prices.
That balance between pricing and demand is playing out across the sector. Nestle S.A., the parent company of the Indian entity said it saw 3.5% organic sales growth during the quarter, with RIG (real internal growth or volume growth) of 1.2% and pricing of 2.3% in the January-March quarter.
“The conflict in the Middle East will have some impact on commodity and distribution costs, and possibly on consumer behavior. But it’s too early to know the full extent of this,” chief executive officer at Nestlé S.A, Philipp Navratil said in the analyst call after the results. Its India unit, Nestlé India, reported its strongest quarterly growth in nearly a decade, led by double-digit volume expansion.
HUL reported a 21% year-on-year rise in consolidated net profit to ₹2,994 crore, while Nestle India saw net profit up 27% at ₹1,110.9 crore. year-on-year to ₹1,110.9 crore in Q4 FY26. HUL has also retained its medium-term guidance for earnings before interest, taxes, depreciation, and amortization (Ebitda) at 22.5%-23.5%.
The resilience in volumes comes even as input costs surge. Prices of crude oil-linked materials, especially packaging, have risen sharply following disruptions around the Strait of Hormuz chokepoint. High-density polyethylene, widely used in packaging, jumped about 42% in March from the previous month.
Multinationals are already bracing for the fallout. Tide and Gillette maker Procter & Gamble, said in its quarterly earnings call that it could take roughly a $1 billion post-tax hit to its fiscal 2027 profit from surging oil prices. Still, not all inputs are moving in tandem. Prices of staples such as wheat, sugar, tea and coffee have remained relatively stable, offering some cushion. Edible oils, however, remain a concern.
Palm oil, a critical input in many FMCG products, is seeing supply shifts, as producers such as Malaysia and Indonesia divert output toward biodiesel. AWL Agribusiness, which sells Fortune oil, said in the quarterly analyst call that edible oils faced a 10% price surge in March, which has already been passed to consumers. The company expects to pass on the rise in packaging material prices also soon. The company posted a 53% jump in consolidated net profit to ₹292 crore in Q4FY26, from ₹190 crore a year earlier.
Experts expect the trend of margin-saving strategies to continue.
“Depending on the product, category and brand, we will see a mix of price hikes, shrinkflation and rationalization of SKUs (stock keeping units), and also a shift from brand-related to tactical advertising and promotional spends to boost short-term demand,” Dutta said.
Elsewhere, companies are acknowledging broad-based inflation but are continuing to push through growth. Bajaj Consumer Care reported near double-digit volume gains even as managing director Naveen Pandey noted that “nearly 100%” of its cost base is under inflation. The company plans further pricing actions alongside cost optimization. Bajaj Consumer Care’s net profit for the March quarter more than doubled to ₹63.6 crore from a year ago.
Beyond the basics
The ripple effects extend beyond staples. Fashion, lifestyle and grocery retailer Trent Ltd flagged uncertainty around supply chains and inflation, warning of potential implications for near-term demand. “Duration and intensity of disruptions in the Middle East, along with its second order effect on supply chain, commodity prices and inflation in general has potential implications for near-term demand,” the company said in its results presentation.
Meanwhile, consumer appliance maker Havells India has initiated price increases after what chairman Anil Rai Gupta described as an unprecedented escalation in input costs. “I’ve not seen this kind of a price escalation in the recent past in the recent memory,” he said in the post results analyst call.“ Calibrated price actions have been initiated, he said. Havells India reported a strong 40% year-on-year increase in net profit to ₹723 crore in the March quarter.
More clarity may emerge as additional earnings roll in. Companies with higher exposure to West Asia, such as Dabur and Emami, are yet to report results and could face greater consolidated impact due to regional disruptions. “Companies such as Dabur and Emami will be more affected at the consolidated level due to issues in the MENA or Middle East and North Africa Region (6-8% revenue salience),” said analysts at Motilal Oswal Financial Services ahead of the earnings season.
For now, inventory buffers are offering temporary relief. Some companies have built raw-material stockpiles lasting up to six months, helping them absorb immediate shocks. “In our international markets, our effect will be in the raw material, practically zero to a couple of points maybe because we are well-stocked not just for this quarter, but the next quarter also. We normally carry six months inventory in international,” said Raj Pal Gandhi, whole-time director at Varun Beverages, the largest bottler of Pepsico in India, in the quarterly analyst call. This has helped the firm tide over the challenges in plastic shortage faced in March.
However, companies will now have to buy raw materials at higher prices, leaving room open for more price hikes.
(Published in MINT)
admin
May 1, 2026
Yuthika Bhargava & Vikash Tripathi, Outlook Business
Mumbai, 1 May 2026
For generations of Indians, the word Tata hasn’t just been a brand, it has been a permanent resident in our homes. Think back to the kitchens of your childhood. It was the familiar packet of Tata salt, the Desh ka Namak, that seasoned every meal. It was the steaming cup of Tata tea that signalled the start of the day for elders at home.
In every Indian household, the name represents trust and legacy.
Yet, when N Chandrasekaran, chairman of Tata Sons, wanted to hire Whirlpool India’s head Sunil D’Souza to lead Tata Global Beverages (TGBL) in September 2019, he got a shock refusal.
Who in their right minds wouldn’t want to join a Tata company?
Well, D’Souza hadn’t heard much about TGBL. In fact, his colleague at Whirlpool India had called it a “sleepy company”.
At the time, TGBL’s revenues were a meagre ₹7,408cr compared to close to ₹50,000cr and ₹40,000cr logged by fast-moving consumer goods (FMCG) heavyweights ITC and Hindustan Unilever (HUL), respectively, in 2018–19.
Experts had noted TGBL had not much to show in terms of major product innovation for years. Primarily a tea and coffee company, it was locked in a low-growth cycle.
In 2018, various analysts had remarked that TGBL’s growth was muted as it wasn’t selling anything beyond tea and coffee.
At TGBL’s annual general meeting on July 5, 2018, Chandrasekaran said the company would exit loss-making subsidiaries and focus on profitable ones that can be scaled up. “Even though in volume terms, the company continued to be number one in the Indian market, the same was not true in value terms,” he said.
So, D’Souza’s immediate “no way” to the job offer was justified. TGBL wasn’t on his radar or anyone’s at the time.
But the headhunter convinced him to meet Chandrasekaran.
This meeting, says D’Souza, made all the difference for him. He recalls the Tata Sons’ chairman saying “I have the money. But I don’t have the team to run it.”
But the clincher for him was Chandrasekaran’s larger plan to foray into the FMCG space and the intent to disrupt the market.
In December 2019, Tatas announced D’Souza’s appointment as managing director and chief executive effective April 2020. One more important addition to this FMCG team was Tata Sons’ Ajit Krishnakumar as chief operating officer.
What followed was the duo’s visits to Mumbai, Bengaluru and Gurgaon. They walked to distributor offices and kirana stores and sat through market visits. “We drew out in great detail what we wanted this company to look like,” says Krishnakumar.
The mandate from Chandrasekaran was simple. He wanted a company commensurate with the Tata name, one that shared the same shelf space as the likes of HUL and ITC.
Humble Beginnings
The mission to become an insurgent company in the FMCG space kickstarted with the formation of Tata Consumer Products (TCPL) in February 2020 by merging TGBL’s tea and coffee units with Tata Chemicals’ salt and pulse businesses.
However, with established FMCG rivals like HUL, ITC and Nestlé India, D’Souza and Krishnakumar had their tasks cut out. The competition had a century of headstart in India.
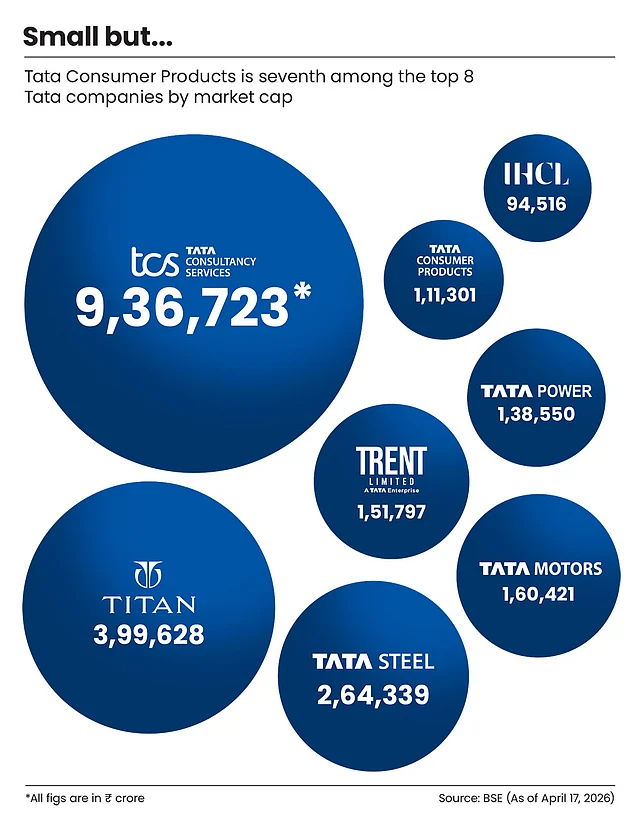
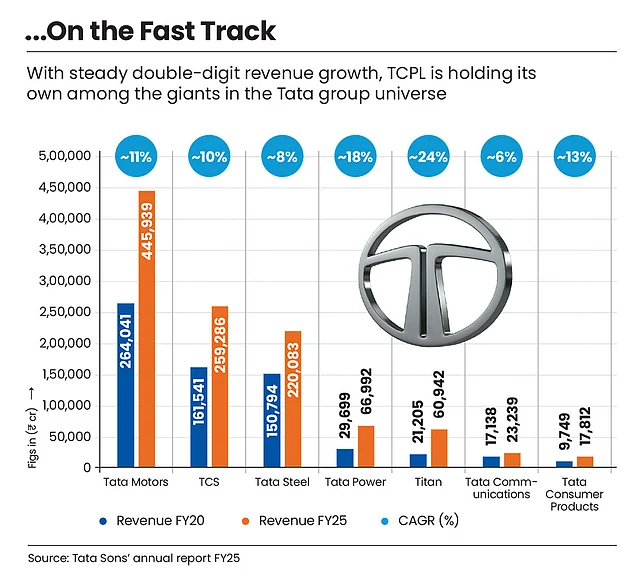
Within the Tata group itself, TCPL ranked eighth by revenue in 2019–20, behind Tata Motors, TCS, Tata Steel, Tata Power, Titan, Tata Communications and even Tata Chemicals.
But “things couldn’t get any worse than this, right? We were already at the bottom of the heap in FMCG. You could only get better,” recalls D’Souza about his mindset at the time (see pg 24).
Building a brand name as a Tata company opens doors. But competing is another. Could this new company take on HUL, Nestlé and ITC?
TCPL started by trimming the portfolio, streamlining the consumer products businesses spread across five continents, from India and the US to the UK, Canada, South Africa and Australia.
In Australia, the company held a 7% share of the tea market but was also running an out-of-home coffee dispensing business that was losing millions of dollars. It was shut down in December 2020.
In the US, a food-service joint venture, including a tea factory and a distribution unit, was disposed of as well in March 2021.
“We had 45 legal entities. That’s not tenable,” D’Souza says. “We exited areas where we didn’t see value. The focus clearly shifted to not just the topline, but margins.”
Six years later, TCPL’s entity count stands at 25 and is well on the way to the target of 18 entities.
What stood out in the next six years is TCPL’s sole focus to dominate the food and beverages (F&B) category. The company’s mantra: think big, move fast.
By late 2020, once the initial scramble post the merger had settled, TCPL ran a strategic exercise called Project Falcon. The result was a playbook: categories to foray into, categories to stay out of, where to build and what to buy.
The year 2021 provided a starting point for TCPL. In March that year, the United Nations officially declared 2023 as the International Year of Millets, acting on a proposal from India. The country being the largest producer of millets, accounting for 20% of global production, wanted to raise awareness of millet’s role in improving nutrition and creating sustainable market opportunities.
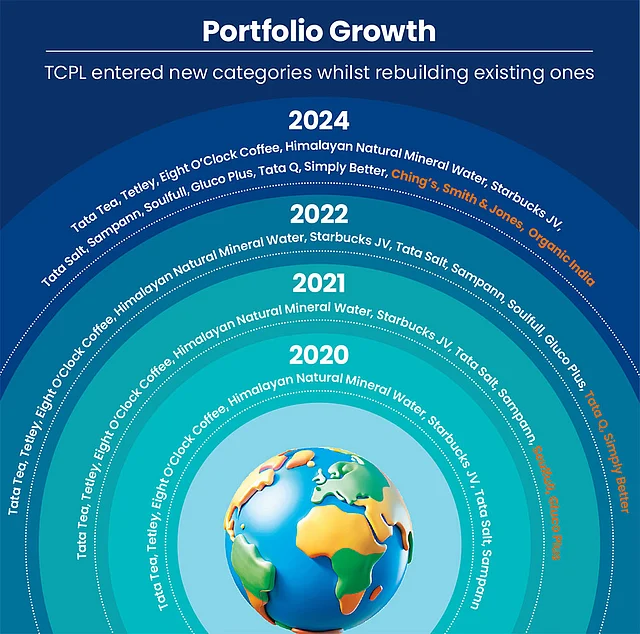
The timing was fortuitous for TCPL. In 2021, its first acquisition, Soulfull, was a millet-based health-food brand. This ₹155.8cr deal gave Tatas a foothold in a category it couldn’t have credibly entered on its own.
Within three years of acquisition, Soulfull’s distribution had grown from 15,000 outlets to 300,000, carried on the back of the Tata’s existing network.
Three years later, in January 2024, when TCPL announced two deals with combined worth of ₹7,000cr in quick succession, its stocks fell.
The market wasn’t convinced initially. TCPL had just committed roughly 40% of its annual revenue to two brands it did not build. At the time, it was a new player with its core business running on single-digit margins.
Analysts at Ambit Capital estimated the acquisitions would cut 2025–26 earnings by roughly 10%.
The first, a ₹5,100cr deal, was to buy Capital Foods, the company behind Ching’s Secret.
The second was a wellness play, a ₹1,900cr cheque for Organic India, a Lucknow-based brand with a devoted following in the US.
D’Souza had faith in these big-cheque acquisitions. “We are not playing this game for the next one or two years. We do these acquisitions knowing that we put money there. It will bear out over a period of time.”
Ching’s Secret had spent decades building the desi Chinese category in urban Indian homes almost single-handedly—the Schezwan chutney, the noodles and sauces.
As for Organic India, it had a network of farmers across Madhya Pradesh and Uttarakhand, a manufacturing facility in Lucknow and decades of Ayurvedic credibility in the American wellness market. It was built over years of relationships that TCPL simply did not have and could not quickly acquire.
And the numbers weren’t disappointing. By the third quarter of 2025–26, Capital Foods and Organic India together were generating ₹354cr in quarterly revenue, up 15% year on year, at gross margins of roughly 48%, well above TCPL’s blended average of 43%.
Motilal Oswal expects integration costs to ease substantially by 2026–27, after which the margin story should become clearer.
Fight for Shelf Space
From the get go TCPL was clear about the categories it wanted to enter and to avoid as well.
It didn’t want any stake in the basic edible-oil segment. This shelf had far too many players led by the likes of Fortune and Saffola.
But cold-pressed oil was a different ballgame. Consumers here were buying into a health claim with no way to verify if the product was trustworthy. “The Tata name does the magic there,” says D’Souza.
In August 2023, TCPL launched a range of cold-pressed oils under its brand Tata Simply Better, a new brand that was launched in 2022 to enter the plant-based mock-meat category.
The logic: find the trust deficit, fill it with the four-letter Tata name, became the basis for every category TCPL considered entering.
The sweet spot for the insurgent company was categories that were fragmented, where consumers didn’t fully trust what they were buying and where a credible brand could change the equation.
Biscuits was another category that TCPL gave a skip.
Britannia and Parle owned 56% of the market, built over decades of backward-integrated manufacturing and distribution muscle.
This restraint, wrote Motilal Oswal, in a recent note, is “rare in Indian FMCG”. Categories like biscuits, snacks, colas and base edible oils are permanently off the table, crowded segments where the Tata brand adds no meaningful trust-led differentiation. “Such portfolio discipline is a positive indicator of capital allocation quality,” the note observes.
Built organically, cold-pressed oil is now running at an annual revenue of ₹350cr. Dry fruits, another category Tatas entered with the same trust deficit logic is at a ₹300cr run rate.
What differentiates TCPL from other FMCG players?
The categories that Tatas have built or bought into are still being defined. HUL and Nestlé, on the other hand, are dominant in mature markets where penetration is already high. HUL is buying established brands in categories it rules, plugging gaps in existing portfolios. TCPL is buying into categories it has never played in, at scale, while the core business is still being built.
Whether this is disciplined offence or over-extension is a question the next two years of integration will answer.
Even before acquisitions came into play, among the first things D’Souza and Krishnakumar did was to build accountability. There had been no one person who owned a category (tea, salt or pulses) from manufacture to sales.
They created category leaders who were responsible for the product’s profit and loss, bar the fixed costs. Functions that did not exist were created.
In 2020, Tata Salt was present in nearly 2mn retail outlets across India. TCPL’s own salespeople directly visited just 150,000 of them. The remaining 1.85mn stores were being supplied through a chain of middlemen, called super stockists or consignee agents.
These middlemen picked up Tata Salt in bulk from big distributors and moved it onward through their own networks. No one from TCPL knew what was selling fast, what wasn’t or what product a rival had placed on the shelf just two rows away.
“That shows the strength of the brand and also the lack of distribution reach,” says D’Souza. In FMCG, this gap between a brand’s total reach and its direct reach is called the wholesale multiplier. It measures how many outlets are stocking your product for every outlet you directly supply. A multiplier of five is considered normal. TCPL’s was 15, a number almost unheard of.
This meant TCPL had no direct relationship with over 90% of the shops and no mechanism to introduce anything new in those shops.
“There was this big layer [of middlemen] in each state. We removed that entire layer. That layer alone was about 1.2% in terms of cost. Then we appointed proper distributors, recruited the right people and rebuilt the distribution system,” says D’Souza. This was a saving of 36 paise on every 1kg pack of Tata Salt with an MRP of ₹30.
Rebuilding the entire distribution ecosystem took six to seven months. The distributor base was cut from 4,500 to around 1,500–1,600. These distributors were now carrying the full portfolio, reporting directly to TCPL. The sales force was expanded by 30%.
The results were quick. TCPL’s direct outlet reach stands at approximately 2.3mn today from roughly 500,000 in 2019–20. The total reach is 4.4mn outlets now.
“There are two key benefits to getting closer to the retailer. It supports margins and gives you better visibility into what’s happening at the point of sale,” says Arvind Singhal, chairman of The Knowledge Company, a management-consulting company.
Progress is real. But TCPL has miles to go. HUL reaches more than 9mn outlets, built over nine decades. ITC reaches 7mn. Nestlé 5.2mn. India has roughly 12–15mn kirana stores.
“The whole premise was to create a distribution funnel through which you can then push different products,” says D’Souza.
Bump in the Road
The first real test for TCPL was whether the idea of pushing new products through the distribution funnel would work.
Pradeep Gupta, a kirana store owner in Varanasi, has been a witness that it worked. Six years ago, two products were always on his shelf: Tata Salt and Tata Tea Premium. He didn’t need a salesperson to tell him to stock them.
Now, new products from Tata Sampann spices to Ching’s Secret sauces and Soulfull rusk are on the shelves of Gupta’s tiny store. TCPL’s distribution network made it happen. A distributor who had built his business around Tata Salt would now also handle Ching’s Secret. A salesperson who knew how to move a commodity would now pitch a branded sauce.
But not everyone was happy. The All India Consumer Products Distributors Federation (AICPDF) went up in arms against TCPL in 2025. Distributors were protesting excessive targets, stocks were piling up in warehouses and damaged goods sitting for months with no settlement.
The mismatch was structural. Salt moves through wholesale with 80% of it never seeing a retail salesperson. Most of the newer growth products like Ching’s Secret are sold almost entirely through direct retail.
Running both through the same distributor was asking a man who sold salt by the tonne to also build a market for Schezwan chutney.
The AICPDF president Dhairyashil H Patil explains what went wrong. “Salt is typically sold in large volumes. Products like Tata Sampann [a packaged pulses brand launched in 2017 under Tata Chemicals] and tea are the opposite, only about 8–10% goes through wholesale. After the merger with Capital Foods, there was a complete mismatch.”
Distributors built around salt did not find it viable to handle retail-heavy products. “Most Tata distributors derive 60–70% of their turnover from salt, so their focus remains there,” adds Patil.
TCPL eventually had to take back damaged goods sitting with distributors for six to eight months. D’Souza’s response was to separate the networks entirely.
TCPL’s growth businesses like Ching’s, Soulfull and Organic India had their own distributors and sales teams in just three months. “For any other company, it would have taken at least a year or more,” D’Souza says.
Also, the portfolio TCPL had inherited gave its own answer to what the distribution funnel could carry. Sampann, a “hobby for Tata Chemicals”, arrived at the merger doing ₹150–200cr in revenue. In 2025–26, Sampann is expected to touch ₹1,700–1,800cr, with pulses alone contributing ₹1,000 crore.
“The whole DNA of the company is to stay agile and make sure to move at full speed,” says D’Souza.
Fast and Furious
TCPL moved at full speed indeed when it came to trends. In May 2019, Beyond Meat, a company that made plant-based burgers from pea protein, listed on Nasdaq. Its stock more than doubled on the first day.
Within months, McDonald’s was testing a meatless McPlant and KFC was piloting plant-based chicken. Plant-based meat looked like the future of food.
TCPL bought into the trend. In 2022, it launched plant-based mock meat under the Tata Simply Better brand. However, the global buzz died sooner than expected. Two years later, TCPL exited the category.
The exit is not the point. What matters is that the product took 150 days from concept to shelf. TCPL had built something that would have been impossible two years before.
Mock meat required food science to replicate the texture of meat from plant protein, process technology, a team of chefs, food scientists and packaging engineers.
Capabilities were built from scratch. In the beginning, the R&D team was just 10–15 people. Today, it operates across three centres: Bengaluru as the research and packaging science hub, Mumbai for food innovation and product development, and Barabanki in Uttar Pradesh, anchoring the wellness work after the Organic India acquisition.
The team remains lean, around 60 people, roughly one-third the size of comparable FMCG rivals, estimates Vikas Gupta, R&D head at TCPL.
When D’Souza arrived in 2019, just 0.8% of TCPL’s revenue came from new product launches. The industry benchmark is 5%. TCPL was nowhere close. Today, that number stands at roughly 5%.
Onkar Kelji, research analyst at Indsec Securities, a brokerage firm, frames the economics of the chase: the early returns on innovation can be thin, he says, as companies push products aggressively and launch on e-commerce where margins are typically lower than general trade. “But if these products scale, they deliver better margins over time.”
Across the industry, the contribution of newly launched products has generally stayed under 5%. With acquisitions, that mix is expected to rise, notes Kelji.
In FMCG, innovation is not only about launching entirely new categories. It is also about rethinking what already exists. “We were singularly focused on vacuum-evaporated iodised salt,” says D’Souza.
The thinking that replaced it was simpler. “Give the consumer what they want. Plain salt. Salt with iron, with zinc. Low sodium for the health-conscious. Himalayan rock salt for the premium buyer. Sendha [during Navaratri]. One product became a portfolio,” adds D’Souza.
A patented granulation technology was developed for double-fortified salt, solving a long-standing industry problem of how to add iron to iodised salt and keep it stable.
TCPL also produced the Tata Coffee Cold Coffee liquid concentrate, a first-of-its-kind product in the Indian market that lets consumers make cold coffee at home without equipment.
The first 100 product launches after the merger took three-and-a-half years. The next 100 took 16 months. At one point, the company was turning out a new product every week, each one requiring its own supply chain, packaging, shelf-space negotiation and own sales story.
For a company that was criticised in 2018 for launching almost nothing new for years, this was a different metabolism entirely. “It’s easier when you are doing everything from scratch, says D’Souza, adding “As soon as we see a trend, we are on top of it and running with it.”
E-commerce is a good example of how TCPL, weeks into its merger, took on the very real challenge of lockdown and built a new digital vertical to boast of.
Lessons from Pandemic
In March 2020, most Indians had online grocery apps on their mobile phones. These were rarely used. But the Covid-19 pandemic and subsequent lockdown reshaped this landscape.
BigBasket’s servers strained with massive order volume surge. Dunzo crashed repeatedly. Amazon Fresh ran out of delivery slots. Millions of urban Indians were struggling to restock their kitchen shelves.
At the time, TCPL’s entire e-commerce operation was one person’s part-time responsibility. The southern regional sales head looked after e-commerce. TCPL had to race against time to build a digital channel. And D’Souza’s team built it fast.
E-commerce became a dedicated function with its own head. A modern trade team was created. Every new product launch went digital first. E-commerce gave TCPL something general trade never could: unfiltered data on what actually works.
While the company’s overall innovation-to-sales ratio was 3.4% by 2022–23, it was 10% on e-commerce. Products that proved themselves online were then pushed into general trade.
“The beauty of e-commerce is that it is only you and the consumer. It is the power of your product and your brand and your value proposition,” D’Souza said in an earnings call.
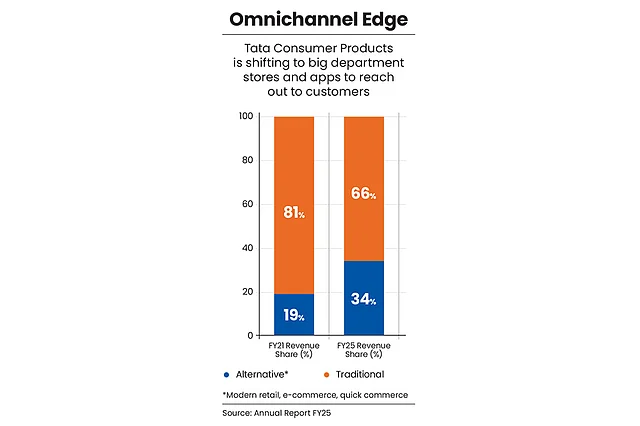
E-commerce’s revenue contribution at the time of merger was 2.5%. By late 2021, it was 7%, a growth of 130% in a single year. By 2024–25, it reached 14%, overtaking modern trade for the first time. By the third quarter of 2025–26, e-commerce and quick commerce together stood at 18.5%.
“I don’t think anyone else is in this ballpark,” says D’Souza. He is not wrong. HUL’s equivalent figure runs at 7–8%, Nestlé India’s at 8.5%. The company that almost missed the decade’s defining channel shift now leads it among its peers.
What makes the number more significant, according to Motilal Oswal, is TCPL’s margins on quick commerce are comparable to traditional channels, unlike most peers, who are seeing margin erosion on the platform.
The Tata group’s acquisition of BigBasket in May 2021 gave TCPL a window into how millions of Indians shop for groceries.
In an earlier earnings call D’Souza pointed out that BigBasket is a group company, not a TCPL asset. But within the group, he said, they were working closely to find synergies.
The channel shift also fits the company’s portfolio. Quick commerce skews toward the premium buyer: the person reaching for Himalayan rock salt at ₹100 rather than iodised salt at ₹30, Organic India’s tulsi tea rather than a commodity tea bag.
The premium end of TCPL’s portfolio, built over five years, is precisely what the fastest-growing channel wants. The mass business still dominates revenue.
Half-way Mark
In January 2021, D’Souza said, “If we get it right, the rewards would be endless. If we didn’t, we’d have to live with it for a long time.” Five years later, he rates himself “five out of 10”. Ask him what TCPL has that HUL and Nestlé don’t, and the answer is the four letters T-A-T-A.
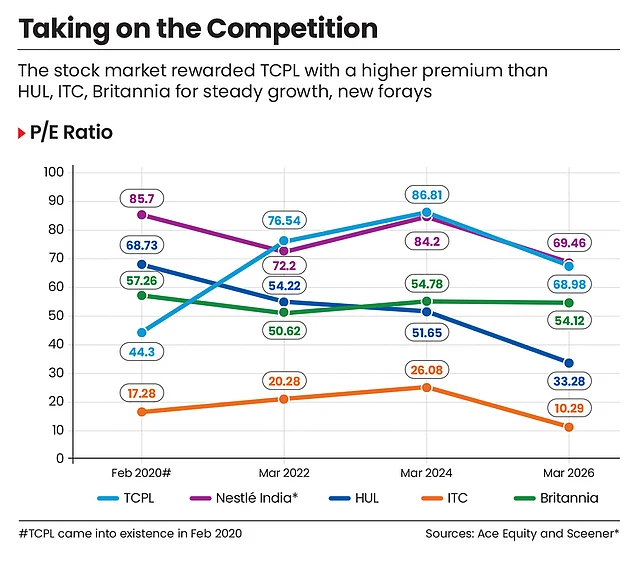
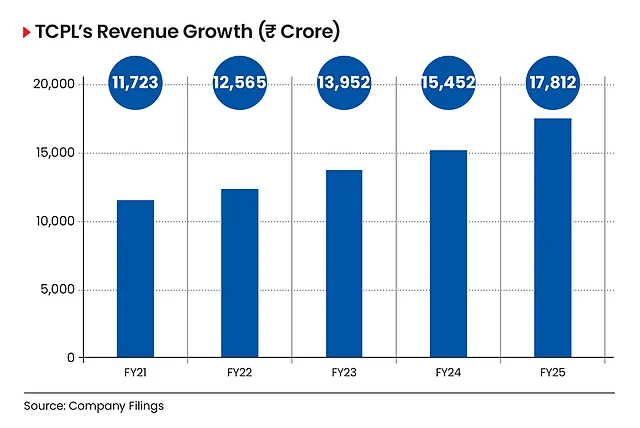
Here is what five out of 10 looks like. TCPL’s revenue has grown over 80% between 2019–20 and 2024–25. In annual terms, that is a compound rate of roughly 13%, faster than HUL’s 9.8%, Nestlé India’s 10.5% and ITC’s 9.7% over the same period, albeit off a smaller base.
TCPL reported a consolidated annual turnover of ₹17,618cr in 2024–25. Its operating margin, what survives from every rupee of revenue after paying for everything, runs at 14–15%. HUL’s is 23–24%.
Closing this gap requires high-margin businesses like Ching’s, Organic India, Soulfull, cold-pressed oil to grow fast enough to become roughly a third of total revenue. Right now, they are 8–9%.
Tea costs, which TCPL cannot control, need to normalise. Integration costs from the 2024 acquisitions need to wind down.
Motilal Oswal projects margins reaching 17% in three years. The path to 20%-plus, where HUL and Nestlé operate, is considerably longer than that.
Return on capital, how much profit a company earns on every rupee invested, tells the same story from a different angle. TCPL’s sits at roughly 10%. HUL’s is 27%. D’Souza points out that the core business, stripped of the 2024 acquisition capital, delivers 30%-plus.
The acquisitions are dragging the consolidated number while they are still being absorbed. Most analysts expect the trajectory to improve. The question is whether it does so within the timeline management has guided.
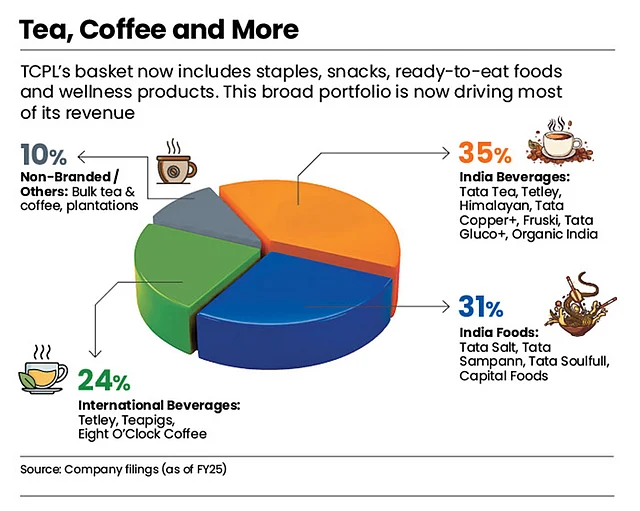
D’Souza describes the portfolio in three segments: the international business: Tetley, steady and cash-generative. The India staples: tea and salt, large but low-margin, subject to commodity costs he cannot control. And the growth businesses: Ching’s, Organic India, Soulfull and cold-pressed oil, which are small today but carry the highest margins and expectations.
“All three pieces need to come together,” says D’Souza.
“Each piece in the portfolio has a very specific purpose,” explains Krishnakumar. International for steady margins. Sampann for growth. Capital Foods and Organic India for both. “The headline target ties it together: a double-digit-plus topline and a bottom line growing higher than that,” he adds.
Today, the portfolio spans tea, coffee, water, ready-to-drink beverages, salt, pulses, spices, ready-to-cook and ready-to-eat offerings, breakfast cereals, snacks and mini meals.
However, the product range is in the food and beverages (F&B) universe. The company does not yet cover much else. “Without personal care or home care, TCPL is not yet a comprehensive FMCG powerhouse,” says Devangshu Dutta, founder of Third Eyesight, a boutique management-consulting firm.
Krishnakumar’s response is: “On a revenue basis, F&B accounts for nearly 80% of the FMCG universe. Outside of F&B, it requires a very different set of skills, a very different DNA.”
TCPL is not making bets in personal-care or home-care segments in the near future.
The Long Game
“There’s no magic breakout moment,” says Krishnakumar. What he points to instead are accumulations: salt crossing million packets a day, the stock market re-rating and the innovation pipeline turning out a new product every week.
The competition, however, is not waiting. HUL’s quick commerce is logging 3% of revenue, growing at over 100%. ITC plans to spend ₹20,000cr over five years with the bulk for foods. Nestlé is deepening its product pipeline.
These rival FMCG companies are now moving faster than they have in years. For TCPL, the race has gotten harder.
At the same time, these giant competitiors have their own challenges. HUL draws only 25% of its revenue from foods. Nestlé is concentrated in dairy and confectionery.
ITC, which is still moving away from tobacco, draws 40% of its revenue from packaged foods and personal care combined.
While these Goliaths have their attention split, TCPL’s focused approach is perhaps the one thing they cannot replicate. “In any category that we have a stake in, we would be among the top three brands,” says a confident D’Souza.
Six years in, the pieces are in place. “Our strategic road map and the strong foundation we have laid for the business have yielded good results…Our overarching ambition is to evolve into a full-fledged FMCG company,” Chandrasekaran said in TCPL annual report 2024–25.
Whether TCPL becomes big and matches his vision is a question the next six years will answer.
Within the Tata group, TCPL’s revenue ranking may not have moved much: eighth in 2019–20, seventh today. Both profits and market capitalisation have grown more than three times. It’s now worth over ₹1 lakh crore, nearly seven times Tata Chemicals, and more than double that of Tata Communications.
The market is not pricing what TCPL is. It is pricing what it might become. “Because if you’re not in the top three, there is no point,” says D’Souza. The man who chose to walk into the “sleepy company” is not done yet.
(Published in Outlook Business)
admin
March 7, 2026
Vaeshnavi Kasthuril, MINT
Bengaluru, 7 March 2026
While many consumer goods companies are acquiring direct-to-consumer (D2C) startups, Reliance Consumer Products Ltd (RCPL) is pursuing a different playbook. The consumer arm of billionaire Mukesh Ambani’s Reliance Industries has been steadily buying regional legacy brands with strong local recall. By plugging these brands into Reliance’s vast retail and distribution ecosystem, the company hopes to accelerate its ambition of becoming an FMCG powerhouse.
During the December quarter, RCPL overall gross revenue stood at 5,065 crore, up 60% year-on-year, according to an earnings statement from Reliance Industries. India’s FMCG sector remains dominated by established players such as Hindustan Unilever Ltd, which reported revenue of about 64,138 crore in FY25—highlighting the scale of the opportunity Reliance is targeting as it builds its consumer business.
“What Reliance is doing is cobbling together a portfolio of brands that already have some momentum,” said Arvind Singhal, chairman of The Knowledge Company, a Gurgaon-based management consulting firm.
Which regional brands has Reliance acquired?
Over the past few years, RCPL has assembled a portfolio of regional brands across food, beverages and personal care. One of its latest additions is Chennai-based Southern Health Foods Pvt. Ltd, which sells millet-based foods, health mixes and baby nutrition products under the Manna brand. Reliance acquired the company for about 158 crore, marking its entry into the fast-growing millet and nutrition foods segment.
Earlier, RCPL bought a majority stake in Udhaiyam Agro Foods Pvt. Ltd, a Tamil Nadu-based staples brand known for pulses, flours, spices and ready-to-cook mixes. Revenue at Shri Lakshmi Agro Foods Pvt. Ltd, which sells products under the Udhaiyam brand, rose about 5% year-on-year to 668.2 crore in FY24, according to Tracxn data.
Reliance has also acquired Delhi-based Sii, a legacy condiments maker known for jams, sauces and cooking pastes as well as Velvette, the historic personal care label that pioneered shampoo sachets in India in the 1980s.
In beverages, RCPL revived Campa Cola, acquired from the Pure Drinks Group, as a mass-market challenger in the carbonated drinks segment. It has also partnered Hajpuri & Sons to distribute regional drinks such as Sosyo, Kashmira and Ginlim, and tied up with Sri Lanka’s Elephant House to manufacture and distribute its beverages in India.
What do regional brands gain from partnering with Reliance?
Regional brands that partner with or are acquired by Reliance gain access to scale that is often difficult to achieve independently. Many local brands enjoy strong loyalty in their home markets but face constraints such as limited capital, weaker supply chains and restricted distribution networks.
Under the Reliance umbrella, these brands gain access to the group’s nationwide retail and distribution ecosystem, which includes millions of kirana stores as well as large-format retail chains operated by Reliance Retail. This enables them to expand beyond their regional strongholds far faster than they could independently.
Reliance can also improve manufacturing and supply-chain efficiencies, helping these brands scale production, strengthen sourcing and reduce logistics costs. In addition, stronger marketing capabilities and financial backing allow brands to invest in packaging, advertising and product innovation—helping them evolve from local favourites into national brands.
Why is Reliance pursuing this strategy?
For Reliance Consumer Products Ltd, acquiring regional brands offers a faster and potentially less risky way to expand in India’s vast FMCG market. These brands already have loyal customers, established products and existing manufacturing. By plugging them into Reliance Retail’s distribution network, the company can rapidly expand their reach across the country.
The strategy also allows Reliance to quickly build a diverse portfolio across staples, beverages and personal care—strengthening its ability to compete with established FMCG giants such as Hindustan Unilever and ITC.
How are rival FMCG companies expanding instead?
Most traditional FMCG companies are pursuing a different strategy by acquiring or investing in digital-first D2C brands. These startups often operate in fast-growing segments such as premium skincare, clean beauty and health-focused foods, helping established companies tap younger, digitally savvy consumers.
• Hindustan Unilever recently acquired skincare startup Minimalist, a fast-growing digital-first brand known for its ingredient-focused beauty products.
• Dabur India has also entered the space by acquiring premium beauty brand RAS Luxury Skincare through its 500-crore venture capital arm.
• Marico has taken a similar approach, investing in digital-first brands such as Beardo and Just Herbs to strengthen its presence in grooming and natural beauty.
Such deals allow established companies to quickly enter emerging premium categories.
What challenges could Reliance face in scaling regional brands?
Scaling regional brands nationally can be more complex than expanding digital-first startups. Many regional brands are built around specific local tastes, price sensitivities and cultural preferences that may not translate easily across markets. “India is very diverse, and consumer preferences vary significantly across regions,” said Singhal of The Knowledge Company.
Another challenge is that many regional brands lack the infrastructure to scale independently. “For many regional brands, the first real scaling often comes from the acquirer’s distribution rather than from the brand itself,” said Devangshu Dutta, founder of consulting firm Third Eyesight.
In contrast, many D2C brands are designed from the outset for a national or digital audience, making them easier to scale online. However, these startups often rely heavily on marketing spends and online channels, which can make profitability and large-scale expansion challenging.
For RCPL, the key test will be retaining the regional authenticity of these brands while using the nationwide distribution strength of Reliance Retail to expand them beyond their core markets.
(Published in Mint)
