admin
November 3, 2026
Pritha Pahari, The Core
3 November 2026
India’s packaged food and soap makers are running out of easy choices. Input costs have continued to rise since late February, when the Middle East conflict began disrupting supply chains and pushing up crude-linked costs.
A visible price hike, however, risks sending shoppers to a rival. To offset this, companies have reduced package sizes. However, scope for how much these packs can be reduced is limited, especially for products already sold at low price points. Take the example of a Rs 10 pack of Parle-G biscuits.
At this price, there is little room to reduce the quantity further without risking consumer dissatisfaction. Cutting the pack size could make the product less attractive, while increasing the price may discourage price-sensitive buyers.
India’s FMCG giants have squeezed pack sizes about as far as they can go. With input costs still climbing and shoppers watching every rupee, the choice between eating the cost and raising prices is coming, likely right after Diwali.
The Hikes Are In
Britannia, Hindustan Unilever (HUL), Dabur and Godrej Consumer had already raised prices by around 2-5% in the June quarter, and were weighing more for the September quarter. FMCG companies have continued to raise prices to offset higher input costs.
FMCG companies have continued to raise prices to offset higher input costs.
Tata Consumer Products increased tea prices by 8-10% between the June and September quarters, while it raised the price of its Rs 30 salt pack to Rs 32 in May and again to Rs 34 in October.
Hindustan Unilever also took price increases of around 7.5% during the September quarter, according to media reports.
Godrej Consumer Products said it would continue calibrated price increases, particularly in soaps and liquid detergents, to manage cost pressures.
Dabur has also confirmed taking pricing actions in its October business update, while Britannia had indicated a further 1.5-2% increase, largely through smaller packs. However, the latter two companies’ September-quarter results were still awaited.
Experts said that lower-income households face greater pressure because everyday essentials take up a larger share of their budgets. Affordable products such as biscuits, noodles, soaps, detergents and cooking oils are particularly sensitive to price changes.
According to experts, some manufacturers are weighing selective price increases after Diwali, possibly from December.
Shoppers haven’t walked away yet
So far, demand is holding up. Nestlé India’s sales rose 20.5 per cent to Rs 6,782 crore in the September quarter, with double-digit volume growth.
At HUL, June-quarter underlying sales growth of 10 per cent came equally from volume and price.
The market is still nervous.
Nestlé India shares closed 7.7% lower on results day after management flagged rising input costs, especially packaging, edible oils and farm commodities.
Business Standard quoted chairman Manish Tiwary as saying, “Rising inflation, particularly food inflation, is a reality.”
India’s FMCG volume growth remains mixed, although several companies continue to report resilient demand. Tata Consumer Products’ India branded volume growth eased from 16% in Q4 FY26 to 13% in Q1 FY27 and 11% in Q2 FY27.
Marico reported that India volume growth reached near double digits in Q2 FY27, following 11% in Q1.
Dabur India recorded 5% underlying volume growth in Q1 FY27, while its October update indicated double-digit revenue growth for Q2 but did not disclose a confirmed volume figure.
Overall, demand remains resilient, but revenue growth should not be confused with volume growth, particularly as companies raise prices to offset higher input costs.
Why Smaller Packs?
Satish Meena, founder of research firm Datum Intelligence, said that companies try to absorb costs first. “They can do it for one quarter, they can do it for two quarters, but at a certain point they have to pass it on to the customer,” he said. He expects much of that to happen after the festive season.
Discounts are not an option either, since margins are thin. That leaves pack sizes. “Instead of 150 grams, we are doing 120 grams, keeping the price the same,” Meena said, describing the move.
A visible price rise carries a risk of its own.
“Your positioning in the shop will change, and customers will also perceive you as an expensive product and look for other brands,” he said. Once a rival takes the shelf space, it is hard to win it back.
Devangshu Dutta, founder of research firm Third Eyesight, says price points are hard to move. “Price points are often anchored either in the consumer’s mind or by competitive benchmark pricing, making them difficult to change,” he said.
He also said the practice now carries a reputation risk. “The shrinkflation phenomenon isn’t new, but social media has given it viral visibility, which can potentially damage brand reputation.”
Pricing Pecking Order
Meena said companies will follow a set order. First they improve buying and supply chains, then trim ad spending. Next they raise prices on premium products, where buyers are more willing to pay. Raising prices across all products comes last, so they don’t lose share.
Dutta says companies are “caught in a vice” because input costs are rising while core shoppers are cautious about spending. Companies have “no option but to cut brand-level advertising and also review overheads deeply.”
Indian FMCG companies are facing rising input costs across several product categories.
In October 2026, plastic packaging costs were reported to have increased by 30–40%, putting pressure on snack makers and household-product manufacturers.
Palm oil prices rose 21% year-on-year in September, while sunflower oil increased 14%, soybean oil 9% and mustard oil 8%.
Sugar prices climbed 18% year-on-year, adding pressure on confectionery and packaged-food producers.
Tea prices rose 10% over the same period. Coffee and cocoa also recorded increases, with Arabica coffee up 19% quarter-on-quarter and cocoa rising 48%. These increases affect biscuits, noodles, chocolates, soaps, shampoos and detergents differently.
Now What?
The next test is HUL’s September-quarter results, due after its board meets on 28 October. Meena does not expect much to change in the next one to two quarters.
He says the pressure is not seasonal. “It’s because of the war happening in the Middle East… it’s a much longer issue for them,” and he points to RBI data showing some impact on demand.
Input-cost pressures could persist into early 2027.
S&P Global’s September outlook projected elevated manufacturing costs through 2027, while October data showed plastic packaging costs 30–40% higher and key polymer prices more than 50% above pre-conflict levels.
Although prices may ease if supply routes improve, these figures suggest FMCG companies could face continued cost pressure over the next two quarters.
Dutta said only a few brands will come through easily. “Few brands or products are able to build longer-term loyalty consistently and whose value to the consumer is stickier than the resistance to price movement.”
For everyone else, the room to raise prices or shrink packs is running out.
(Published in The Core)
admin
July 13, 2026
Viveat Susan Pinto, S Shanthi (Financial Express)
13 July 2026
India’s new-age coffee chains are accelerating expansion despite continuing losses, as investors bet that the country’s under-penetrated branded cafe market can deliver long-term growth.
Third Wave Coffee plans to open 100 cafes this financial year while targeting company-wide break-even. Blue Tokai aims to expand from 240 outlets to 800 by FY30 and is preparing for an eventual public listing. Nothing Before Coffee (NBC), which has grown to 114 cafes across 45 cities, plans to more than double its network over the next two years.
The expansion comes even as profitability remains elusive. Investors, however, are increasingly prioritising store-level economics over headline profits, arguing that India’s cafe market is still in its early stages of growth.
“The earlier failures in the cafe segment were largely capital-discipline failures, not failures of the category itself,” said Vish Narain, managing partner at Pulsar Capital, which is backing Blue Tokai’s international expansion.
“Chains expanded store count before proving unit economics. Investors today understand that India’s per-capita coffee consumption is still in its early stages. They are reading past shutdowns as wrong execution, not wrong thesis,” he said.
Dissecting the Balance Sheets
The numbers highlight the challenge.
Heissette Beverages, the parent of Third Wave Coffee, accumulated losses of Rs 320 crore between FY21 and FY25, while total assets stood at Rs 538 crore at the end of FY25, according to Tracxn. Muhavra Enterprises, Blue Tokai’s parent, reported accumulated losses of Rs 175 crore over the same period, with total assets of nearly Rs 370 crore. Financials for FY26 are not yet available with Tracxn.
NBC accumulated losses of nearly Rs 3 crore over FY24 and FY25 against total assets of Rs 18 crore. Mumbai-based premium chain Subko Coffee, with 16 outlets in India and one in Dubai, posted losses of Rs 45 crore over five years, while total assets stood at Rs 61 crore at the end of FY25.
Third Wave Coffee said around 90% of its outlets are Ebitda-positive and expects to achieve company-wide break-even during FY27. Blue Tokai, backed by Verlinvest, is targeting profitability by March 2028.
NBC declined to specify a profitability timeline but said it has adopted a franchisee-invested, company-operated (FICO) model to reduce cash burn while retaining operational control.
“FICO lets us expand quickly with franchisee capital while keeping operational control,” said Ankesh Jain, co-founder and chief executive officer, Nothing Before Coffee.
Structural Shifts
Experts attribute the investor interest partly to improving outlet economics as operators shift from large dine-in formats to compact grab-and-go and cloud-kitchen models.
“These formats materially cut capex per outlet and shrink payback timelines, making the category venture-fundable rather than just a slow-and-steady, self-funded business,” said Krishna Dev Pathak, investment banker and advisor to early-stage startups.
Lower capital requirements have strengthened unit economics, reinforcing investor confidence despite delayed company-level profitability.
Investors are also betting on a broader shift in consumer behaviour. Anuj Kejriwal, chief executive officer and managing director of Anarock Retail, said rising incomes, urbanisation and changing preferences are gradually moving India from “a tea economy to a coffee economy”. The shift is widening the addressable market for organised coffee chains beyond the metros into smaller cities.
Consumers increasingly use cafes as workspaces, meeting points and all-day dining destinations, prompting chains to diversify into food, desserts, packaged coffee, vending solutions and merchandise.
“The cafe model is now well established as part of consumers’ lifestyles,” said Devangshu Dutta, founder and chief executive of retail consultancy Third Eyesight.
Challenges remain. Rentals in premium locations have surged, coffee prices remain volatile, and labour and supply-chain costs continue to pressure margins.
For now, investors appear willing to fund rapid expansion, betting that disciplined execution and improving unit economics will eventually turn India’s cafe boom into a profitable business.
(Published in Financial Express)
admin
July 9, 2026
Neethi Lisa Rojan & Vaeshnavi Kasthuril, MINT
Mumbai/Bengaluru, 8 July 2026
The collapse of the US-Iran peace deal in less than a month has rattled India’s consumer sector, reviving fears that higher oil prices and fresh supply-chain disruptions could squeeze demand just as companies were betting on a broader recovery.
The renewed uncertainty followed US President Donald Trump’s declaration on Wednesday that the peace deal with Iran was effectively over, alongside Washington’s decision to end a sanctions waiver on Iranian energy supplies. The market reaction was swift. The Nifty FMCG Index fell 2.49% on Wednesday, underperforming the broader market as all 15 constituents declined, led by Dabur India, Hindustan Unilever, and Tata Consumer Products, whose shares fell 3-4% each. The benchmark Nifty50 ended 2.12% lower after renewed hostilities in West Asia pushed crude prices higher.
Executives and analysts said companies have little room to respond immediately, leaving them to closely monitor devel opments as risks to costs and consumer spending mount. “I don’t think companies can react on this kind of a short notice,” said Arvind Singhal, chairman of consulting firm The Knowledge Company. “It takes 2-6 months to make any change in your plans and strategy. I think right now the Indian FMCG (fast moving consumer goods) companies will be watching the progress of monsoon more carefully than the Strait of Hormuz.”
Even after the US-Iran peace deal took effect on 18 June, consumer companies were unlikely to have expected immediate relief, analysts said.
“While everyone hoped for a cessation in hostilities, smart management teams would work on the realistic expectation that even with a ceasefire, pent-up supply chain input costs need to be absorbed over time, and pricing plans must be factored accordingly,” Devangshu Dutta, founder and chief executive of consulting firm Third Eyesight, said.
“Given that the conflict zone is active, I don’t think there is any immediate likelihood of pricing freeze or reductions, even though demand in rural areas as well as in lower-income urban segments is likely to be hit from both sides ― earnings and expenses.”
Large consumer goods companies including Dabur, Emami and Godrej Consumer had recently told investors they remained confident about consumer demand, including in rural markets.
But the renewed rise in crude prices, coupled with erratic monsoons marked by rainfall deficit in some regions and flooding in others, threatens to complicate that outlook. Higher fuel costs could lift prices of crude-linked raw materials such as plastic packaging and ingredients used in soaps and creams, while persistent inflation could push consumers to cut discretionary apne ding and trade down even on staples.
Major consumer companies had already raised prices or reduced grammage across packaged food, beverages and personal care products in the March quarter.
“As far as the crude prices are concerned, that is probably the only variable where the government has to decide as far as pricing of crude or the petroleum in India is concerned,” Singhal said.
That comes at an awkward time for India’s largest consumer companies, including Hindustan Unilever, which had earlier this year told analysts they intended to drive growth through higher volumes rather than price increases. A renewed bout of inflation could undermine that strategy.
(Published in MINT)
admin
May 25, 2026
Vaeshnavi Kasthuril, MINT
Bengaluru, 25 May 2026
Value fashion retailers across the country are likely to face margin pressure in the upcoming quarters as rising crude oil prices are driving up the cost of polyester and other fabrics. Executives at V-Mart Retail Ltd, Vishal Mega Mart Ltd, and Kewal Kiran Clothing Ltd (KKCL) said crude oil-linked inflation has begun to push up yarn and sourcing costs across apparel and general merchandise categories, with the full impact expected to play out over the next few months.
Value fashion retailers face a double whammy: their heavy reliance on polyester and synthetic blends exposes them to crude-linked inflation, while their price-sensitive customer base leaves little room to pass on rising costs without hurting demand.
Apparel contributes about 22.8% of the overall revenue of the country’s largest retailer, DMart, in FY26. Rising polyester and fabric prices could also weigh on this share, which has been declining since FY20.
“We see almost 60% to 70% consumption of polyester yarn or poly-based product lines, which have or will get impacted,” said Lalit Agarwal during the company’s March-quarter earnings call. Agarwal said that yarn prices had already risen sharply in recent weeks. “There is a rise of almost 10% to 15% in the yarn prices, which effectively converts to almost 5% to 7% in the apparel prices,” he said.
“Cost increases are at multiple points. One, of course, is raw material, which is not only fabric, but also polyester buttons, thread, packaging, all of that,” Devangshu Dutta, founder of Third Eyesight, a consulting firm, said. “Because with value, you cannot really pass on the price hikes so readily to the consumer.”
Dutta said that lower- and middle-income consumers were already under financial stress from broader inflationary pressures, “so, they will not be able to absorb price hikes as easily as well.”
Ebitda margins in Q4FY26 are 10.9% for V-Mart Retail, 13.6% for Vishal Mega Mart and 19.1% for Kewal Kiran Clothing.
Double whammy for value segment
Gunender Kapur, CEO of Vishal Mega Mart, during the company’s March-quarter earnings call, said the inflationary impact had started becoming visible towards the end of April and would likely intensify in the coming months.
Despite rising input costs, retailers said they are avoiding broad-based price hikes on entry-level products amid fragile demand conditions in the value segment.
Entry-level products for these retailers range from ₹199 to ₹399, with some going up to ₹1,500.
“We would never tinker with the opening price points and the lower price points in these difficult times, because those are the customers who are the most vulnerable in inflationary situations,” Kapur said.
Hemant Jain, CEO of KKCL, said the company was willing to absorb part of the pressure on profitability to protect revenues and market share.
Jain also said the company had not yet implemented price hikes despite the inflationary environment.
To cushion the impact, companies said they are increasingly relying on cost optimisation, fabric innovation, premium fashion products and deeper expansion into smaller towns to sustain growth.
V-Mart said it was attempting to offset part of the inflation through alternative fabric usage, sourcing efficiencies and tighter inventory planning.
The retailer has also blocked orders in advance and is utilising existing yarn and fabric inventories available with vendors to soften the immediate impact of rising prices.
Vishal Mega Mart’s Kapur said it has revived cost-saving measures from the post-Ukraine cotton inflation cycle, including replacing cartons with gunny bags, removing polybags from some apparel categories, and shipping footwear without outer cartons.
The retailer has also increased the use of computer-aided design systems to reduce fabric waste during cutting.
Premium products, private labels offer buffer
These value retailers are also increasingly depending on premium and higher-fashion assortments, where consumers are relatively less price sensitive, to absorb selective price increases while keeping entry-level products affordable.
Kapur said Vishal Mega Mart’s large private-label portfolio, which contributes over 74% of its revenue, gives it greater flexibility to manage pricing pressure while maintaining discounts against national brands.
KKCL on the other hand, said it would absorb part of the inflationary impact rather than immediately pass on higher costs to consumers.
These retailers are also increasingly leaning on expansion into smaller towns and deeper markets to drive incremental growth as discretionary spending in larger urban centres remains uneven.
Value fashion retailers have underperformed the broader market amid growing concerns over rising input costs and margin pressure. Shares of V-Mart Retail, V2 Retail Ltd, Vishal Mega Mart and Kewal Kiran Clothing have fallen between 4% and 11% on a year-to-date basis, while the benchmark BSE rose 6.1% during the same period.
(Published in MINT)
admin
May 15, 2026
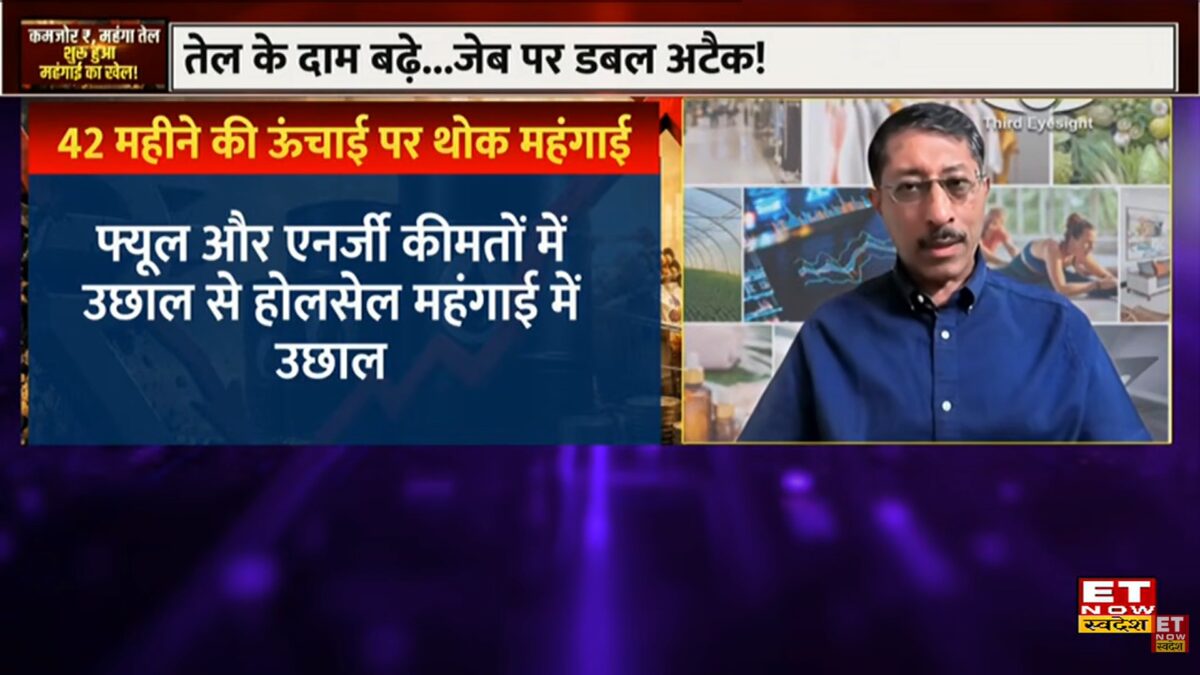
The ET Now Swadesh panel discussion focussed on the dual challenge facing the Indian economy: a weakening rupee and rising crude oil prices, which together are driving “imported inflation” and straining household budgets. Devangshu Dutta (Founder, Third Eyesight) put forth the following key points during the discussion (the video link is under the text summary below):
1. Dual Impact on Industry and Consumers:
2. Vulnerability of Small Businesses (SMEs):
3. Income vs. Expenditure Strain:
4. Ripple Effect of Crude Oil Beyond Logistics:
5. Shifts in Consumer Spending Patterns & “Shrinkflation”:
The panel noted that while the Reserve Bank of India (RBI) has adequate foreign exchange reserves to defend the rupee temporarily, the definitive solution relies heavily on the cooling down of global geopolitical tensions (such as the Middle East conflict affecting the Strait of Hormuz). Until then, Indian consumers will need careful financial planning and smart spending adjustments to navigate this inflationary phase. [Video below.]
