admin
October 7, 2026
Vidya Sathyapriyan, ET Brand Equity
7 October 2026
Every single month, leather-goods brand Hidesign changes the storefront of its airport stores. The reason: “You can’t bore the man or woman who’s coming to the airport every week,” says founder Dilip Kapur.
But then what makes the airport shopper any different from someone walking into a high-street or mall store? Affluent? Sure. Willing to spend? Mostly. Time-poor and seeking convenience? Definitely.
That mix presents a particular challenge for brands: understanding what and why travellers will buy, and how quickly they can buy it.
Some have learnt to make the often lopsided economics work. Others are running an expensive billboard with a billing counter attached.
Crunching Numbers
The economics are punishing.
Airport rents, minimum guarantees, revenue-share, staffing and operating costs can make them significantly more expensive than conventional retail. For example, a good mall in Chennai charges roughly Rs. 350-800 per sq ft monthly in retail rent, compared with Rs. 150-200 per sq. ft. on the high street. Airport rentals can rise to as much as Rs. 6,000 per sq. ft. Similar differentials play out in other major cities.
Yet brands keep signing on because the alternative would be an advertising site with no retail attached. “A hoarding is for all and sundry and 1D,” says S. Shriram, founder of Miles2Go Consulting Services. “In the airport, captive audience, engagement is 3D and sometimes even 4D – touch and feel, trial, buy, and even return elsewhere.”
For deep-pocketed brands, spending on airport visibility can be justified even when store-level profitability is modest or even non-existent. Others gotta move on.
Go Colors, for instance, is rationalising stores at airports where the economics are not working. “The opportunity remains strong, but the location must justify the cost of access to the consumer,” says CMO Vatsal Koolwal. “As a broad benchmark, rentals in the range of 15-20% of revenue can work, provided the rest of the cost structure is managed effectively.”
The right sell
Six of Hidesign’s top-10 stores in India are at airports, says Kapur. The average Hidesign airport store generates roughly twice the turnover of an average mall store, while its smaller footprint pushes sales per square foot even higher.
A key reason is the skew in merchandise mix towards gifting.
Around 40% of the products sold in Hidesign’s airport stores are gifts. “If you have a product which can be gifted, can be purchased quickly and is work-oriented, you’ve covered most of the problematic variables.”
An overwhelming majority of domestic air travellers are men, who may not spend two hours browsing a mall, but can quickly buy a premium handbag for someone back home. Time is their scarcest resource, not money.
“Those are breaks (from routine). These are things that they would normally not have time to do,” adds Forest Essentials executive director Samrath Bedi on why premium skincare too commands attention in an airport environment.
But categories such as perfumes, cosmetics, watches, sunglasses, travel accessories and bags have an obvious advantage – they can be bought quickly and generally don’t require fitting rooms or extensive trial. As Pravat Paikray, VP-Commercial, Bangalore International Airport, says, these “one-size-fits-all” categories perform well.
Right-Sizing
Apparel, jewellery and other categories involving multiple sizes, fits or lengthy considerations have a harder job.
“Standalone apparel and niche lifestyle stores would typically be loss-making,” says founder, Third Eyesight, Devangshu Dutta.
Shriram believes even these categories are being held back by conventional merchandising assumptions. He points out that a business traveller does not necessarily need another blazer simply because they are at an airport. What they may need is a pair of track pants for an overnight trip, a gift for someone at home, or a product they discover while waiting for a flight.
For instance, Ramraj Cotton’s proposition works partly because of its local-brand resonance and partly because of its gifting-driven merchandising. “There are a lot of combos which work very well for gifting,” says Radhakrishnan. He says passengers are usually concerned about weight restrictions, so the store even repackages the items as per requirement. The brand declined Brand Equity’s interview request.
Airport merchandise can carry a 20-40% premium, he says, because the customer is paying partly for convenience. The traveller does not necessarily want to step out into the city just to save a few hundred rupees.
Front of the Queue
Paikray says Bengaluru airport explicitly designs its retail proposition around this time constraint. Brands are expected to adapt their store design, assortment, staffing, service and operations rather than simply transplanting their city format. “If a brand has 100 stores, don’t come and open 101st store in an airport, ” he says.
For Forest Essentials, what changes is also the reason the consumer is being shown the product, says Bedi. Hydration for flying, sleep on long journeys, stress relief, gifting, replenishment, etc. “It’s just about how you angle it.”
Bengaluru airport is also lowering the barriers for brands to test the market by using pop-up stores to let newer brands test travel retail without committing to long-term contracts.
Paikray says challenger and D2C brands are increasingly considering airports earlier in their expansion journeys.
But the opportunity is not on auto-pilot. Only those who adapt can turn the minutes before boarding into something more valuable than visibility – a sale.
(Published in ET Brand Equity)
admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
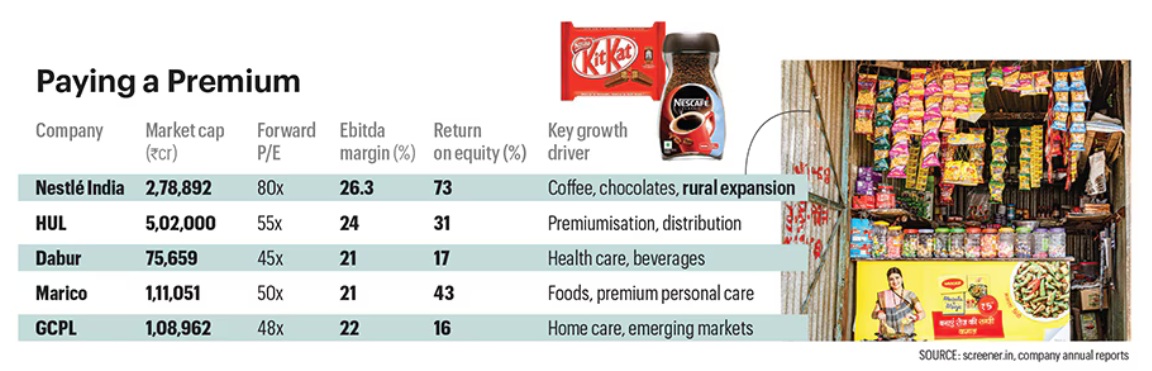
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
admin
September 22, 2025

Christina Moniz, Financial Express
22 September 2025
It is already the largest player among organised fumiture makers with over 15% of the market. With 1,000 stores, it has the widest retail store footprint among organised players. The 102-year-old brand is also the second-largest revenue con-tributor to the parent enterprise.
So why is Interio tinkering with its name, logo and colour attributes?
“We want to move away from being viewed as a functional brand to more of a design-led lifestyle one. We have a wider range of offerings that are more modular and aesthetic,” says Reshu Saraf, head of marketing communications at Interio by Godrej.
As a first step, it has a new logo and name change – from Godrej Interio to Interio by Godrej. The brand has earmarked ₹50 crore towards an integrated campaign across TV, digital, outdoor and in-store branding to promote its new proposition over the next year. Overall, it will invest ₹300 crore in expansion and technology with the goal to more than double revenues to ₹10,000 crore by FY29.
Younger consumers don’t see furniture as utility but as lifestyle, observes Puneet Pandey, strategy head and managing partner, OPEN Strategy & Design. “By moving from ‘solid and sturdy’ to ‘stylish and aesthetic’, the brand earns the right to play at higher price points as well. Design-led positioning will also unlock repeat purchase since people no longer wait a decade to change their furniture based on utility; they want constant upgrades to refresh their living spaces as their tastes evolve,” he notes, adding that Interio needs to make the marketing leap from “catalogue to culture”.
Saraf says the brand is also building differentiation with its customer experience. “We’re using digital tools for store walkthroughs and visualisers to help visualise our products in the home. Our product portfolio, which is deeply personalised ane tailored for Indian sensibilities, it is a major differentiator that few other brands offer,” she points out.
E-commerce is also a focus area with the brand looking to increase the revenue share from 15% to 20-22% by 2029. The company is leveraging Al to improve the search functionand sharpen personalisation. Saraf adds the that offline too, the brand will have large format experience centres to help people envision what their rooms could look like, along with mid-size and small-format stores.
Interio also plans to widen its retail store footprint from 1,000 to 1,500 by 2029.
As per industry estimates, the Indian furniture market is set to grow at 11% annually to reach $64.1 billion by 2032 from $30.6 billion in 2025. It is this growth momentum that Interio is looking to cash in on.
Built-in differentiation
Although a significant chunk of Interio’s business comes from its home remodelling services, within the furniture category, it competes with global players like IKEA and digital-first brands like Pepperfry. The challenge for Interio in this market is to embed the design-led positioning in its productsandcus-tomer experience, says Nisha Sam-path, managing partner at Bright Angles Consulting.
One of its biggest advantages is the Godrej brand. “The Godrej brand stands for many values prized in interiors such as quality, trust, reliability and durability with a ‘Made in India’ tag. However, the brand has not been so successful in building an image of cutting-edge design and innovation. These are new values that can make the brand more contemporary,” she remarks.
Devangshu Dutta, CEO of Third Eyesight concurs, pointing out aside from nimble competition, Interio’s key challenges also come from the dual pressures of increasing consumer expectations for rapid delivery and customisation on the one hand, with aggressive price competition on the other.
(Published in Financial Express – Brandwagon)
admin
September 5, 2025
Pooja Yadav, Exchange4Media
4 September 2025
Quick commerce today is no longer just about delivering groceries in 10 minutes. It has emerged as one of India’s most coveted retail media channels, where brands are willing to pay a steep premium for visibility.
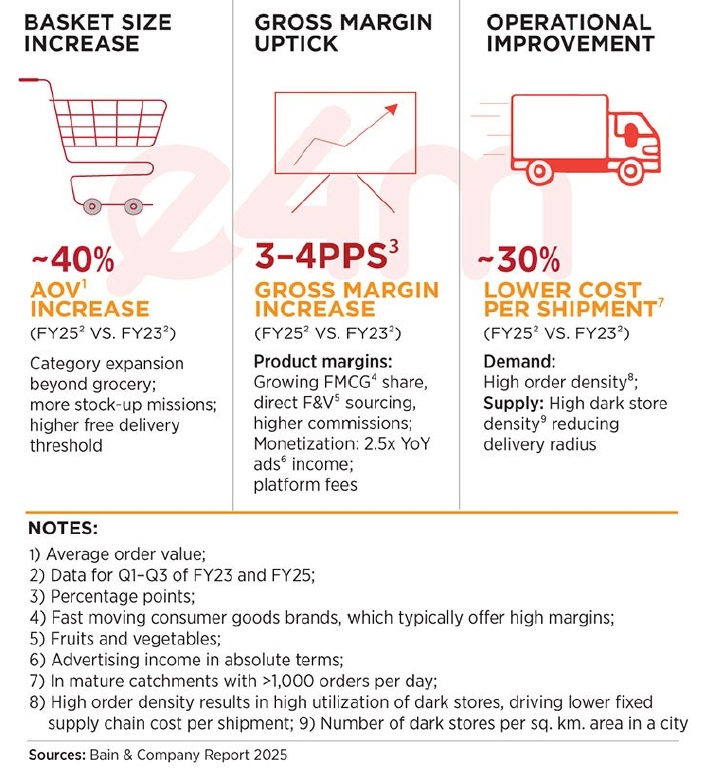
If FY25 was about building scale, FY26 is definitely shaping up to be about pricing power. With consumer adoption of 10–20-minute delivery apps surging, advertisers are competing for limited inventory, pushing ad rates up by 30–50% year-on-year.
“Ad rates on quick commerce platforms have surged by 30–40% year-onyear, especially during high-impact windows like festive seasons and major cricket events. This is fuelled by rising user engagement and proven performance outcomes. With more sophisticated ad formats and attribution models now in play, advertisers increasingly view the premium as justified,” added Uday Mohan, COO, Havas Media India & Havas Play.
Scale, Pricing & Soaring Ad Rates
While agencies point to surging demand, market data shows that platforms themselves are firming up monetisation models with steep onboarding thresholds.
As per market estimations, Swiggy Instamart offers tiered onboarding packages ranging from ₹4.5 lakh to ₹10 lakh, adjustable against advertising spends over a three-month period. Zepto reportedly asks new or small brands to commit anywhere between ₹2 lakh and ₹7 lakh per month on ads, depending on the category. Blinkit, on the other hand, charges ₹25,000 per SKU per state as a non-refundable onboarding fee, which is credited to the brand’s ad wallet.
This aggressive push comes against the backdrop of a sector that has grown at breakneck speed. According to CareEdge Analytics’ July 2025 data, India’s quick commerce market was valued at around ₹64,000 crore in FY25, growing at a staggering 142% CAGR during FY22–FY25 on the back of evolving consumer preferences, hyperlocal infrastructure, and a low base.
The momentum is expected to continue with strong double-digit growth over the next few years, as adoption deepens in Tier II & III cities, delivery networks expand, and instant fulfilment becomes mainstream.
At the same time, platforms are pivoting from pure hypergrowth to sustainable profitability—tapping into advertising, subscriptions, private labels and tech-led inventory optimization as key revenue levers. This shift is being enabled by India’s expanding digital backbone: with over 1.12 billion mobile connections and 806 million internet users (a 6.5% YoY rise), the country is projected to cross 900 million internet users by the end of 2025. Rising smartphone penetration in both urban and rural areas, aided by affordable data and policy support, has created one of the world’s largest online consumer pools, with 270 million e-shoppers in 2024, making India the second-largest e-retail market globally.
Unsurprisingly, advertisers are flocking to these platforms because that’s where their consumers are. Even though seller commissions contribute the bulk of revenues (68–74%), ad placements and brand boosts already account for 9–11%. Industry data shows that ad rates on quick commerce apps have climbed by 30–50% in just a year, with premiums doubling during high-impact windows like festivals and cricket tournaments. This steep inflation reflects both rising consumer traffic and the limited nature of in-app inventory, pushing brands to pay top dollar for guaranteed visibility at the point of purchase.
Bain’s ‘How India Shops Online 2025’ report also underscores this momentum: beauty, personal care, and snacking categories are already outpacing overall e-retail growth, and these are the very segments leaning most aggressively into quick commerce ads.
“Ad rates on quick commerce platforms have jumped by nearly 40–50% compared to last year. This spike reflects that premium brands are willing to pay for immediacy and guaranteed visibility, where ad placement directly links to instant purchase behaviour,” said Mandar Lande, founder of Waayu, a zero-commission food delivery app in India.
According to Aditya Aima, Managing Director, Growth Markets; Co-MD, India & MENA, AnyMind Group, ad rates on quick commerce platforms have not only risen but demand has intensified. “The surge is fuelled by three dynamics: sticky consumer behavior with high visit frequency, dense purchase intent compared to social or entertainment platforms, and the scarcity of ad real estate.”
Quick commerce becomes a strategic channel
For brands, quick commerce has moved far beyond being a fulfillment partner. It has become a strategic advertising channel, especially for those in fast-moving and competitive categories like beauty, wellness, snacks, and personal care. The platforms offer not just last-mile delivery but also front-of-shelf visibility in an increasingly cluttered digital environment.
According to Seshu Kumar Tirumala, Chief Buying and Merchandising Officer, bigbasket, “Brands are moving beyond purely search-centric strategies and increasingly adopting immersive display activations with formats like Spotlight Videos, Banners with Add-to-Cart (ATC), targeted banners, and ATC widgets. For established brands, most investments still flow into performance-led formats such as Sponsored/PLA ads, while a portion is reserved for top-funnel initiatives like storytelling, new launches, and high-visibility events. Emerging or smaller brands usually begin with awareness and consideration campaigns before shifting focus toward performance once they’ve built stronger customer connections.” Unlike marketplaces or social media, quick commerce blends data-led targeting, high engagement, and measurable ROI.
Many brands pair Q-comm placements with collab ads on Meta, Google, and Criteo to build visibility while keeping consumers engaged across the funnel. This creates a sharper, closed-loop system where awareness, consideration, and conversion happen almost instantly. “D2C brands have been rapidly scaling up ad spends on quick commerce platforms, up to 40–50% year-on-year, with a significant share during the festive season. Among the key reasons are fast-growing adoption of Qcomm by consumers and better ROI than marketplaces,” said Shrikant Shenoy, AVP at Lodestar UM.
What sets this instant delivery model apart is its ability to compress the purchase journey. Marketplaces drive comparisons, and social platforms spark discovery, but Q-comm taps into impulse buying with SKU-level attribution.
“The quick delivery model encourages impulse purchases and immediate gratification shopping, which is particularly valuable for D2C brands. Qcomm platforms have lower competition density, and ad formats are more native and less cluttered than traditional e-commerce,” said Devangshu Dutta, founder of Third Eyesight.
“When someone opens Blinkit or Zepto, they’re usually in active purchase mode, not just browsing. For consumables, personal care, or lifestyle products, this is the sweet spot of marketing,” Dutta noted.
“Ad rates on quick commerce have gone up by more than 20% in the last year. If you want a prime slot, say a homepage banner in a big city, you might even be paying 50% more than last year. Because every brand wants it. When a Blinkit or Swiggy placement can move your product in minutes, not weeks, those ads aren’t just distribution, they are discovery,” said Mohit Singh, Head of Product at Zippee, a quick commerce logistics platform.
Meanwhile, pricing pressures are only going up. Ratnakar Bharti, VP, Media, Mudramax said, “Quick commerce isn’t just ‘fast delivery’ anymore, it has become high-intent retail media sitting right next to the ‘add to cart’ button, with sales that can be measured in real time. Quick commerce platforms say their ads business grew 5X in a year to about $200M ARR. At that kind of scale, inventory quality improves, targeting gets sharper, and the medium starts looking like the next big retail media play.”
“In a nutshell, expect meaningfully higher prices in peak weeks — often up to 2x — and a higher year-round floor price due to steeper minimums and fees. The trade-off is harder proof of sales at the exact SKU, which is why demand and prices are rising,” Bharti added.
“Brands pay a premium for Q-Comm because it drives sales at the point of purchase. What began as experimental spends has now become a steady line item in media plans, thanks to strong ROI and proven results,” added Jatin Kapoor, MD, AdsFlourish.
Beauty, beverages & snacking lead the charge
Notably, not all categories are leaning on quick commerce equally. Industry executives point out that beauty & personal care, beverages, snacking, and wellness are the biggest spenders, given their high repeatability, impulse-driven nature, and urban skew.
Beauty and personal care brands, for instance, are using Q-comm not just to drive trial packs and quick replenishment, but also to run festival-led campaigns targeting affluent millennials. Similarly, beverages and packaged snacks are thriving on the “in-the-moment” consumption occasions that these apps uniquely enable.
“The biggest spenders are beverages, beauty, packaged foods, and wellness. Those categories thrive on impulse and repeat consumption, which is exactly what quick commerce delivers best,” Singh added. As per many industry experts, wellness and lifestyle brands, too, are seeing outsized returns. From daily supplements to discreet personal care items, quick commerce is proving to be a low-friction purchase environment with high conversion rates.
“Quick commerce platforms have lower competition density, and ad formats are more native and less cluttered than traditional e-commerce,” explained Dutta.
Media buyers also note that Q-comm platforms are evolving fast, offering more contextual in-app placements and data-driven targeting. This is creating a level playing field for challenger brands that lack legacy shelf space in offline retail.
“Quick commerce advertising is inherently contextual. A beverage or snack brand running an IPL campaign is literally tapping into the consumer’s 15-minute window of intent, it’s that instant,” added Mohan.
With ad rates on quick commerce platforms climbing 30–50% year-on-year, it’s clear the medium is shifting from experimental budgets to a core retail media channel. However, with competition heating up, festive weeks commanding 2X pricing, and minimum spends rising, the question is: how long before quick commerce ads start resembling the crowded, high-cost landscape of traditional e-commerce marketplaces?
(Published in Exchange4Media)
admin
August 6, 2025

Naini Thaker, Forbes India
Aug 06, 2025
It’s a known fact that of the thousands of startups founded each year, only a small fraction survive—and even fewer scale to become unicorns. Rarer still are those unicorns which, after reaching dizzying heights, come crashing down. The Good Glamm Group is one such cautionary tale.
Once celebrated as a unicorn that cracked the code on content-to-commerce, the company’s meteoric rise was matched only by the speed of its unravelling. At the heart of its downfall lies a critical misstep: The relentless pursuit of growth through acquisitions and brand launches, even as cracks in its house-of-brands model began to show. Instead of pausing to consolidate and build sustainably, Good Glamm doubled down—prioritising valuation over viability.
That strategy came to a head on July 23 when founder and CEO Darpan Sanghvi announced the dissolution of the group’s house-of-brands structure. In a LinkedIn post, Sanghvi confirmed that lenders would now oversee the sale of individual brands, effectively ending the company’s vision of building a digital-first FMCG conglomerate.
Despite raising $30 million in 2024 and undergoing multiple rounds of restructuring, the group failed to integrate its acquisitions or generate sustainable profitability. With key investors such as Accel and Bessemer Venture Partners exiting the board and leadership turnover accelerating, the company’s ambitious empire—built on rapid expansion and aggressive brand aggregation—has now been reduced to a lender-led breakup.
In the aftermath of the announcement, Sanghvi offered a candid reflection on what went wrong. “In hindsight, it wasn’t one decision, one market force, or one acquisition. It was three levers we pulled, which together, turned Momentum into a Trap,” he wrote in a LinkedIn post. According to Sanghvi, the group’s downfall stemmed from doing “too much, too fast and too big”.
He elaborated: “At first, Momentum feels like your greatest ally. Every headline, every funding round, every big launch is a shot of adrenaline. And you start believing you can do more and more and more. But momentum has a dark side. If you stop steering and go in a hundred different directions, it doesn’t just carry you forward, it drags you faster and faster until you can’t breathe.”
Where The Model Broke?
In October 2017, Sanghvi launched direct-to-consumer (DTC) beauty brand MyGlamm. Most brands at the time were big on selling on marketplaces such as Amazon or Nykaa. However, Sanghvi believed, “We wanted to be truly DTC and not just digitally enabled. We believed that to own the customer, the transaction needs to happen on our own platform.”
But the biggest challenge with being a DTC brand is its customer acquisition cost (CAC). Towards the end of 2019, the company was spending about $15 (over ₹1,000) to acquire a customer to transact on their website. “Around the same time, our revenue run rate was ₹100 crore. We were spending about $0.5 million to acquire 30,000 customers a month. That’s when we realised it was time to solve the CAC problem,” Sanghvi told Forbes India in 2022. In an attempt to find a solution, Sanghvi turned to the content-to-commerce model.
And then, started the acquisition spree. According to Sanghvi, with a single brand in a single category one can’t build scale. He told Forbes India, “The most you can scale it is ₹1,000 crore, if you want a company that’s doing ₹8,000 or ₹10,000 crore in revenue, it has to be multiple brands across multiple categories.” In hindsight, this perspective might be debatable.
As Devangshu Dutta, founder of consultancy Third Eyesight, points out, the “house of brands” model is essentially a modern-day consumer-facing business conglomerate—and its success hinges on multiple factors working in harmony. While there are examples globally and in India of such models thriving, both privately and publicly, the reality is far more nuanced. “Brands take time to grow, and organisations take time to mature,” Dutta notes, emphasising that rapid aggregation of founder-led businesses under a single ownership umbrella is no guarantee of success.
In recent years, Dutta feels the influx of capital into early-stage startups and copycat models—often seen as lower risk due to their success in other geographies—has shortened business lifecycles and inflated expectations. The hope is that synergies across the portfolio will unlock outsized value, but that rarely plays out as planned. “It is well-documented that more than 70 percent of mergers and acquisitions fail,” he adds, citing reasons such as weak brand fundamentals, lack of synergy, inadequate capital, limited management bandwidth, and internal misalignment.
In the case of Good Glamm, these fault lines became increasingly visible as the group expanded faster than it could integrate or stabilise.
Scaling Without Steering
In FY21, the company had losses of ₹43.63 crore, which rose to ₹362.5 crore in FY22 and went up to ₹917 crore in FY23. Despite the mounting losses, Good Glamm marked its entry into the US market, in a joint venture with tennis player Serena Williams to launch a new brand—Wyn Beauty by Serena Williams. The launch was in partnership with US-based beauty retailer Ulta Beauty.
For its international expansion, it invested close to ₹250 crore over three years. “We anticipate that the international business will account for 25 to 35 percent of our total group revenues by the end of next year. This strategic focus on international expansion is pivotal as we prepare for our IPO in October 2025,” he told Forbes India in April 2024.
Clearly, things didn’t pan out as expected. As Sanghvi rightly points out, it was indeed a momentum trap. “You tell yourself you’ll fix the leaks after the next milestone. But the milestones keep coming, and so do the leaks. Soon, you’re running from fire to fire, never realising that the whole building is getting hotter. And somewhere along the way, you lose the stillness to think,” he writes on his LinkedIn post.
Dutta feels that a strong balance sheet is the most fundamental requirement, “to provide growth-funding for the acquisitions or for allowing the time needed for the acquisitions to mature into self-sustaining businesses over years. In the case of VC-funded businesses, the pressure to scale in a short time can go against what may be best for the business or for its individual brands”.
The Good Glamm Group’s fall is a reminder that scale alone doesn’t build resilience. Its story reflects the risks of expanding faster than a business can integrate, and of prioritising valuation over value. The house-of-brands model can work—but only when backed by strategic clarity, operational discipline, and patience. This is less a warning and more a reminder for founders: Scale is not success, and speed is not strategy.
(Published in Forbes India)
