
admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
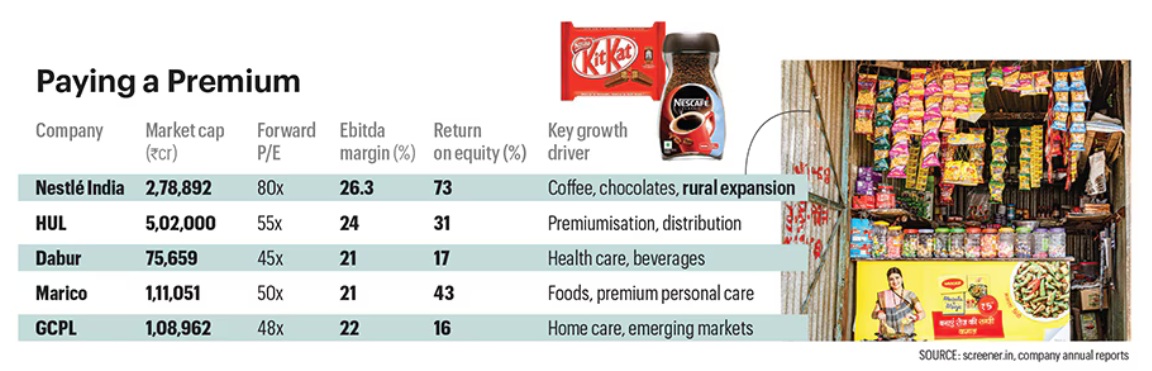
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
admin
February 12, 2026

Vaeshnavi Kasthuril, Mint
Bengaluru, 6 February 2026
Global fragrance maker Bath & Body Works Inc. is betting on a reset to revive growth after years of heavy discounting and weak product innovation dulled its brand momentum across markets. The Columbus, Ohio-based retailer is pivoting to a “consumer-first” formula strategy centered around upgraded formulations, more disciplined marketing, and fewer promotions.
The reset matters as India is emerging as one of the company’s fastest-growing and best-performing markets and is also becoming a testing ground for how the brand evolves its retail model. India now ranks among Bath & Body Works’ top five international markets by growth.
“We’re seeing strong engagement across stores (in India), digital marketplaces and even quick commerce, which gives us confidence as we evolve the brand and introduce more innovation,” said Tony Garrison, global vice president at Bath & Body Works, in an interview with Mint.
The fragrance maker entered India in 2018 in partnership with Dubai-based Apparel Group and has since expanded to about 50 stores across major metros, while also building an online presence through platforms such as Nykaa, Myntra, and Amazon. Apparel Group brings over 80 global brands to India, including Victoria’s Secret, Charles & Keith, Aldo, Crocs, and Tim Hortons.
“We’re learning a lot from how the Indian consumer shops across platforms, especially the speed and convenience expectations,” Garrison said. “It’s helping us think differently about assortment, pack sizes and how we show up digitally”.
Even as discretionary spending softened, the brand’s franchise partner, Apparel Group, delivered double-digit sales growth in India and high single-digit comparable store gains in FY25. It reported a 26% year-on-year jump in FY25 revenue to ₹1,118 crore and a net profit of ₹20.5 crore, reversing a loss in the previous year.
Globally, Bath & Body Works’ earnings reflect soft consumer demand as well as margin pressures. Its revenue declined 1% to $1.59 billion in the third quarter of FY25, while net income fell 27% year-on-year to $577 million.
Reviving the fragrance engine
While legacy scents such as Japanese Cherry Blossom, Champagne Toast, and Thousand Wishes remain global blockbusters, the company admits it hasn’t produced enough new hits at a similar scale in recent years. Japanese Cherry Blossom is a $250 million fragrance.
“I think we haven’t done the best job of keeping up with some of the fragrance trends. We haven’t done a lot of innovation, and that’s what you’re going to see this year. This is a big change year for us,” Garrison said.
The company plans to elevate its home fragrance portfolio, bringing in more premium candle collections, gift-ready packaging, and deeper, more sophisticated scent profiles. The broader goal is to encourage shoppers to trade up within the brand rather than wait for markdowns. “We want customers to see the value in the product itself… not just the promotion,” Garrison said.
New retail formats
To test new retail formats, the company and Apparel Group plan to pilot a small “neighbourhood store” format of roughly 500 square feet in select non-metro markets later this year. These stores will focus heavily on core body care lines and hero fragrances, while creating a more discovery-led environment for first-time shoppers.
India is also emerging as a key market in testing how far premiumisation can go. Garrison noted that the company has not seen a slowdown locally: “India has actually been one of our strongest markets in the post-Covid period. Even when consumers are careful, they still spend on small luxuries that make them feel good”.
What experts say
Retail experts caution that the reset in India won’t be without challenges. Devangshu Dutta, founder of Third Eyesight, noted that brands often fall back on discounting when volumes don’t come through. He added that the personal care market has become intensely crowded, making brand clarity critical.
While the brand is leaning into quick commerce and smaller stores, Dutta cautioned that premium brands still need larger formats to build experience-led differentiation. “Neighbourhood stores can be spokes, but you still need the hub—the large store—to communicate the brand experience,” he said.
Race Intensifies
The turnaround plan comes at a time when rivals, including The Body Shop and Forest Essentials, are also vying for the Indian consumer’s wallet. The Body Shop plans to achieve ₹1,100 crore in revenue in India within the next three to five years. India’s fragrance market was valued at $1.0 billion in 2024 and is projected to grow at a 13.9% CAGR to $3.23 billion by 2033.
(Published in Mint)
admin
January 31, 2026
Surabhi Prasad, Business Today
Print Edition: 01 Feb, 2026
The last two years—2024 and, more notably, 2025—saw a wave of protests by a new generation of students and young professionals looking for political change, better economic conditions and more climate awareness across countries, including Bangladesh, Nepal, Indonesia and the Maldives.
But beyond these uprisings, Gen Z, the term used to describe those born in late 1990s to the early part of the 2010s and currently aged around 13-29 years, are not only questioning but also bringing forth changes in societal norms and economic behaviour. It’s not just a generation gap!
Gen Z are digital natives. They are tech savvy, have grown up with Internet in their homes, iPads as their support system, social media as a constant companion and take digital payments, online and quick commerce for granted. They tend to be night owls, the real gigsters, at home with artificial intelligence (AI) and machine learning, and with a lingo—cap, salty, suss and tea—that make others scratch their heads.
They also have newer challenges—rising unemployment, an uncertain economic environment, the rise of AI that has put a question mark on the future of work, climate change that is turning more real by the day, and skyrocketing real estate prices that mean a dream home could remain just a dream. Still, they are the rising consumer force who, over the next decade, are poised to become the largest chunk of the labour force and the focus of most companies.
For a country like India that is still young, Gen Z will soon be the economic force to reckon with. A recent report by not-for-profit think tank People Research on India’s Consumer Economy (PRICE) estimates that as of 2025, nearly one in five young individuals globally lives in India. “This is a formidable 420-million strong force, constituting approximately 29% of the nation’s total population, and made up of individuals aged between 15 and 29 as defined by India’s National Youth Policy (2014),” it said.
Labour sociologist Ellina Samantroy, Fellow at the V.V. Giri National Labour Institute, says India’s expanding Gen Z or youth workforce offers a significant opportunity for the country to reap the demographic dividend. As per the recent Periodic Labour Force Survey 2023-24, around 46.5% of the labour force is in the 15-29 age group. “There has been an increase in labour force participation in this age group from 42% during 2021-22. One can see the economic growth potential of this cohort,” she says.
However, with transitions and emerging opportunities in the world of work, it is important to harness the potential of this population cohort with adequate access to education and skilling, she says.
Devangshu Dutta, founder and chief executive of Third Eyesight, a boutique management consulting firm focused on the retail and consumer products ecosystem, says Indian Gen Z consumers are not a uniform cohort.
“A critical issue in India is the coexistence of aspiration and constraint, and India’s Gen Z are shaped by a mix of high digital exposure and wide economic disparity. While they are ambitious and globally aware, their purchasing power varies sharply across segments and locations,” he says.
Further, urban, higher-income Gen Z display global consumption behaviours such as brand experimentation, social commerce and premium aspiration, whereas a large proportion of Gen Z in Tier II, Tier III and rural India is highly value-driven and necessity-led, while drawing their inspiration from global and national sources. He also points out that unlike Millennials, Indian Gen Z are also entering the workforce in a more uncertain economic environment, making price sensitivity, smaller pack sizes and flexible payment options important. “Employment patterns such as informal jobs, gig work and delayed income stability are influencing consumption cycles and brand loyalty,” he says. There is a strong preference for digital discovery, vernacular content and peer-led recommendations, with trust built through community and relevance rather than legacy brand status.
Rising aspirations of Indian households and changes in consumption pattern with a marked move from essentials to more premium products have been well documented, most recently in Household Consumption Expenditure Surveys. But more granular, individual-level data from PRICE shows marked changes in education levels and behaviour of Gen Z and other cohorts such as Millennials (those aged between 30 and 45), Gen X (aged 45-60) and Baby Boomers (60+). A 2024 PRICE ICE 360 Survey of 8,200 respondents (18–70 years) in 25 major cities showed that Gen Z is the most educated cohort, spends the most time browsing the Internet and is more engaged with e-commerce and paid digital services.
Multinational and domestic companies are also now waking up to the Gen Z wave and are realising that they need to review strategies to gain the attention and loyalty of Gen Z as consumers and workers.
“Fashion, beauty and personal care, food and beverages, and mobile and consumer electronics are at the forefront of change in India,” says Dutta. Responding to Gen Z requirements, companies are designing products at accessible price points, expanding entry-level ranges and leveraging sachetisation and subscription models. Brands are investing more in regional languages, local influencers and platforms such as short-video and social commerce channels that resonate with young Indian consumers, he says.
But this process is still at a nascent stage, and many companies and analysts are still trying to assess this generation.
For the 34th Anniversary Issue, we at Business Today decided to decode what Gen Z is truly about, what influences them the most, what they aspire to purchase, what they can afford and what this means for India Inc. Over the course of the last few months, our newsroom saw animated discussions as senior editors sat down with younger colleagues to discuss lifestyle choices, brand loyalties and career ambitions, as we drafted an issue brief and a potential survey.
We then got in touch with PRICE, which worked with us on our survey objectives and tweaked the questionnaire. The result—a first-of-its-kind exercise where PRICE surveyed 4,311 Gen Z respondents, who are now entering the workforce with an income of their own, residing in metros and Tier II cities. The survey covered gender, education, employment status, personal income and household income classes. The main focus was urban, educated Gen-Z who has the income to be a strong consumer.
The research examined consumption behaviour across discretionary and essential categories, savings and credit attitudes, digital influence, brand loyalty, aspirations, and future spending intent.
And the results are indeed, surprising! The survey reveals that traditional consumption models that were built around age-based life stages, linear career progression and early credit adoption no longer hold for Gen Z. “This cohort’s behaviour reflects early exposure to economic shocks, greater career volatility and a redefinition of success away from speed toward resilience,” it underlines.

For businesses, misreading delayed demand as permanent weakness risks underinvestment just as Gen Z approaches its next consumption inflection, it warns. For financial services, premature credit push without trust-building will underperform. For consumer brands, price-led acquisition without quality consistency will fail to convert into lifetime value.
Delve into this issue where BT brings to you the in-depth findings of the survey and explains what this means for companies as they vie for a share of this growing consumer segment. Gen Z is not just about rizz and drip, it is giving the main character energy as they come of age.


(Published in Business Today, issue dated 1 February 2026)
admin
December 10, 2025

Shabori Das, ET Bureau
Dec 10, 2025
India’s social media platforms are powerful marketing tools but not yet retail destinations. Billions scroll and swipe daily, but few buy directly within apps. Unlike China, India faces regulatory hurdles and a lack of integrated payment systems.
A billion Indians scroll, swipe and double tap every day, but barely buy. Despite Instagram and Facebook Marketplace being in India for over a decade, social media here remains a showroom, not a store. Creators and D2C brands are hustling to convert attention into action, but the holy grail of in-app shopping where discovery, live streaming, and purchase happen seamlessly, remains out of reach.
The question is, what’s stopping India from becoming the next China or the US in social commerce?
Influence-to-Commerce Gap
Globally, social commerce is powered by influencers. In China, influencer Li Jiaqi reportedly sold products worth $2 billion on Singles’ Day on Alibaba’s online marketplace Taobao Live in 2021. Another popular influencer Zheng Xiang Xiang, with over 5 million followers on Douyin (the Chinese equivalent of TikTok), reportedly generated $18 million in sales in a week in 2023. These are numbers India’s creator economy can only dream of, for now.
To be clear, influencer marketing in India is booming. EY estimates the sector at over Rs 3,000 crore and yet, due to regulatory restrictions, social media platforms in India can’t host end-to-end transactions. What India has is content commerce, driven by players like Meesho and Myntra, not social commerce. Globally, social commerce is a $1-trillion market. China alone accounts for over $500 billion and the US, $100 billion. India’s share? Around $10 billion — despite being home to the world’s largest Gen Z population and the second-largest base of internet users after China.
What’s Holding India Back
“Just as quick commerce changed how India buys food, social commerce will change how we shop for fashion and lifestyle,” says Anand Ramanathan, partner, consumer industry leader, Deloitte South Asia.
The idea is simple: Social commerce enables an end-to-end purchase journey within a social media app. But in India, the final sale still happens elsewhere — typically on e-commerce platforms.
“In China, live streaming contributes nearly 20% of total e-commerce revenue. In India, it hasn’t taken off,” says Puneet Sehgal, CEO of D2C apparel brand Freakins. He believes in-app checkout could be transformative. “Our Gen Z audience spends over an hour daily on social media. If the purchase could happen right there, it’s one step less for the consumer — and one step closer to a sale.”
The China Contrast
China’s social commerce revolution was built on three forces — speed, scale and seamlessness. Influencer Zheng, for instance, showcases each product for barely three seconds and moves on. That brevity, combined with integrated payments, drives impulse buying at staggering volumes.
India’s influencer-driven commerce, by contrast, is still warming up. Projected to touch $ 55 billion by 2030, it remains largely limited to discovery and advertising.
The barriers aren’t technological, they’re regulatory. India’s payment rules require clear accountability and settlement tracking, making it difficult for global platforms to enable in-app sales. Meta’s 2023 policy shift also directed purchases off-platform, keeping Instagram and Facebook Marketplace confined to discovery and promotion, rather than purchase. For now, social media in India remains a potent marketing engine, not yet a retail destination.
Experiments and Exceptions
Some Indian players are testing new waters. Myntra’s Glamstream, launched this July, lets influencers host live sessions where viewers can “shop the look” in real time — though the final checkout still redirects you to the Myntra app.
“India’s creator economy influences over $300 billion in annual consumer spending,” says Sunder Balasubramanian, chief marketing officer at Myntra.“That could grow to $1 trillion in the next few years, making India one of the fastest-growing creator economies globally,” adds Lakshminarayan Swaminathan, vice president-product management, Myntra.
The potential is clear. In 2021, Taobao Live hosted a 12-hour live streamed sale with influencer Li Jiaqi in China that clocked $2 billion in presales and attracted 250 million viewers.
Closer home, Sujata Biswas, co-founder of Suta Sarees, recalls Instagram’s shortlived Shop Now feature. “We saw an immediate dip in transactions after it was withdrawn,” she says. “Fashion is about instant gratification. You see it, you want it and buy it right away.”
The D2C Advantage
India’s D2C market, valued at $87 billion as of 2025 by Deloitte, could be the biggest gainer if social commerce does take off. Most D2C brands currently pay 25–35% retailer margins to platforms like Myntra and Nykaa. Social commerce could let them bypass intermediaries and sell directly to their audiences.
“Anything that reduces friction between intent and purchase is gold,” says Sehgal. “If that entire journey — from watching to buying — happens within the same app, conversion rates would shoot up.”
Even so, social platforms come with their own costs. TikTok, for instance, charges promotional, marketplace and fulfilment fees. But for Indian D2C players, the larger hurdle isn’t cost — it’s access.
Open vs Closed Ecosystems
“India’s retail market is far more open than China’s,” explains Devangshu Dutta, CEO of ThirdEyesight, a retail consulting firm. “In China, closed ecosystems like WeChat and Douyin created the perfect environment for social commerce to thrive. In India, where consumers can freely move between Google, Meta and e-commerce giants, those closed loops don’t exist.”
Globally, TikTok Shop, Douyin, WeChat, Pinduoduo, and Taobao Live dominate social commerce. According to Business of Apps, a data provider for the global app industry, TikTok earned $23 billion in 2024, with nearly 23% of it from in-app and commerce purchases.
If similar models are launched in India, e-commerce giants would face direct competition from the very platforms that fuel their traffic.
The Wait Continues
From beauty tutorials to thrift stores, social media spawns thriving micro economies. Yet, true social commerce — where discovery leads directly to purchase — hasn’t yet clicked.
The next big leap for India’s e-commerce may not come from deeper discounts or faster delivery but from social media itself. “The idea of instant gratification is key,” says Biswas. “When the ‘Shop Now’ button comes back, we’ll be the first to use it.”
Till then, India scrolls, likes, shares — and waits.
(Published in Economic Times)
admin
November 26, 2025
Aakriti Bansal, Medianama
November 26, 2025
MediaNama’s Take: The Central Consumer Protection Authority’s (CCPA) decision to publish 18 self-declarations confirms only a partial picture of its dark pattern(s) identifying exercise. The authority has stated that 26 platforms have filed their declarations, but it has made only 18 of them public. This gap means the public still cannot see what eight major platforms submitted or whether those filings contain any meaningful detail. Moreover, even among the published declarations, several are one-paragraph statements that offer almost no insight into the scope or accuracy of the companies’ internal audits.
LocalCircles’ new survey adds further complications, reporting that 21 of the 26 platforms that submitted declarations still display at least one dark pattern. This finding suggests that the CCPA’s reliance on voluntary self-assessment may not be enough to shift platform behaviour at scale. It also raises questions about what the unpublished declarations contain and whether the missing submissions are similarly sparse or incomplete.
Notably, the CCPA has not clarified how it plans to verify the accuracy of any of the declarations, whether published or unpublished. If filings remain unverified for months, compliance risks turning into a box-ticking exercise rather than a meaningful regulatory process. Therefore, the next phase matters far more than the publication of select declarations, because the current approach raises more questions than it answers.
What’s the News
The CCPA has made 18 dark pattern self-declarations public, despite stating that 26 platforms have filed their compliance letters. The publication follows an RTI filed by MediaNama that revealed which companies had submitted their declarations, and pointed out that none of the filings had been available to the public at the time.
These declarations stem from the Ministry’s June 5 advisory, which required e-commerce and quick commerce companies to conduct internal audits under the 2023 Guidelines for Prevention and Regulation of Dark Patterns and submit compliance letters within 90 days.
For context, Moneycontrol reported that Amazon has still not filed its declaration and has asked for additional time. A senior government official told the publication that the government “has done what it had to” and does not plan further discussions.
The official also said that any punitive action would depend on consumer complaints routed through channels such as the national consumer helpline. This indicates that the enforcement approach continues to be reactive rather than compliance-driven.
What Did The CCPA Ask Platforms To Do?
The June 5 advisory set out a simple compliance framework for digital platforms. It asked every e-commerce and quick commerce company to complete a self-audit of its website and mobile app within 90 days and check their interfaces for the 13 dark patterns listed in the 2023 guidelines. Platforms were required to file a self-declaration confirming compliance once this internal review was complete.
However, the advisory did not specify how the audit should be conducted. Companies were free to choose any methodology, and the CCPA did not prescribe a standard format, a uniform checklist, or a minimum evidence requirement. Also, the advisory did not require independent audits or third-party validation.
Furthermore, there was no explanation of how the CCPA planned to verify whether the declarations were accurate or complete. In effect, the responsibility for defining the scope, depth, and rigour of the audit rested entirely with each platform.
What the CCPA Has Done With the Declarations
As mentioned before, the CCPA has now published 18 self-declarations on its website. The release confirms that companies submitted their compliance letters, but it does not indicate whether the authority evaluated the accuracy or depth of the filings.
Several platforms submitted very short statements that simply assert compliance without describing any checks or findings. BigBasket, Zomato, Blinkit and Swiggy were among the companies that filed especially minimal disclosures. The CCPA has not explained why these filings were accepted or whether any follow-up questions were asked. Therefore, asking for and disclosing self-declarations shows some administrative progress, but it does not reflect any regulatory scrutiny.
This lack of verification aligns with concerns raised by Devangshu Dutta, Founder of business consulting firm Third Eyesight. He told MediaNama that self-declarations “do not change things much” when regulators do not audit submissions or impose consequences.
Further, Dutta remarked that most companies comply at the minimum level required if their claims are not examined and are not made public in full. According to him, revenue-driving design choices such as forced add-ons, confusing checkout flows or misleading scarcity claims will not be voluntarily removed sans oversight.
What Independent Evidence Shows
LocalCircles’ latest audit presents a sharply different picture from the companies’ filings. The organisation found that 21 of the 26 platforms that submitted “dark pattern free” declarations still use one or more manipulative design practices. The assessment relied on feedback from more than 250,000 consumers across 392 districts along with AI-assisted testing.
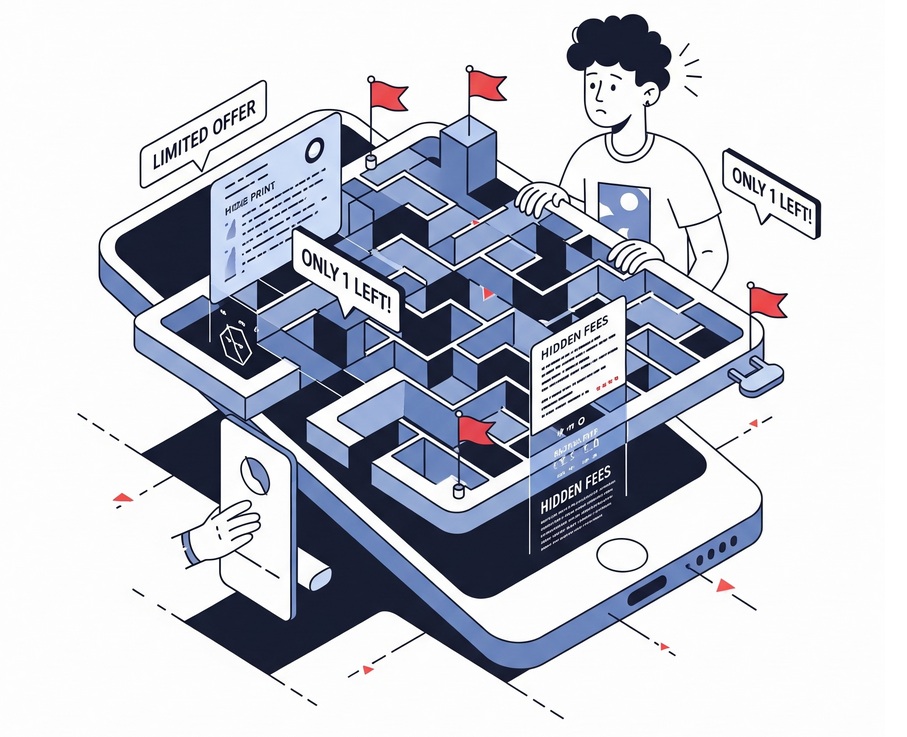
The most common violations include forced action, subscription traps, bait and switch, basket sneaking, interface interference and disguised advertisements. In practice, these dark patterns respectively mean that users are pushed into steps they did not choose, face hidden or hard-to-cancel subscriptions, see offers change during checkout, encounter fees added at the last moment, get nudged toward platform-favoured choices, and come across ads that appear as regular listings.
LocalCircles also identified drip pricing (gradually adding mandatory fees during the checkout process) on 11 of the 26 companies, including Flipkart, Myntra, Cleartrip, MakeMyTrip, BigBasket, Zomato and Blinkit, among others. The organisation said that many platforms appear to misunderstand what qualifies as drip pricing, which has led to incomplete corrections.
Trust Can Erode Due To Gap Between Declarations And User Experience
Sachin Taparia, Founder of LocalCircles, said that the problem begins with the absence of any verification. “Our understanding is that CCPA is wanting that companies submit a self-declaration at the earliest. However, there is no cross checking of claims that is being done by the CCPA, and as a result the companies are not being as thorough with their dark-pattern detection and resolution,” he said.
Taparia added that discrepancies between declarations and user experience could harm trust. “LocalCircles has found dark patterns on 21 of the 26 platforms submitting self-declarations. If this exercise is not done with high accuracy, both platforms doing so and CCPA could see consumer trust being impacted,” he said.
Importantly, Dutta echoed this concern, saying that the absence of penalties or reputation-related consequences allows companies to self-declare compliance while keeping revenue-generating patterns intact. He described the current process as “more an administrative formality [rather] than a behaviour-changing regulatory tool”.
Why This Matters
The gap between self-declarations and independent audits in the true sense of the word brings the real enforcement question into focus. What should the next phase of regulation look like?
In this context, Dutta said that regulators need to move beyond self-certifications and mandate detailed user experience (UX) audit reports that map every user journey, including pop-ups, onboarding, search, checkout, cancellations and returns.
He explained that regulators should reinforce this by demanding substantive evidence instead of brief compliance letters. This evidence can include screenshots and screen recordings of key flows, version histories that show how an interface changed over time, and product design documents or A/B testing results that reveal why specific nudges were introduced. To explain, A/B testing is essentially a method for comparing two versions of something to see which one performs better.
Furthermore, Dutta noted that platforms already collect extensive data on user complaints and drop-off points, which can help identify harmful or confusing design choices. He also said that independent third-party attestations, similar to security or accessibility audits, can provide a credible external check and increase the cost of non-compliance.
Multiple Annual Audits For Apps that Change Interface Frequently
Notably, Dutta stressed that most dark pattern categories appear across e-commerce, quick commerce and Direct-to-Consumer (D2C) websites, which means regulators can create a baseline audit standard that works across sectors instead of relying on platform-specific interpretations. He also suggested that audits should occur at least once a year, and companies that frequently modify their interfaces may need to report two or three times annually.
The larger concern now is whether the CCPA plans to move toward such a structured framework. Without independent verification and clear audit expectations, companies can continue declaring compliance even when manipulative designs remain embedded in their interfaces.
(Published in Medianama)
