admin
November 3, 2026
Pritha Pahari, The Core
3 November 2026
India’s packaged food and soap makers are running out of easy choices. Input costs have continued to rise since late February, when the Middle East conflict began disrupting supply chains and pushing up crude-linked costs.
A visible price hike, however, risks sending shoppers to a rival. To offset this, companies have reduced package sizes. However, scope for how much these packs can be reduced is limited, especially for products already sold at low price points. Take the example of a Rs 10 pack of Parle-G biscuits.
At this price, there is little room to reduce the quantity further without risking consumer dissatisfaction. Cutting the pack size could make the product less attractive, while increasing the price may discourage price-sensitive buyers.
India’s FMCG giants have squeezed pack sizes about as far as they can go. With input costs still climbing and shoppers watching every rupee, the choice between eating the cost and raising prices is coming, likely right after Diwali.
The Hikes Are In
Britannia, Hindustan Unilever (HUL), Dabur and Godrej Consumer had already raised prices by around 2-5% in the June quarter, and were weighing more for the September quarter. FMCG companies have continued to raise prices to offset higher input costs.
FMCG companies have continued to raise prices to offset higher input costs.
Tata Consumer Products increased tea prices by 8-10% between the June and September quarters, while it raised the price of its Rs 30 salt pack to Rs 32 in May and again to Rs 34 in October.
Hindustan Unilever also took price increases of around 7.5% during the September quarter, according to media reports.
Godrej Consumer Products said it would continue calibrated price increases, particularly in soaps and liquid detergents, to manage cost pressures.
Dabur has also confirmed taking pricing actions in its October business update, while Britannia had indicated a further 1.5-2% increase, largely through smaller packs. However, the latter two companies’ September-quarter results were still awaited.
Experts said that lower-income households face greater pressure because everyday essentials take up a larger share of their budgets. Affordable products such as biscuits, noodles, soaps, detergents and cooking oils are particularly sensitive to price changes.
According to experts, some manufacturers are weighing selective price increases after Diwali, possibly from December.
Shoppers haven’t walked away yet
So far, demand is holding up. Nestlé India’s sales rose 20.5 per cent to Rs 6,782 crore in the September quarter, with double-digit volume growth.
At HUL, June-quarter underlying sales growth of 10 per cent came equally from volume and price.
The market is still nervous.
Nestlé India shares closed 7.7% lower on results day after management flagged rising input costs, especially packaging, edible oils and farm commodities.
Business Standard quoted chairman Manish Tiwary as saying, “Rising inflation, particularly food inflation, is a reality.”
India’s FMCG volume growth remains mixed, although several companies continue to report resilient demand. Tata Consumer Products’ India branded volume growth eased from 16% in Q4 FY26 to 13% in Q1 FY27 and 11% in Q2 FY27.
Marico reported that India volume growth reached near double digits in Q2 FY27, following 11% in Q1.
Dabur India recorded 5% underlying volume growth in Q1 FY27, while its October update indicated double-digit revenue growth for Q2 but did not disclose a confirmed volume figure.
Overall, demand remains resilient, but revenue growth should not be confused with volume growth, particularly as companies raise prices to offset higher input costs.
Why Smaller Packs?
Satish Meena, founder of research firm Datum Intelligence, said that companies try to absorb costs first. “They can do it for one quarter, they can do it for two quarters, but at a certain point they have to pass it on to the customer,” he said. He expects much of that to happen after the festive season.
Discounts are not an option either, since margins are thin. That leaves pack sizes. “Instead of 150 grams, we are doing 120 grams, keeping the price the same,” Meena said, describing the move.
A visible price rise carries a risk of its own.
“Your positioning in the shop will change, and customers will also perceive you as an expensive product and look for other brands,” he said. Once a rival takes the shelf space, it is hard to win it back.
Devangshu Dutta, founder of research firm Third Eyesight, says price points are hard to move. “Price points are often anchored either in the consumer’s mind or by competitive benchmark pricing, making them difficult to change,” he said.
He also said the practice now carries a reputation risk. “The shrinkflation phenomenon isn’t new, but social media has given it viral visibility, which can potentially damage brand reputation.”
Pricing Pecking Order
Meena said companies will follow a set order. First they improve buying and supply chains, then trim ad spending. Next they raise prices on premium products, where buyers are more willing to pay. Raising prices across all products comes last, so they don’t lose share.
Dutta says companies are “caught in a vice” because input costs are rising while core shoppers are cautious about spending. Companies have “no option but to cut brand-level advertising and also review overheads deeply.”
Indian FMCG companies are facing rising input costs across several product categories.
In October 2026, plastic packaging costs were reported to have increased by 30–40%, putting pressure on snack makers and household-product manufacturers.
Palm oil prices rose 21% year-on-year in September, while sunflower oil increased 14%, soybean oil 9% and mustard oil 8%.
Sugar prices climbed 18% year-on-year, adding pressure on confectionery and packaged-food producers.
Tea prices rose 10% over the same period. Coffee and cocoa also recorded increases, with Arabica coffee up 19% quarter-on-quarter and cocoa rising 48%. These increases affect biscuits, noodles, chocolates, soaps, shampoos and detergents differently.
Now What?
The next test is HUL’s September-quarter results, due after its board meets on 28 October. Meena does not expect much to change in the next one to two quarters.
He says the pressure is not seasonal. “It’s because of the war happening in the Middle East… it’s a much longer issue for them,” and he points to RBI data showing some impact on demand.
Input-cost pressures could persist into early 2027.
S&P Global’s September outlook projected elevated manufacturing costs through 2027, while October data showed plastic packaging costs 30–40% higher and key polymer prices more than 50% above pre-conflict levels.
Although prices may ease if supply routes improve, these figures suggest FMCG companies could face continued cost pressure over the next two quarters.
Dutta said only a few brands will come through easily. “Few brands or products are able to build longer-term loyalty consistently and whose value to the consumer is stickier than the resistance to price movement.”
For everyone else, the room to raise prices or shrink packs is running out.
(Published in The Core)
admin
October 29, 2026
Pritha Pahari, The Core
29 Oct 2026
When ITC Ltd. launched Aashirvaad in May 2002, it sold one thing — whole wheat flour. The brand now has more than 200 SKUs across staples, spices, fresh foods and frozen foods.
ITC wants to double what Indians spend on Aashirvaad to Rs 20,000 crore in five years. It said growth will come from two places: more premium atta, and new categories around the Indian kitchen. That makes the brand a test of a hard question in packaged food. Can a name built on the purity of an ingredient win in the other segments and break out from its identity built around atta?
Trust in the purity of flour may not translate into trust in ready-to-eat meals, where taste, consistency and repeat purchases matter more. ITC itself has bought brands and built separate ones for some of these jobs.
A Big Target, A Soft Core
Hemant Malik, who runs ITC’s foods division, told PTI the company expects spending on Aashirvaad to double from above Rs 10,000 crore. That figure is what shoppers pay, including taxes and trade margins. It is not ITC’s revenue. The push comes as the core product slows. In the quarter ended June 30, ITC said atta was held back by heat waves, an LPG shortage and low wheat prices.
FMCG-Others revenue rose 12%, or 16% without staples, and dairy, snacks, noodles and frozen snacks each grew more than 20%. Not all of that belongs to Aashirvaad. Snacks, noodles and frozen foods sell under Bingo!, YiPPee! and ITC Master Chef.
The wider backdrop matters too. ITC is trying to rely less on cigarettes, which now face a sharp rise in tax.
Devangshu Dutta, founder of consultancy Third Eyesight, said value-added ready-to-cook and ready-to-eat products earn better gross margins than staples. Selling more of them would also help ITC use its factories more fully, he said.
ITC’s recent annual report shows multigrain atta, vermicelli and besan have grown threefold over five years, and now make up about 16% of the staples portfolio. ITC does not give a brand-level split between premium atta and new categories, or Aashirvaad’s profit.
ITC’s own Q1 FY27 release said atta performance was tempered by transient factors including heat waves, an LPG shortage and benign wheat prices. The FMCG-Others business grew 12% in the quarter.
The Easy Stretch
ITC said its value-added atta variants and staples-related products have grown three-fold in five years, and their share of the portfolio has doubled. They include besan, rava, vermicelli and soya chunks. The newest addition is chana sattu, first sold in Bihar, Jharkhand and West Bengal, with a Rs 10 pack that carries 10 grams of protein.
Suumit Kapoor, a brand growth consultant, calls these safe stretches. Besan and rava barely change what a shopper expects, he said. They are “still about what’s in the bag,” so purity still answers the question.
The Harder Jump
Ready-to-cook and ready-to-eat food asks something different. “Purity is a raw material promise. Ready to eat is a finished experience,” Kapoor said. Nobody buys a packaged curry because the dal was well sourced, he said. They buy it because they are hungry, short of time and hoping it tastes home-cooked.
ITC’s recent launches show it knows this. Its ready-to-cook chapati comes in packs of 10, with no preservatives and a shelf life of five to six days. The chutney and sambar range, launched in June, is made in small batches without preservatives and depends on a cold supply chain.
At launch it was sold only in Bengaluru through quick-commerce apps. The short shelf life answers a real problem.
Dutta said many shoppers prefer freshly cooked, hot meals and are wary of additives that extend shelf life. Cold chains remain patchy even in big cities, he said. A time-pressed household can also cook, order in, eat out or buy a packaged meal, and each choice is judged on price, convenience and taste.
Kapoor added a caution about ITC’s own numbers. They do not show whether shoppers buy the new products because of the Aashirvaad name, or simply because those categories are growing.
ITC’s latest results release names ready-to-cook chapati in a list of products but gives no sales figure for it, or for ready-to-eat meals. That may reflect how ITC groups its figures, not a change in plans.
Why One Name Still Makes Sense
Dutta sees a strong business case for using one name. A familiar brand cuts the cost of getting shoppers to try something new, he said, because Aashirvaad is already in millions of homes. New items can also move through ITC’s existing distribution, including modern trade and quick commerce, and retailers accept extensions from a leading brand more readily than unknown labels.
He also sees a defensive motive. Aashirvaad sits in everyday kitchen use, between ITC’s older gourmet line, Kitchens of India, and its snack-led Sunfeast. A bigger range puts it up against MTR, Haldiram’s and iD Fresh.
Tata Consumer said Tata Sampann grew 69% in Q4 FY26 with strong performance across categories. On the Q1 FY27 earnings call, CEO Sunil D’Souza said the core portfolio of pulses, spices, poha and vermicelli was growing at about 30%, with cold-pressed oils and dry fruits adding to that growth.
Poha and vermicelli are the closest items to convenience foods, but Tata doesn’t separate them out.
AWL Agri Business, which owns Fortune and Kohinoor, reported Q1 FY27 Food & FMCG revenue of Rs 1,726 crore, up 22%, with a segment EBITDA margin of 6%, and management said the Fortune and Kohinoor brands both grew at double-digit rates. AWL’s investor day deck also shows Kohinoor rising from Rs 150 crore in FY23 to over Rs 400 crore in FY26.
Not Betting Only On The Name
ITC’s record suggests it does not rely on one brand for everything.
It launched Kitchens of India in 2001 as a separate premium name, using the dishes of its hotel restaurants. It bought the spices brand Sunrise in 2020. In February 2025, it agreed to buy Prasuma, a frozen and ready-to-cook company, starting with a 43.8% stake. Sproutlife Foods, the Yogabar business, became a subsidiary on April 1.
Mint reported in February 2025, citing two unnamed people, that ITC was in early talks to buy MTR Foods and Eastern Condiments from Norway’s Orkla for about $1.4 billion. Orkla said it does not comment on rumours. ITC did not reply to Mint. No deal followed.
Kapoor reads such moves as ITC buying skills it lacks, not as proof that Aashirvaad cannot stretch.
ITC is also putting weight behind fresh food. Its fresh food business, which includes a brand called ITC Aashirvaad Soul Creations, grew gross order value 90% in the quarter, passed an annual revenue run rate of Rs 300 crore and now runs 75 cloud kitchens in five cities.
What Comes Next
The company’s position is strongest where the brand started. In July, ITC said it had already secured 95% of the wheat of the quality needed for Aashirvaad atta, but it also warned that monsoon rains were short and El Niño could hurt growth.
Value-added atta variants and staples adjacencies have grown three-fold over five years, and Aashirvaad Svasti dairy is among its fastest-growing categories, but neither is a meal category.
The newest meal-type launches, such as ready-to-cook chapatis, frozen naans and parathas, and fresh chutneys and sambar, have no disclosed sales or repeat-purchase data.
ITC launched Aashirvaad ReadyMeals back in 2003 and still describes ready-to-cook as a new bet, and it markets other finished-food lines under separate brands (Kitchens of India, ITC Master Chef, Prasuma), which suggests it doesn’t simply assume the Aashirvaad name carries into every meal category.
Management frames success around product innovation and differentiation, not brand trust alone. The larger test is on the shelf.
Kapoor said staples-linked products can keep drawing on Aashirvaad’s purity, but anything close to a finished meal has to earn a name for taste and consistency. Whether shoppers will pay for that under the Aashirvaad label is what ITC’s Rs 20,000 crore target depends on.
(Published in The Core)
admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
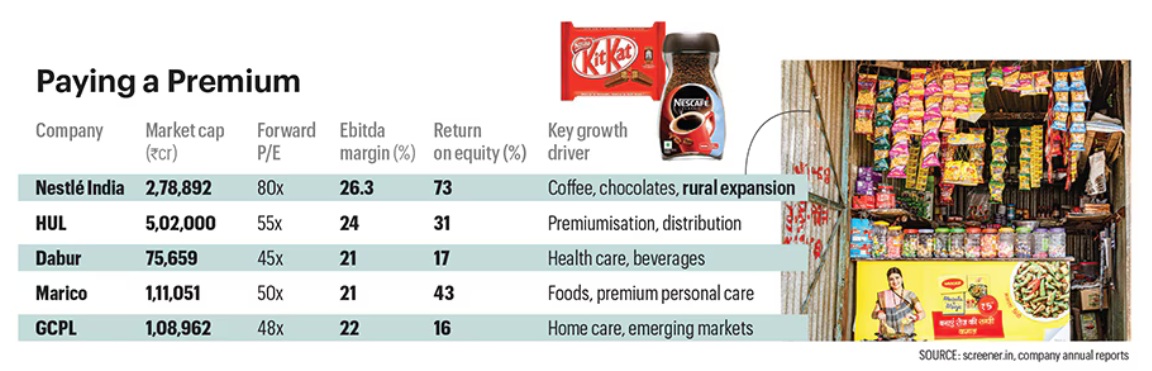
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
admin
August 6, 2026
Pritha Pahari, The Core
5 Aug 2026
Saurav, a 27-year-old resident of Navi Mumbai, has bought the same tub of whey protein for three years, same brand, same 1kg pack, same monthly ritual after his gym membership renews.
Last month, at checkout, the price had jumped by nearly a thousand rupees. He assumed it was maybe a limited-time markup. But when he checked his order history, he noticed that the price had been going up for two to three months until it crossed a threshold that made him realise that whey protein has gradually become more expensive.
India is the world’s largest milk producer, yet it imports most of its whey protein because its dairy sector was never built to make cheese, the one thing that whey needs to exist.
That gap is now colliding with a global protein boom, driven partly by weight-loss drugs that leave patients needing more protein.
The result is a price rise that is now reaching the local pharmacy and fitness stores, and one that is unlikely to recede.
The Price Move
Research firm, The Daily Datum analysed Keepa price data for 11 whey protein SKUs on Amazon and found an average price increase of 32% and a median rise of 27% across varying tracking periods.
Keepa is a third-party price-tracking tool for Amazon, it logs a product’s price history over time by continuously scraping Amazon’s listing pages, so you can see a graph of how a specific SKU’s price has moved (sales, hikes, restocks) going back months or years.
Prices of different types of proteins i.e. blends, isolates and concentrates have all moved by similar amounts, and so have Indian D2C brands and long-established imported ones.
In protein powder terms, concentrates are ~70-80% protein (less processed, retain more fats/carbs), isolates are ~90%+ protein (more filtered, less lactose/fat), and blends mix two or more protein types (e.g., whey + casein, or whey concentrate + isolate) to combine benefits like fast and slow absorption.
The one outlier, MuscleBlaze’s premium Biozyme Performance line, has roughly doubled, but excluding it, the category average is still 26%, about five times India’s headline food inflation, which stood at 5.32% year-on-year in June 2026, according to government data.
The retail prices are only a reflection of what is happening with the raw ingredients needed for whey.
Imported whey protein concentrate landed in India at roughly Rs 700–800 per kg in 2024; by mid-2026, the industry estimates put it at Rs 2,300–3,000 per kg, a rise of over 200%.
Brands have absorbed much of that shock through smaller pack sizes and blended formulations rather than passing it straight through, which is why retail prices have risen a fraction of what the raw material has.
For scale, India’s protein supplement market (powders, bars and ready-to-drink shakes together) is put at roughly $860 million to just over $1 billion in 2025, though the exact figure depends a lot on which research firm and which product categories you ask (IMARC Group and Grand View Research land in that range but don’t agree closely). That compares with a global protein supplements market well above $30 billion.
Not A Farmed Commodity
“You don’t milk a cow for whey. You milk a cow for milk. And then you have to make cheese,” said Rajiv Mitra, Strategic Advisor, Sonai Dairy, a Maharashtra based dairy.
Whey from cheese-making is “sweet whey”, protein-rich and further processed through filtration and expensive drying infrastructure into the 80–90% protein concentrate that ends up in a gym-goer’s scoop.
“This is a structural bottleneck,” Mitra said. “It’s not a kind of seasonal commodity up and down.” New filtration and drying plants can take two to four years to build, with much of the machinery imported.
This is where India’s dairy habits work against it.
Devangshu Dutta, founder of the retail consultancy Third Eyesight, while speaking to The Core explained that globally, about 95% of whey protein comes as a co-product of Western-style hard and semi-hard cheeses such as cheddar and mozzarella. India’s dairy sector, by contrast, is built around paneer, curd, khoya and ghee.
Paneer is made by acid coagulation, which produces “acid whey”, lower in protein and higher in minerals, and not suitable for concentration into protein powder.
“Unless consumption of western-style cheeses grows dramatically in India, co-production capacity will remain low,” Dutta said.
Mitra makes the same point from the kitchen rather than the factory floor: squeeze lemon into milk to make paneer at home and the liquid that separates out simply gets drained. “Traditionally, for years, while we have been the highest producer of milk, our consumption pattern is such that we do not harness the whey that is produced,” he said.
That liquid is easy to overlook because it looks like nothing more than watery runoff, but it isn’t a waste.
When milk curdles, the solid part becomes paneer or cheese, and the yellowish liquid left behind, the whey, still carries a meaningful share of the milk’s protein along with lactose and minerals.
Filtered, concentrated and dried at an industrial scale, that liquid becomes the powder sold in tubs as whey protein concentrate or isolate. In most Indian kitchens it is simply poured away; in a cheese-and-whey-processing economy like the US or Europe’s, it is captured and turned into a saleable ingredient.
That gap between what gets thrown out and what gets processed is the crux of the shortage.
Why It’s Getting More Expensive
India imports an estimated 80–90% of its supplement-grade whey, mostly from the US, Europe, New Zealand and Australia, in dollars. The rupee has weakened sharply against the dollar over the past few years, from around 74 to nearly 97 by July 2026, adding another 10–15% to landed cost before customs and tax.
India’s own import policy adds a further layer of cost. Dairy is among the most protected sectors in the Indian economy: duties on whey, cheese and milk powder run 30–60% depending on the product, India offers no duty-free quota for dairy, and the government has repeatedly kept dairy outside trade negotiations, including in the interim India–US trade agreement reached in early 2026.
US suppliers, the world’s largest whey producers, also frequently fall short of the vegetarian-rennet certification Indian food rules require, which further narrows where Indian buyers can import from. None of this caused the current price spike, but it does mean India pays a built-in premium over the raw international price, and there is no sign of that premium being negotiated away soon.
Global demand, meanwhile, keeps climbing while milk output in the US and Europe grows only slowly. The global whey protein market is put at roughly $9.7 billion in 2025 by one widely cited estimate (Grand View Research).
It has clearly grown a lot over the past decade, but market-research firms disagree fairly widely on the starting point and pace of that growth.
Mitra pointed to a newer driver on top of the usual sports-nutrition demand: GLP-1 weight-loss drugs.
“Doctors have asked patients to consume more protein” to offset muscle loss from the drugs, he said, and as patents expire and generics spread to India and China, “the demand-supply gap is definitely going to increase further.”
(Some industry commentary points to semaglutide patents lapsing in markets including India and China around 2026, which would open the door to cheaper generics, though this detail comes from a single industry source and is worth treating as a general trend rather than a confirmed date.)
He laid out what he called a three-pronged squeeze: India’s own GLP-1 users will need more protein even as domestic production stays constrained; the US and Europe, which used to export surplus whey, will increasingly consume it themselves as their own GLP-1 use grows; and India’s roughly 30% vegetarian population, which depends on dairy for protein, will lean on it even harder.
Ingredient suppliers and dairy processors abroad broadly back this account, at least directionally, though they are careful not to call GLP-1 the sole cause. In wire-service and trade-press interviews, executives at FrieslandCampina and Lactalis have cited the weight-loss drug trend by name as a reason for new investment in high-protein whey processing, and StoneX’s dairy consulting head has said the food industry simply lacks the capacity to turn whey into the concentrates and isolates the market now wants. Those are real, on-record statements, but they’re a handful of quotes, not a market-wide survey, so it would be a stretch to read them as proof that GLP-1 is now a dominant driver.
The macro numbers, where they exist, suggest a more modest picture: one investment-bank estimate (cited secondhand rather than pulled from the original research note) put GLP-1’s impact on total European calorie demand at around a quarter of one percent, since only a low single-digit percentage of the population is on the drugs so far.
Separately, some retail-data providers have reported that households with a GLP-1 user spend noticeably more on protein-rich products than matched non-user households.
Taken together, traditional sports-nutrition and everyday-fitness demand almost certainly remains the larger base of whey consumption, GLP-1 use is a real and fast-growing add-on that industry executives say is starting to show up in sourcing decisions, but nobody has published a solid, independently verified number for how much of the current price spike GLP-1 specifically accounts for. Anyone who tells you an exact percentage is guessing.
Who Feels It First?
Large manufacturers are better insulated than small ones.
“The bigger players always get into long-term contracts,” Mitra said. Smaller brands and contract manufacturers, reliant on buying at spot prices, “get squeezed first.”
Big companies can also cross-subsidise from other product lines for a while, he said, but that isn’t a permanent fix: “Businesses are not there to absorb cost. Businesses are there to make profit.” Margin compression, in his words, “is never sustainable.”
An executive at HealthKart, which owns MuscleBlaze, was quoted saying in an Financial Express article that whey concentrate costs have more than tripled in two years and are “quickly approaching 4x,” and that the company has raised prices while absorbing part of the increase itself.
The founder of Wellbeing Nutrition was quoted in the same Financial Express article saying whey isolate prices have roughly tripled over the same period, and that whey, which makes up 15–20% of the company’s revenue, is now being promoted less actively as a result.
The founder of The Whole Truth, a clean-label brand that also uses cashews and cocoa, was quoted in the same article in Financial Express, saying input costs across its ingredient list have surged and that the company has pushed through several price increases, including a 15–20% hike on protein bars, rather than change its recipe.
Budget-focused brands such as Nakpro, AS-IT-IS and Avvatar have not made similar public statements, but their pricing sits in the same band as the rest of the market, and their category positioning, cheaper, no-frills whey aimed at price-sensitive buyers, looks consistent with the same cost pressure, even without a direct quote confirming it.
Smaller sachet and single-serve formats, which let a brand hold a lower shelf price even as the cost per kilogram rises, have also become more common across the category over the past year, though this is more an observed pattern than something brands have explained on the record.
Consumers shouldn’t expect quick relief either. “Commodity prices normally fall before retail prices,” Mitra said.
Existing contracts and retail pricing cycles are sticky, so the consumer will see relief much later than any drop in the raw material.
Some Headroom, No Quick Fix
Both experts see room for India to produce more eventually.
Dutta noted that rising protein-consciousness and GLP-1 adoption are giving Indian manufacturers “headroom for growth,” though feedstock constraints will remain a challenge.
Mitra talked about the scale needed: new capacity requires a couple of hundred crores of investment and years to commission, on top of a slow, generational shift in how Indians eat dairy. Cold storage for hard cheeses, which need months of ageing, is also still being built out.
Some of that investment is already happening.
Amul has launched a whey protein line priced well below imported brands, part of a broader push by Indian dairy majors to move into higher-margin, value-added products; cheese and whey can carry margins of 25–45%, against much thinner margins on liquid milk.
Parag Milk Foods already sells whey protein under its Avvatar brand and has positioned itself as a nutrition company rather than a pure dairy one.
Milky Mist, which is preparing a stock market listing, has said it will use part of the proceeds to add new production lines for whey protein concentrate, yoghurt and cream cheese at its Tamil Nadu plant.
Cheese-focused players including Schreiber Dynamix, Britannia Bel Foods and Lactalis India are separately expanding capacity, since more cheese production is what generates more whey as a by-product in the first place.
None of these projects will materially add to supply in the next year or two; dairy-processing plants of this kind typically take two to four years from investment to commissioning, and most industry estimates suggest India’s domestic whey production still covers only a small fraction of what the country consumes.
Neither expert expects plant-based protein to substitute for whey in a hurry. “Whey still offers a superior amino acid profile” and better digestibility, Mitra said, predicting diversification and hybrid blends rather than replacement.
What Could Break the Cycle?
Globally, the shortage is widely described by dairy analysts as a processing bottleneck rather than a milk shortage: milk supply itself has been broadly stable, and cheese production, which generates whey, has continued at normal levels. The constraint is the specialised filtration and drying capacity needed to turn liquid whey into the concentrated, dried powder the supplement industry uses, and that capacity takes years to build.
Major producers, including Glanbia, Fonterra, Arla, Tirlán and Idaho Milk Products, have announced billions of dollars of new whey-processing investment in the US, Europe and New Zealand over the past year. Most of these projects are expected to come online through 2027, not before, so global analysts generally don’t expect meaningful supply relief until late 2026 at the earliest, and more likely 2027.
US milk production is forecast to keep growing gradually into 2027 as well, which should help at the margin, though rising input costs (energy, feed, financing) are also squeezing dairy farmer margins in exporting regions, which cuts the other way.
For India specifically, easing would most likely need several things to move together over the next two to three years: new domestic processing capacity from players like Amul, Parag, Milky Mist and the cheese-focused majors actually coming online, rather than merely being announced; global WPC and WPI supply catching up with demand as the 2026–27 capacity wave lands; a stabler or stronger rupee, since a large share of India’s whey is still imported and priced in dollars; and some change to India’s own tariff and certification structure on dairy imports, which currently adds cost on top of the global price and shows no sign of loosening given how firmly successive governments have kept dairy out of trade deals.
GLP-1-driven demand would also need to plateau rather than keep accelerating as drug prices fall and generics spread.
Even if all of that happens, retail prices in India are unlikely to fall quickly. Brands are currently absorbing part of the cost increase rather than passing all of it through, which means a chunk of any future relief in the raw material would likely go toward rebuilding margins before it reaches the shelf.
Contracts, inventory cycles and psychological pricing (brands are usually slower to cut prices than to raise them) add further lag. Mitra’s framing captures this: raw material costs typically fall before retail prices do, and the gap between the two can run into quarters, not weeks.
What experts keep coming back to is that this has stopped being a niche fitness-industry story. “
This is no longer just about dairy,” Mitra said. It is now about healthcare, pharmaceuticals, nutrition, overall food.
(Published in The Core)
admin
July 9, 2026
Neethi Lisa Rojan & Vaeshnavi Kasthuril, MINT
Mumbai/Bengaluru, 8 July 2026
The collapse of the US-Iran peace deal in less than a month has rattled India’s consumer sector, reviving fears that higher oil prices and fresh supply-chain disruptions could squeeze demand just as companies were betting on a broader recovery.
The renewed uncertainty followed US President Donald Trump’s declaration on Wednesday that the peace deal with Iran was effectively over, alongside Washington’s decision to end a sanctions waiver on Iranian energy supplies. The market reaction was swift. The Nifty FMCG Index fell 2.49% on Wednesday, underperforming the broader market as all 15 constituents declined, led by Dabur India, Hindustan Unilever, and Tata Consumer Products, whose shares fell 3-4% each. The benchmark Nifty50 ended 2.12% lower after renewed hostilities in West Asia pushed crude prices higher.
Executives and analysts said companies have little room to respond immediately, leaving them to closely monitor devel opments as risks to costs and consumer spending mount. “I don’t think companies can react on this kind of a short notice,” said Arvind Singhal, chairman of consulting firm The Knowledge Company. “It takes 2-6 months to make any change in your plans and strategy. I think right now the Indian FMCG (fast moving consumer goods) companies will be watching the progress of monsoon more carefully than the Strait of Hormuz.”
Even after the US-Iran peace deal took effect on 18 June, consumer companies were unlikely to have expected immediate relief, analysts said.
“While everyone hoped for a cessation in hostilities, smart management teams would work on the realistic expectation that even with a ceasefire, pent-up supply chain input costs need to be absorbed over time, and pricing plans must be factored accordingly,” Devangshu Dutta, founder and chief executive of consulting firm Third Eyesight, said.
“Given that the conflict zone is active, I don’t think there is any immediate likelihood of pricing freeze or reductions, even though demand in rural areas as well as in lower-income urban segments is likely to be hit from both sides ― earnings and expenses.”
Large consumer goods companies including Dabur, Emami and Godrej Consumer had recently told investors they remained confident about consumer demand, including in rural markets.
But the renewed rise in crude prices, coupled with erratic monsoons marked by rainfall deficit in some regions and flooding in others, threatens to complicate that outlook. Higher fuel costs could lift prices of crude-linked raw materials such as plastic packaging and ingredients used in soaps and creams, while persistent inflation could push consumers to cut discretionary apne ding and trade down even on staples.
Major consumer companies had already raised prices or reduced grammage across packaged food, beverages and personal care products in the March quarter.
“As far as the crude prices are concerned, that is probably the only variable where the government has to decide as far as pricing of crude or the petroleum in India is concerned,” Singhal said.
That comes at an awkward time for India’s largest consumer companies, including Hindustan Unilever, which had earlier this year told analysts they intended to drive growth through higher volumes rather than price increases. A renewed bout of inflation could undermine that strategy.
(Published in MINT)
