
admin
September 1, 2026
Pritha Pahari, The Core
1 September 2026
Reliance has spent more than a decade bringing together a long list of names such as Burberry and Tiffany & Co. to India. Its latest focus seems to be luxury celebrity brands, adding global pop star Rihanna’s Fenty Beauty and now media personality Kim Kardashian’s shapewear label SKIMS to its luxury brands portfolio.
Isha Ambani, executive director of Reliance Retail, has fronted most of these announcements herself.
Meanwhile, Nykaa, the beauty platform Reliance Retail keeps getting compared to, spent the last year going after some of the same celebrity founders.
In August 2025, Fenty Beauty moved from Nykaa’s platform to an exclusive deal with Reliance’s Sephora India and Tira. In June 2026, Nykaa answered by signing pop star Selena Gomez’s Rare Beauty. A month later, Reliance landed SKIMS.
India’s luxury and celebrity-brand market is split between Reliance’s scale and Nykaa’s beauty expertise, with Fenty, Rare Beauty and SKIMS showing how ownership, reach and brand fit are shaping who gets the biggest names.
Big Brands, Different Bets
Reliance wins brands through scale (20,169 stores, 396 million customers) and ownership ties; Fenty’s move to Sephora India is less a market choice than an internal LVMH routing decision, given LVMH’s stakes in both Fenty and Sephora.
But Nykaa is holding its own by competing on specialism, not size; its beauty-literate audience and curated community pulled in Rare Beauty and Chanel.
The brand fit, not just distribution muscle, still decides who signs where, and some brands (like Birkenstock) skip both platforms entirely.
The economics behind these deals are harder to pin down than the headlines suggest. None of the three — Fenty, Rare Beauty, or SKIMS — have disclosed minimum guarantees, royalty rates, or sales targets for their India entries; these are announced as partnerships, not filed joint ventures.
SKIMS raised $225 million in November 2025 at a $5 billion valuation, nearing $1 billion in annual net sales.
Fenty tells a different story: $450 million in 2024 sales, now valued at $1-2 billion, down sharply from a $2.8 billion estimate in 2021, with Jay-Z’s MarcyPen Capital Partners in talks to buy LVMH’s stake.
Rare Beauty’s India entry rides on Nykaa’s own momentum; the company’s revenue from operations rose 29% year on year (YoY) to Rs 2,782 crore in Q1 FY27, up from Rs 2,154.9 crore a year earlier. In the last quarter of FY26, revenue stood at Rs 2,648.1 crore.
The Core has reached out to Reliance and Nykaa for their response, and will update this report if and when they respond.
Why Fenty Chose Reliance
Fenty’s move looks more like an internal one, according to Suumit Kapoor, a brand growth consultant.
LVMH owns 50% of Fenty Beauty through its beauty incubator Kendo Brands, a stake it has held since co-founding the brand with Rihanna in 2017. LVMH also owns Sephora globally, and Sephora in India is run by Reliance.
“When Fenty enters a new market through Sephora, LVMH is effectively distributing its own equity stake through its own global retail infrastructure,” Kapoor said. For a brand with that kind of ownership overlap, he added, the choice of partner is “close to an internal routing decision” and not a genuine trade-off.
That ownership overlap is itself now in a pickle.
LVMH has been exploring a sale of its 50% Fenty stake since October 2025, working with investment bank Evercore, according to Reuters. As of June 2026, American rapper and businessman, Jay-Z’s investment firm MarcyPen Capital Partners was reported to be among the parties in talks to buy it.
No sale has closed yet, so the Reliance-Sephora-LVMH alignment still holds for now, but it isn’t guaranteed to outlast the current ownership structure.
Fenty’s India journey backs this up. The brand’s first India listing wasn’t through Reliance at all.
It ran on Nykaa’s Cross Border Store, a low-commitment digital shelf that was discontinued before Fenty’s August 2025 relaunch, an exclusive omnichannel deal with Reliance spanning more than 50 stores across 16 cities on day one.
Kapoor doesn’t think of the switch as a deliberate strategic upgrade.
“The Cross Border Store listing may simply have underperformed on its own terms, without much marketing support behind it,” he said, adding that there is no clear evidence that Reliance stole the brand away.
Devangshu Dutta, founder of the research firm Third Eyesight, said celebrity backing only buys a brand little room.
“When a company or an investor buys into an early-stage celebrity brand, they are acquiring instant brand equity which acts as a top-of-the-funnel magnet and potentially lower CAC,” he said. “However, the ‘fame premium’ runs out if product and service execution isn’t compelling enough to drive repeat business and customer retention.”
Ownership decides the biggest deals before “competition” even enters the picture, Fenty landed at Reliance’s Sephora because LVMH owns half of each, though that alignment is shakier than it looks, with Jay-Z’s MarcyPen Capital Partners now the leading bidder for LVMH’s Fenty stake.
Beyond ownership, it’s a straight trade-off.
For brands chasing scale, Reliance’s tens of thousands of stores will get you reach. If brands want to chase community, Rare Beauty did by picking Nykaa specifically to tap its affluent, digitally engaged beauty shoppers and build loyalty. Some brands skip the fight altogether, like Birkenstock, which walked into India solo.
The Distribution Gap
Where Reliance doesn’t need an ownership story to make its case is scale. Reliance Retail closed the quarter ended June 2026 with 20,169 stores across 78.4 million square feet, 396 million registered customers, and 568 million transactions in that single quarter, up 46% year on year, according to the company’s Q1 FY27 earnings release. JioMart alone served 5,500 pincodes through its rapid delivery network in the same period.
Nykaa, by comparison, operated 324 physical stores across 105 cities as of its FY26 numbers, with a cumulative customer base of around 42 million, per its own disclosures and Business Standard’s reporting on the company’s results.
“That gap generally buys a brand not just bigger numbers, but reaches into places where a beauty specialist has no reason to be,” Kapoor said. For brands thinking beyond beauty into wellness, gifting, or lifestyle crossovers, he said that scale “is not a nice-to-have. It is the entire argument for choosing Reliance over a beauty-only platform.”
Satish Meena, founder of Datum Intelligence, a research firm, made a similar point on Reliance’s pull with brands weighing an India entry.
“With the kind of strength they have, they can always give a better deal,” he said, referring to Reliance’s ability to commit capital and guarantee scale that a newer entrant typically cannot promise on its own. He pointed to Reliance’s existing retail relationships, including Marks & Spencer, as part of the track record that makes brands comfortable signing with the group.
Experts say over the past two to three years, Nykaa has been the more prolific launch platform for major international beauty brands, while Reliance has had greater strength in international luxury and fashion.
According to experts, Nykaa reported more than 70 luxury-brand additions over the last three years, including names such as NARS, Prada Beauty, La Prairie, Chanel Beauty, Armani Beauty and Maison Margiela. Reliance, meanwhile, has built a luxury portfolio spanning Valentino, Balenciaga, Bottega Veneta, Tiffany & Co., Burberry and others, and most recently brought SKIMS to India. Reliance’s public disclosures do not provide a comparable 2–3-year count of new international brand entries.
Reliance is arguably a major gateway for international luxury/fashion, but calling it the default gateway for international brands overall is too broad.
Where Nykaa Still Wins
Reliance’s advantage on raw numbers doesn’t fully explain why Nykaa keeps landing brands too.
Nykaa built its beauty audience before it built its stores, using tutorials and curated storytelling to create what Kapoor called “a beauty-literate customer base that arrives already primed to trust the platform’s recommendations.”
That specialism is what pulled in Rare Beauty. Nykaa’s June 2026 launch made the brand available through its website, app, and 30 stores nationwide, and came from a company reporting its highest quarterly profit since listing at the time, per its own disclosures.
In a company statement announcing the launch, Anchit Nayar, Nykaa Beauty’s executive director and CEO, said the brand fit a “new generation of highly informed and globally engaged consumers seeking elevated brand experiences.” Rare Beauty’s chief executive, Scott Friedman, said in the same announcement that India was “a very important market” for the brand, citing Nykaa’s beauty community in the country as the reason to partner with it specifically.
Nykaa has run a similar playbook before. Chanel strengthened its India fragrance and beauty presence on Nykaa in 2025, Obagi Medical entered India through the platform specifically for its clinically driven skincare positioning, and Estee Lauder’s incubation arm has run its India beauty programme, Beauty and You, with Nykaa as lead partner every year since 2022.
Dutta pointed to Kay Beauty, Nykaa’s own celebrity line with actor Katrina Kaif, as an example of why platform fit matters as much as platform size. Contrasting it with 82°E, actor Deepika Padukone’s skincare brand on Tira, he said Kay Beauty had two advantages: it was priced for a much larger audience, and it had “Nykaa’s active participation across channels for merchandising and visibility.”
Not The Only Door
Reliance’s pull is real, but it isn’t the only route into India.
Reliance benefits from international-brand partnerships through retail economics, distribution and, in some cases, ownership or joint-venture economics. The potential conflict emerges because Reliance can simultaneously act as a brand’s market-entry partner and control substantial retail and digital routes to consumers. Public filings, however, do not establish that Reliance uses this position to disadvantage partner brands or competing retailers.
Meena pointed to Birkenstock, which entered by opening its own stores rather than partnering with either platform. Birkenstock and similar labels operate as single-brand retail; they can use India’s foreign direct investment rules to set up shop directly, bypassing the need for a local partner altogether.
“If the brands think that they have enough pull in the market and they can bring customers, they are opening these stores without any partnership,” Meena said. He added that most global brands take the partner route anyway because India, for many of them, is still a small share of global sales, and testing the market with an established partner for a few years is lower risk than building from scratch.
Kapoor flagged one risk worth watching no matter which partner a brand picks. Exclusive deals give a retailer more control. But Tira has also started building its own private-label products, including a colour cosmetics line, and sells them in the same stores as the global brands it distributes.
“A retailer can be a brand’s distribution partner and, on an adjacent shelf, its competitor, at the same time,” he said, a tension he noted that Nykaa’s marketplace model, without a comparable private label push against premium brands, does not carry in the same way.
For brands already tied to Reliance through ownership, like Fenty, there isn’t much of a decision to make. For everyone else, Nykaa signing Rare Beauty and Reliance signing SKIMS within weeks of each other shows this fight for celebrity founders in India is far from over.
(Published in The Core)
admin
August 1, 2026
Murali K Menon, Firstpost
1 August 2026
The next time you are shopping for veggies on a quick commerce app, we’d suggest you hop onto the organic produce section and consider where those vegetables came from. Chances are, they have travelled through a supply chain pretty different from the one that bought veggies to your kitchen just five years ago. Some of that produce is supplied by Urban Farms Co., a little-known company that is rethinking food systems.
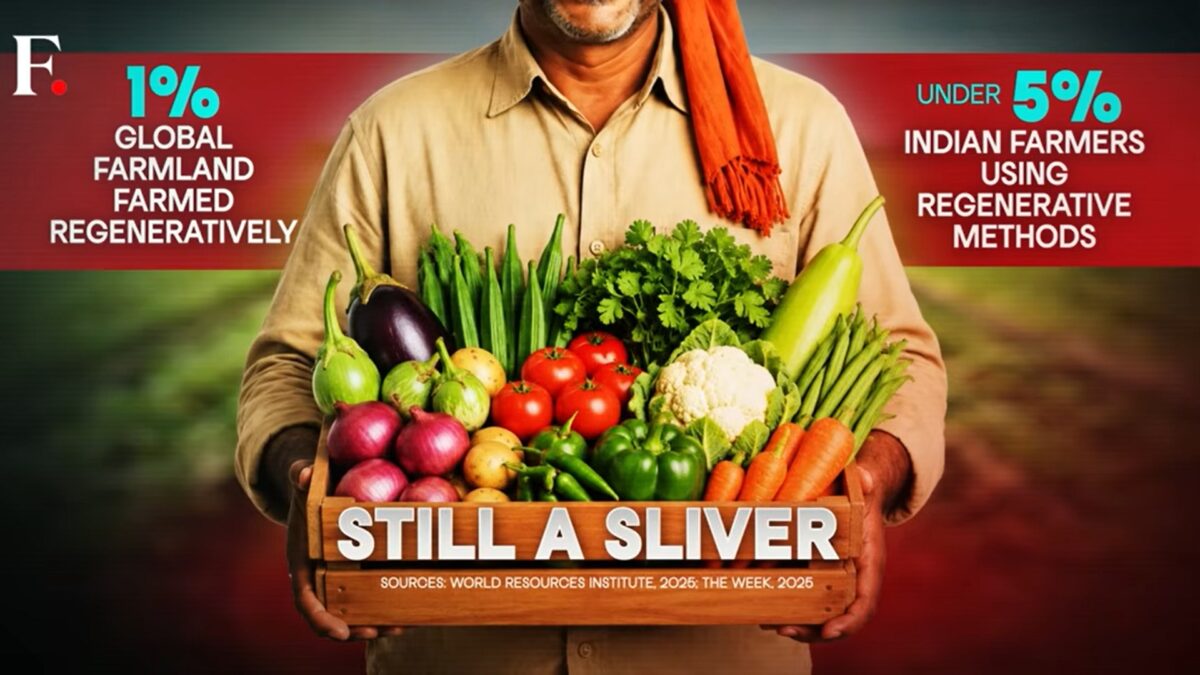
Urban Farms works with about 2,000 small farmers on the outskirts of several of India’s cities, as well as in states like Rajasthan and Maharashtra to grow vegetables using regenerative practices and supplies them to urban consumers via quick commerce and modern retail. The definition of renegenrative agriculture changes depending on who you ask, but broadly it refers to an approach that seeks to restore soil health, as opposed to conventional, chemical-intensive farming.
About 1% of global farmland is now under regenerative practices, according to a 2025 World Resources Institute study. Urban Farms, whose farmer network grows over 50 varieties of vegetables, handles around 12,000 tonnes annually and is targeting a twenty-fold jump in revenue from its current Rs 30 crore in the next five years.
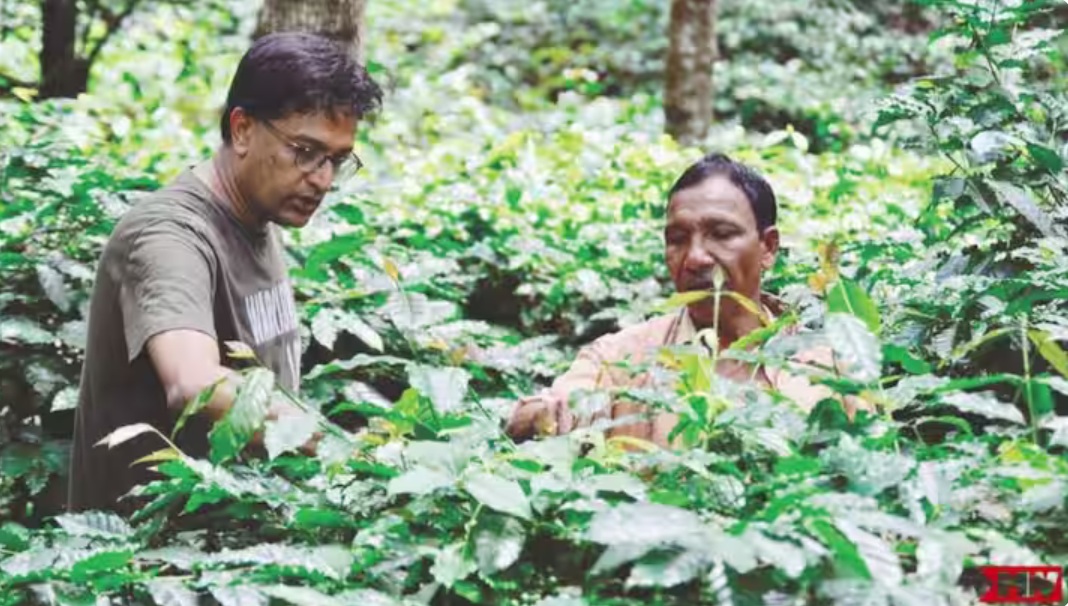
That target might sound ambitious until you look at its origins. Urban Farms was founded by members of the team behind Araku Coffee, the specialty coffee brand that put Indian coffee on the global map. Both Araku Coffee and Urban Farms are backed by the Hyderabad-based Naandi Foundation, among the country’s largest, multi-sector non-profits. The NGO was set up by Dr. Reddy’s Laboratories founder, the late Kallam Anji Reddy, and counts Kris Gopalakrishnan and Anand Mahindra on its board.
The broad details of Araku Coffee’s success are well known, but the model that underpins it is much less discussed. Over two decades, the project worked with thousands of tribal farmers to promote regenerative farming practices, restore degraded land, and improve farmer incomes while building a globally recognised premium coffee brand. The same spirit animates Urban Farms. Instead of tribal farmers, it works with small farmers on the outskirts of India’s cities. Instead of a premium export crop, it is betting on everyday vegetables sold through quick commerce and modern retail. But can a model proven in a premium niche survive in the toughest, most commoditised part of Indian agriculture?
Beyond coffee
Coffee was just a conversation-starter, says Manoj Kumar, the lead architect of the Araku Coffee project and the founding CEO of the Naandi Foundation. The developmental economist says that the project proved two things. “It proved at scale that our regenerative organic agricultural science worked for 20 years in every crop, from coffee to millet, consistently season after season, without any drop in yield. And, just as importantly, that we could do world-class excellence at scale with very ordinary poor people.”
The eventual goal was improving farmer economics. “In India, 85% of farmers have less than one hectare of land,” Kumar says. “The question is: what do we do with small and marginal farmers?” Urban Farms is one answer to that question. Unlike Araku Coffee, though, it isn’t built around a single crop.
“Urban Farms is about doing a system change. We are changing food systems,” says Vikash Abraham, the company’s CEO. So, what does that mean for something as everyday as a lady finger? Before it reaches your kitchen, Urban Farms is involved in almost every stage of its journey. It supplies regenerative fertilisers to farmers, works with them through the growing season, buys back their produce, and sells it to retailers and quick commerce platforms.
Urban Farms
“We procure from the farmer at the same price as conventional produce. We do not pay a premium per kilogram because we believe profitability is about cost of cultivation versus the entire income you get from your farm,” Abraham says. In other words, with Urban Farms, farmers don’t earn more because they sell lady finger at a higher price. They earn more because regenerative farming lowers their costs while giving them an assured buyer. A typical vegetable grower could earn as much as Rs 20,000 to Rs 30,000 more per acre annually, says Abraham, with savings increasing over time. A first-season comparison conducted by the company across 56.5 acres in Wardha, Maharashtra, found that soybean yields rose 12% and total cultivation costs fell by 8%.
Spending on farm inputs dipped from ₹9,750 to ₹5,267 per acre, while profits increased from ₹12,550 to ₹19,195. The model does not rely on government subsidies and farmers pay for the inputs themselves. According to Abraham, Urban Farms doesn’t approach farmers from a moral standpoint, or talk about climate change. “We go to them with a business proposition, and the business proposition is about making profitability.”
From trial to habit
Urban Farms’ residue-free vegetables generally cost about 40% more than conventional produce, although the gap varies by crop, market prices, and platforms. Lady finger, for instance, was priced at ₹24 for a 250gm pack on Zepto in Azadpur, in north Delhi, earlier this week compared with ₹17 for conventional produce; on Blinkit, the same pack was sold at ₹35.
Quick commerce accounts for 65% of its business under the residue-free category, with modern trade and other channels making up the rest. Abraham says part of that premium reflects the cost of maintaining a separate, traceable supply chain. The company supplies Blinkit, Zepto, Swiggy, and Flipkart as well as Reliance, Jubilant, and Country Delight, among others.
Devangshu Dutta, founder of retail consultancy Third Eyesight, says that he expects demand to grow, as incomes rise and consumers become more conscious of the food they are eating. But he thinks a 40% premium may be too high for regular consumption because vegetables, unlike coffee or craft chocolate, are staples.
“You could have a premium of maybe 20% to 30%. Some products could be higher than that, but that is something that has to be managed carefully.” For category growth to accelerate, he says, the produce must become “a fixture in the consumer’s pantry, in the consumer’s kitchen, on the consumer’s plate.”
Dutta believes that quick commerce is well-suited to fresh produce because Indian households have traditionally bought vegetables frequently rather than stocking up. “The bottleneck really is having the product range that consumers will buy over a period of time again and again.” That requires farmers growing different crops across regions and climatic zones. And building a wide range of vegetables also means working with farmers and ensuring farmer retention in the system season after season. “You don’t just sign up a farmer and say he’s going to be there forever,” Dutta says.
Urban Farms says it has managed to do that so far. In May this year, Anand Mahindra posted on X that 80 to 90% of the farmers who work with the company return every season. “Not out of loyalty to a movement, but because the economics work,” he wrote, pointing to yields comparable with conventional farming, lower input costs and produce that consistently tests residue-free.
Abraham says that Urban Farms would like to work with about 100,000 farmers by 2030, and the company’s growth will depend on how quickly it can both build and nurture relationships with its partners across the country. Applying the Araku model to a far more unpredictable market won’t be easy, but if Urban Farms can keep both farmers and shoppers in the system as it grows, coffee, as Manoj Kumar said, may indeed have been just the conversation-starter.
(Published in Firstpost)
admin
August 1, 2026
Two decades ago, the team at the Naandi Foundation turned tribal farmers in a remote Andhra valley into some of the world’s best-paid coffee growers. Araku Coffee now sells in Paris, and the best of it goes for thousands of rupees a kilogram. Now the same team is trying to do it again — this time with everyday vegetables. Their company, Urban Farms Co., works with regenerative farmers and sells their produce on apps like Blinkit and Zepto. The bet is that what worked for premium coffee can work for staples too. But vegetables aren’t coffee. They’re cheap, everyday, and something people buy all the time. Can this really scale, and does it actually leave farmers better off?
admin
March 1, 2026

Apoorva Mittal, Economic Times
1 March 2026
Resshmi Nair, 31, had grown used to the dotted red bumps on her arms. Her dermatologist diagnosed it as keratosis pilaris aka strawberry skin. It is a harmless skin condition that often affects legs and arms but Nair, a Mumbai-based marketing consultant, wanted it gone. She slathered lotions and salves but to no avail. Then she chanced upon an Instagram reel which showed an oil-based in-shower spray that promised to take care of her problem. “It was very tempting as it resonated with a personal concern,” she says. She is now on her third bottle. The bumps haven’t disappeared entirely, but they have become smaller, she says.
Like Nair, there are many who seek solutions tailormade for their beauty bugbears. Consumers who once searched for moisturisers and shampoos now look for niche products for hair and skin. They want to repair skin barrier, tame baby hairs and minimise facial pores.
A new generation of Indian beauty and personal care (BPC) brands are both listening to them and leading them. Focused products, they realise, could help them stand out in a crowded sector dominated by FMCG giants. While problems like acne, frizzy hair and rough skin have always been around, experts say the commercial importance of solving them narrowly and packaging that specificity as a brand strategy have become more intense of late.
India’s direct-to-consumer (D2C) beauty and personal care market—which is heavily invested in micro-problem targeting—is estimated to be $4.5 billion in FY2025, according to consulting firm Redseer. The new-age brands could account for 25-35% of total BPC spends by 2030. “Three major factors have contributed to this: one, the rise of digital medium for both commerce and marketing, which created a segue for new brands to launch and scale; two, younger consumers (Gen Z and young millennials) have become ingredient literate and look for results over broad promises; and three, competitive intensity in the market is pressing brands to position as per the right niches,” says Kushal Bhatnagar, associate partner, Redseer.
The shift is measurable on beauty retailer Nykaa’s platform. “Consumer vocabulary is far more evolved,” says a company spokesperson. Searches driven by specic concerns or ingredients are growing faster than broad category items. While foundational concerns like acne and brightening remain relevant, the platform is seeing strong growth in queries around pigmentation, barrier repair, pore care and specic hair issues. “This fragmentation is actually a sign of a more informed and aware consumer base,” the spokesperson adds.
ZOOMING IN
For young D2C brands, this behavioural shift has opened a narrow but potent entry point. Instead of launching another shampoo or moisturiser, they launch a product targeting a single problem and market it in an easily demonstrable short-video format. In the current beauty landscape, the market has shifted from general solutions to hyper-targeted efficacy.
Moxie Beauty, founded by Nikita Khanna in 2023, illustrates the playbook. Khanna, who previously worked at McKinsey, began with a focus on wavy and frizzy hair, a segment she herself belongs to. But it was one particular styling product, the flyaway hair stick, that went viral, propelling the brand into visibility. She says, “The wavy hair routine required us to educate people, which took time. But one can understand the flyaway wand in five seconds.” And it targeted what she calls a “widely held pain point”. That helped Moxie cut through crowded feeds and end up on consumer shelves. “Being synonymous with a category helps,” she says. “When people want a wax stick or flyaway stick, they search for our brand.”
That shift—from paying for visibility to being searched for directly—is critical in a market where customer acquisition costs (CAC) can be punishingly high. For many D2C brands, launching a sharply defined product is a way to reduce discovery friction and lower early-stage CAC. But a brand cannot be built or scaled on gimmicks, says Khanna. “If you solve only for what will look good in a video and will go viral, you won’t be able to scale. And if it’s a gimmick, people won’t repeat the purchase,” she adds.
Divanshee Jindal, cofounder of the brand The Solved Skin, says companies have to get the “product-communication fit” right. Her brand’s liquid pimple patch, which is designed to mask acne under makeup, is quickly emerging as its hero product. “People get excited when a product feels relatable and authentic,” says Jindal. “A new, convenient format that solves a real pain point makes consumers willing to try a new brand. But if it’s a standard product, say, a salicylic acid face wash, they will often default to a brand they already trust.”
SMALL IS BEAUTIFUL
The idea is to start small but evolve. Moxie, for instance, has moved beyond textured hair into solving broader “Indian hair problems” like damage repair and anti-dandruff that has brought in male consumers as well. “Curly or wavy hair was a huge, underserved problem,” says Khanna. “But the thought was always to solve other problems as well.” Moxie, which recently raised $15 million in a funding round led by Bessemer Venture Partners, says it has crossed Rs. 100 crore in annual recurring revenue on its two-year mark, and is seeing roughly 50% consumers coming back in six months across platforms. However, it says profitability is harder to crack because of intense competition from new brands and changing channel mix.
Mani Singhal, MD of the consulting firm Alvarez & Marsal, points out that most successful D2C brands started out with a sharply defined hero product. “Earlier it was natural vs chemical or price disruption; today it’s much more about efficacy proof, ingredient transparency, visible results and credible
storytelling,” she says.
From the manufacturer’s side, Nishit Dedhia of Kain Cosmeceuticals, a cosmetics manufacturing company, says, “It is easier today for brands to target special concerns. That specificity helps them build a differentiated product earlier on.” Most brands, he explains, x a major problem such as acne, dryness, pigmentation and then layer in a niche twist. Strawberry skin, once not a mainstream concern, is now a category. “People didn’t know the term. Once you give it a name, they identify with it,” he adds.
Dedhia describes the portfolio strategy as 8-2 or 9-1 where eight or nine products are general, incremental variations of core needs, while one or two are “category-building products” that require significant consumer education or product communication but create their own search demand. “That is the only way you get out of the vicious cycle of paying for visibility,” he says. “When people search for your brand directly, CAC comes down.”
Devangshu Dutta, founder of management consulting firm Third Eyesight, says micro-problem framing is “co-created” by consumers and companies. “The fragmentation is real, but the language used to describe it is heavily brand-driven,” he says. Terms like “strawberry skin” or “glass skin” correlate with influencer campaigns but label pre-existing dissatisfactions that mass products did not address sharply.
However, sometimes, in the race to differentiation, brands go for outlandish ideas. Dedhia says brands increasingly approach manufacturers with amusing asks in the quest to stand out. For instance, beard fillers packaged like mascara or plumpers for face and neck.
PRODUCE & PERISH
The problem is that the mortality rate of skincare brands is very high in India. Dedhia estimates that around 60% companies shut down in three years. Many brands burn through capital chasing ads and trends without building repeat customers or a community.
“For a brand to cross over from being a curiosity-driven purchase to being part of a regimen needs a minimum 25-30% of customers showing up as repeats after three months, while truly successful brands reach higher repeat numbers,” says Dutta.
Subscriptions are an even stronger test. “Generic formulations, me-too products and influencer spends can get you first users, but repeats will happen only from the user getting demonstrated value,” says Dutta.
But growth does not equal stability. CAC typically starts low for niche products, rises during scaling-up and stabilises only if organic demand takes over, says Bhatnagar of Redseer. Quick commerce accelerates discovery but compresses margins due to the high commission rates on these platforms, promotional expectations and lower average order values.
Singhal, who says a consolidation phase is underway, adds: “Niche entry can work extremely well if the problem is frequent enough and the solution is demonstrably effective.” Durable brands deliver consistent performance, build adjacencies beyond the first niche and maintain disciplined unit economics.
“If repeat rates don’t stabilise, economics becomes very challenging, very quickly.”
PERSONALISATION AHEAD
For Aparna Saxena, founder of Delhi-based beauty brand Antinorm, the next decade will be defined by even greater personalisation. Her brand has multifunctional products that are timesaving. Saxena says she surveyed about 250 women above 25 years of age and found that five-step routines typically do
not last after two months. Antinorm’s architecture rests on multifunctionality, like a leave-in cream that doubles as heat protectant and promises a “presentable” hair look without a blow-dry. Its most popular product is a spray that cleanses and moisturises, which they dub as “instant shower” or “facial in a flash”.
She says the brand, which launched in July last year, will close next fiscal with about Rs. 25 crore in revenue. Repeat rates are currently under 25% “because the denominator is expanding rapidly”, she adds. “Between 2020 and 2025, customers moved away from incumbents and got used to having options and trying newer brands,” she says. “Now they have routines in place. The next five years will be defined by more and more personalisation and micro-problem solving.” The beauty is about to go really skin deep.
(Published in Economic Times)
admin
January 17, 2026
Prachi Srivastava, Hindustan Times
January 16, 2026
We keep telling ourselves that 2026 will be the year of budgeting. So, we’ve cut back on weekend brunch, paused Zara hauls, are collecting every coupon code we can, and are furiously spinning the wheel of luck on every site’s pop-up box. One thing that’s making it a little easier: Mini-sized luxury.
We’ve been here before. India’s sachet and sample-size products have been so successful, they’re studied in business school. We’ve lived through the beauty-box-subscription revolution (we still have the empty pouches somewhere). We’ve sprung for discovery kits on Nykaa and Tira (those 7ml doses will never make a difference, but still…). But luxury in small sizes? In this economy, when we’re budgeting and still craving pick-me-ups, it’s an idea whose time has come.
Everyone’s doing fun-size now: There’s one-day-use SPF as a handbag charm, tiny tubes of mascara, three-spritz niche perfumes. There are advent calendars – 30-day boxed sets for December, promising big savings. But also tasting jars of chilli-oil, one-hour-burn micro candles, single-wash detergent pods, even a single-cup insulated flask for your morning brew.
They all have starring roles in What’s in My Bag videos and GRWM reels. “Mini-product content sees higher engagement because it’s visually satisfying,” says beauty influencer Preiti Bhamra (@PreitiBhamra). “The contrast of a big hand holding a tiny product instantly catches attention.” Minis are deliberately packaged in the same style as a full-sized product, for better brand recognition. They photograph better too. Plus, think of how many more treats can fit on a shelf or a handbag, if they’re a smaller size.
Thinking small
Minis used to be linked to the Lipstick Index. The uptick in small-luxury purchases has, for decades been a recession indicator – ostensibly because when finances feel uncertain, consumers tend to avoid big purchases and turn to smaller indulgences for an emotional boost. That’s no longer true. Small is now a category unto itself.
On top beauty sites, you can filter products by mini size (not Travel Size as they were once called). Korean and Japanese brands deliberately market “ampoule” sizes for single-dose products. Platforms such as Smytten sell only sample sizes. Gemz, a mass-market brand that hasn’t launched in India yet, is aimed directly at GenZ (as the name suggests). It sells bath products in single-use packs. Hang them on the shower rod, open one, add water, lather, rinse, repeat.
Retail and luxury analyst Devangshu Dutta notes that minis are just low-risk experiments in luxury. It “encourages consumers to try premium categories they might otherwise postpone”. Think about it: A full-size Maison Francis Kurkdjian perfume may cost more than a month of Uber rides, but its mini discovery set under ₹5,000 feels like reasonable adulting. A Jo Malone candle is basically an EMI for your nose — but the 35g version? Suddenly doable.
“Across beauty, fragrance, personal care and gourmet foods, minis help brands acquire new customers faster,” Dutta adds. “They rotate better on shelves, get tried more often, and build quicker loyalty.”
I feel so used
We don’t buy minis only because they’re practical. We buy them because they hit our emotional pressure points. Clinical psychologist Dr Prerna Kohli says that when life feels overwhelming, “a small treat feels manageable.” A tiny lipstick becomes a quick hit of “at least this feels good,” even when nothing else is going right.
“There’s also a cultural twist,” Kohli adds. Indians grow up on the idea of delayed pleasure — work first, reward later. Tiny luxuries flip that script. They’re permission to feel good now. “Choosing something beautiful reminds you that you still matter, without waiting for a milestone.” Women, particularly working women and caregivers, hesitate to invest in themselves. But a tiny serum? That feels “allowed.” Less money, less guilt, and far fewer explanations.
Tiny treats thrive in the kitchen, as young professionals find them easier to experiment with, than brimming jars of an unfamiliar flavour. Food creator Natasha Gandhi (@NatashaaGandhi) says that tasting sets, mini variety packs and weekend-use portions have been doing well in the gourmet and artisanal category as diners seek restaurant-style flavours at home, but don’t want to cook the same thing over and over. In smaller kitchens and cluttered pantries, they also feel practical. They sit “at the sweet spot of ambition, convenience and low commitment.”
Too tiny to thrill
Not all minis deliver value. A 7ml sunscreen sachet isn’t enough for a user to determine if it truly suits their skin. A one-meal condiment delivers flavour, not familiarity. Single-use homecare creates packaging waste, adds to clutter, and cost-per-use can quietly climb. Luxury shampoo and conditioner minis are largely “overrated,” says Bhamra — often more indulgent illusion than practical trial.
The real red flag appears when the buying shifts from enjoyment to emotional avoidance. “It becomes unhealthy when shopping is used to numb uncomfortable emotions,” cautions Kohli. The usual symptoms apply: Shopping in secret, adding to cart the same time every day, week or month – indicating shopping during cyclical low periods, overjustification for a purchase. “Enjoyment is fine. Distraction always circles back.”
Perhaps in an age of overwhelm, the new luxury isn’t about owning more, but about feeling steadier. “Sometimes people simply enjoy beautiful things in small forms,” says Kohli. “We’re allowed to like something just because it makes us smile.”
