admin
November 3, 2026
Pritha Pahari, The Core
3 November 2026
India’s packaged food and soap makers are running out of easy choices. Input costs have continued to rise since late February, when the Middle East conflict began disrupting supply chains and pushing up crude-linked costs.
A visible price hike, however, risks sending shoppers to a rival. To offset this, companies have reduced package sizes. However, scope for how much these packs can be reduced is limited, especially for products already sold at low price points. Take the example of a Rs 10 pack of Parle-G biscuits.
At this price, there is little room to reduce the quantity further without risking consumer dissatisfaction. Cutting the pack size could make the product less attractive, while increasing the price may discourage price-sensitive buyers.
India’s FMCG giants have squeezed pack sizes about as far as they can go. With input costs still climbing and shoppers watching every rupee, the choice between eating the cost and raising prices is coming, likely right after Diwali.
The Hikes Are In
Britannia, Hindustan Unilever (HUL), Dabur and Godrej Consumer had already raised prices by around 2-5% in the June quarter, and were weighing more for the September quarter. FMCG companies have continued to raise prices to offset higher input costs.
FMCG companies have continued to raise prices to offset higher input costs.
Tata Consumer Products increased tea prices by 8-10% between the June and September quarters, while it raised the price of its Rs 30 salt pack to Rs 32 in May and again to Rs 34 in October.
Hindustan Unilever also took price increases of around 7.5% during the September quarter, according to media reports.
Godrej Consumer Products said it would continue calibrated price increases, particularly in soaps and liquid detergents, to manage cost pressures.
Dabur has also confirmed taking pricing actions in its October business update, while Britannia had indicated a further 1.5-2% increase, largely through smaller packs. However, the latter two companies’ September-quarter results were still awaited.
Experts said that lower-income households face greater pressure because everyday essentials take up a larger share of their budgets. Affordable products such as biscuits, noodles, soaps, detergents and cooking oils are particularly sensitive to price changes.
According to experts, some manufacturers are weighing selective price increases after Diwali, possibly from December.
Shoppers haven’t walked away yet
So far, demand is holding up. Nestlé India’s sales rose 20.5 per cent to Rs 6,782 crore in the September quarter, with double-digit volume growth.
At HUL, June-quarter underlying sales growth of 10 per cent came equally from volume and price.
The market is still nervous.
Nestlé India shares closed 7.7% lower on results day after management flagged rising input costs, especially packaging, edible oils and farm commodities.
Business Standard quoted chairman Manish Tiwary as saying, “Rising inflation, particularly food inflation, is a reality.”
India’s FMCG volume growth remains mixed, although several companies continue to report resilient demand. Tata Consumer Products’ India branded volume growth eased from 16% in Q4 FY26 to 13% in Q1 FY27 and 11% in Q2 FY27.
Marico reported that India volume growth reached near double digits in Q2 FY27, following 11% in Q1.
Dabur India recorded 5% underlying volume growth in Q1 FY27, while its October update indicated double-digit revenue growth for Q2 but did not disclose a confirmed volume figure.
Overall, demand remains resilient, but revenue growth should not be confused with volume growth, particularly as companies raise prices to offset higher input costs.
Why Smaller Packs?
Satish Meena, founder of research firm Datum Intelligence, said that companies try to absorb costs first. “They can do it for one quarter, they can do it for two quarters, but at a certain point they have to pass it on to the customer,” he said. He expects much of that to happen after the festive season.
Discounts are not an option either, since margins are thin. That leaves pack sizes. “Instead of 150 grams, we are doing 120 grams, keeping the price the same,” Meena said, describing the move.
A visible price rise carries a risk of its own.
“Your positioning in the shop will change, and customers will also perceive you as an expensive product and look for other brands,” he said. Once a rival takes the shelf space, it is hard to win it back.
Devangshu Dutta, founder of research firm Third Eyesight, says price points are hard to move. “Price points are often anchored either in the consumer’s mind or by competitive benchmark pricing, making them difficult to change,” he said.
He also said the practice now carries a reputation risk. “The shrinkflation phenomenon isn’t new, but social media has given it viral visibility, which can potentially damage brand reputation.”
Pricing Pecking Order
Meena said companies will follow a set order. First they improve buying and supply chains, then trim ad spending. Next they raise prices on premium products, where buyers are more willing to pay. Raising prices across all products comes last, so they don’t lose share.
Dutta says companies are “caught in a vice” because input costs are rising while core shoppers are cautious about spending. Companies have “no option but to cut brand-level advertising and also review overheads deeply.”
Indian FMCG companies are facing rising input costs across several product categories.
In October 2026, plastic packaging costs were reported to have increased by 30–40%, putting pressure on snack makers and household-product manufacturers.
Palm oil prices rose 21% year-on-year in September, while sunflower oil increased 14%, soybean oil 9% and mustard oil 8%.
Sugar prices climbed 18% year-on-year, adding pressure on confectionery and packaged-food producers.
Tea prices rose 10% over the same period. Coffee and cocoa also recorded increases, with Arabica coffee up 19% quarter-on-quarter and cocoa rising 48%. These increases affect biscuits, noodles, chocolates, soaps, shampoos and detergents differently.
Now What?
The next test is HUL’s September-quarter results, due after its board meets on 28 October. Meena does not expect much to change in the next one to two quarters.
He says the pressure is not seasonal. “It’s because of the war happening in the Middle East… it’s a much longer issue for them,” and he points to RBI data showing some impact on demand.
Input-cost pressures could persist into early 2027.
S&P Global’s September outlook projected elevated manufacturing costs through 2027, while October data showed plastic packaging costs 30–40% higher and key polymer prices more than 50% above pre-conflict levels.
Although prices may ease if supply routes improve, these figures suggest FMCG companies could face continued cost pressure over the next two quarters.
Dutta said only a few brands will come through easily. “Few brands or products are able to build longer-term loyalty consistently and whose value to the consumer is stickier than the resistance to price movement.”
For everyone else, the room to raise prices or shrink packs is running out.
(Published in The Core)
admin
May 25, 2026
Vaeshnavi Kasthuril, MINT
Bengaluru, 25 May 2026
Value fashion retailers across the country are likely to face margin pressure in the upcoming quarters as rising crude oil prices are driving up the cost of polyester and other fabrics. Executives at V-Mart Retail Ltd, Vishal Mega Mart Ltd, and Kewal Kiran Clothing Ltd (KKCL) said crude oil-linked inflation has begun to push up yarn and sourcing costs across apparel and general merchandise categories, with the full impact expected to play out over the next few months.
Value fashion retailers face a double whammy: their heavy reliance on polyester and synthetic blends exposes them to crude-linked inflation, while their price-sensitive customer base leaves little room to pass on rising costs without hurting demand.
Apparel contributes about 22.8% of the overall revenue of the country’s largest retailer, DMart, in FY26. Rising polyester and fabric prices could also weigh on this share, which has been declining since FY20.
“We see almost 60% to 70% consumption of polyester yarn or poly-based product lines, which have or will get impacted,” said Lalit Agarwal during the company’s March-quarter earnings call. Agarwal said that yarn prices had already risen sharply in recent weeks. “There is a rise of almost 10% to 15% in the yarn prices, which effectively converts to almost 5% to 7% in the apparel prices,” he said.
“Cost increases are at multiple points. One, of course, is raw material, which is not only fabric, but also polyester buttons, thread, packaging, all of that,” Devangshu Dutta, founder of Third Eyesight, a consulting firm, said. “Because with value, you cannot really pass on the price hikes so readily to the consumer.”
Dutta said that lower- and middle-income consumers were already under financial stress from broader inflationary pressures, “so, they will not be able to absorb price hikes as easily as well.”
Ebitda margins in Q4FY26 are 10.9% for V-Mart Retail, 13.6% for Vishal Mega Mart and 19.1% for Kewal Kiran Clothing.
Double whammy for value segment
Gunender Kapur, CEO of Vishal Mega Mart, during the company’s March-quarter earnings call, said the inflationary impact had started becoming visible towards the end of April and would likely intensify in the coming months.
Despite rising input costs, retailers said they are avoiding broad-based price hikes on entry-level products amid fragile demand conditions in the value segment.
Entry-level products for these retailers range from ₹199 to ₹399, with some going up to ₹1,500.
“We would never tinker with the opening price points and the lower price points in these difficult times, because those are the customers who are the most vulnerable in inflationary situations,” Kapur said.
Hemant Jain, CEO of KKCL, said the company was willing to absorb part of the pressure on profitability to protect revenues and market share.
Jain also said the company had not yet implemented price hikes despite the inflationary environment.
To cushion the impact, companies said they are increasingly relying on cost optimisation, fabric innovation, premium fashion products and deeper expansion into smaller towns to sustain growth.
V-Mart said it was attempting to offset part of the inflation through alternative fabric usage, sourcing efficiencies and tighter inventory planning.
The retailer has also blocked orders in advance and is utilising existing yarn and fabric inventories available with vendors to soften the immediate impact of rising prices.
Vishal Mega Mart’s Kapur said it has revived cost-saving measures from the post-Ukraine cotton inflation cycle, including replacing cartons with gunny bags, removing polybags from some apparel categories, and shipping footwear without outer cartons.
The retailer has also increased the use of computer-aided design systems to reduce fabric waste during cutting.
Premium products, private labels offer buffer
These value retailers are also increasingly depending on premium and higher-fashion assortments, where consumers are relatively less price sensitive, to absorb selective price increases while keeping entry-level products affordable.
Kapur said Vishal Mega Mart’s large private-label portfolio, which contributes over 74% of its revenue, gives it greater flexibility to manage pricing pressure while maintaining discounts against national brands.
KKCL on the other hand, said it would absorb part of the inflationary impact rather than immediately pass on higher costs to consumers.
These retailers are also increasingly leaning on expansion into smaller towns and deeper markets to drive incremental growth as discretionary spending in larger urban centres remains uneven.
Value fashion retailers have underperformed the broader market amid growing concerns over rising input costs and margin pressure. Shares of V-Mart Retail, V2 Retail Ltd, Vishal Mega Mart and Kewal Kiran Clothing have fallen between 4% and 11% on a year-to-date basis, while the benchmark BSE rose 6.1% during the same period.
(Published in MINT)
admin
May 15, 2026
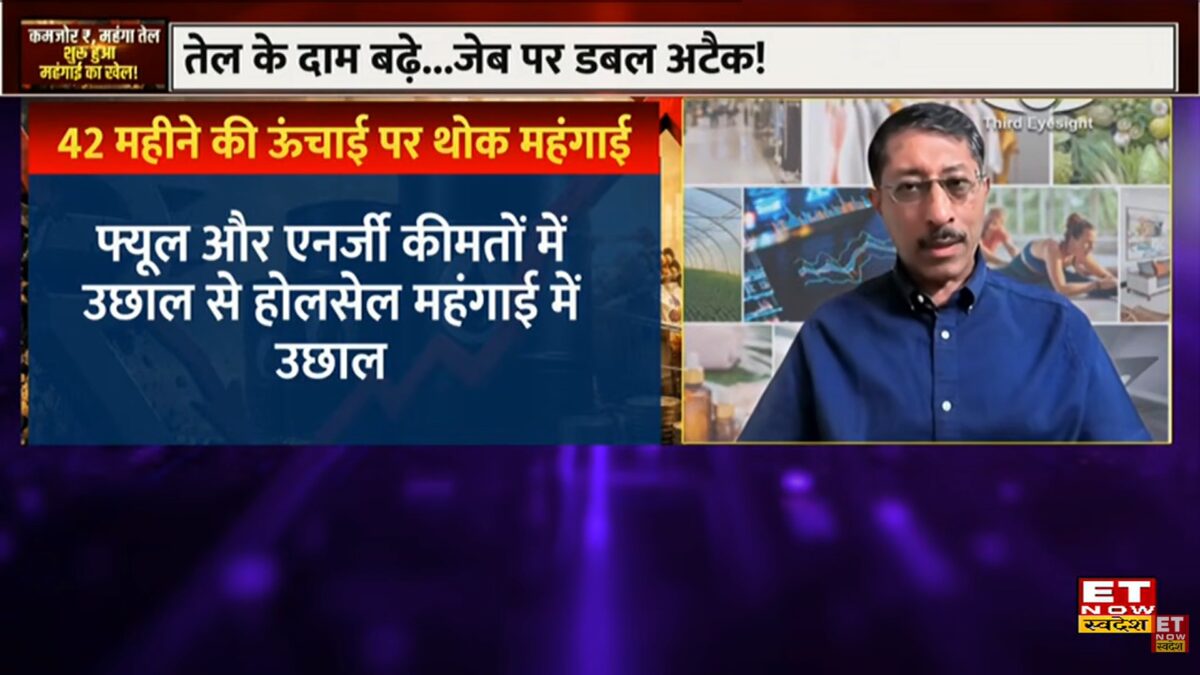
The ET Now Swadesh panel discussion focussed on the dual challenge facing the Indian economy: a weakening rupee and rising crude oil prices, which together are driving “imported inflation” and straining household budgets. Devangshu Dutta (Founder, Third Eyesight) put forth the following key points during the discussion (the video link is under the text summary below):
1. Dual Impact on Industry and Consumers:
2. Vulnerability of Small Businesses (SMEs):
3. Income vs. Expenditure Strain:
4. Ripple Effect of Crude Oil Beyond Logistics:
5. Shifts in Consumer Spending Patterns & “Shrinkflation”:
The panel noted that while the Reserve Bank of India (RBI) has adequate foreign exchange reserves to defend the rupee temporarily, the definitive solution relies heavily on the cooling down of global geopolitical tensions (such as the Middle East conflict affecting the Strait of Hormuz). Until then, Indian consumers will need careful financial planning and smart spending adjustments to navigate this inflationary phase. [Video below.]
admin
December 3, 2025
Pooja Yadav, Exchange4Media
3 December 2025
Over the last few months, India’s e‑commerce and quick‑commerce ecosystem has undergone a wave of structural regulatory and tax reforms. Be it the Goods and Services Tax Council (GST Council) formally bringing “local delivery services” under the tax net with an 18% levy, or the newly implemented labour and social-security reforms expanding obligations for gig workers on aggregator platforms like Swiggy and Zomato, the cost and compliance landscape for delivery and fulfilment is shifting significantly.
The latest GST clarification, delivery fees, packaging charges, and logistics surcharges are now creating a ripple effect across pricing, platform margins, and seller compliance requirements.
The past few months have already shown concrete signals that platforms are revising their incentives, delivery promises, and fee structures. Following the GST clarification, major food‑delivery players have raised their platform fees, for instance, Zomato reportedly increased its per‑order fee from ₹10 to ₹12 (pre‑GST), while Swiggy also raised fees in select markets. Some quick‑commerce arms are also reworking free‑delivery thresholds or fee waiver conditions. Swiggy Instamart also recently updated its free‑delivery threshold to orders above ₹299, with handling and surge fees applying below that level, per reports.
Meanwhile, some platforms seem to be signalling a de‑emphasis on “ultra‑fast for every order” as universally viable; free or fast delivery now appears increasingly tied to higher order values or subscription/membership perks.
It looks like these pressures are forcing platforms to reconsider long-standing quick-commerce levers such as ultra-fast delivery, first-order free offers, zero delivery fees, and flash discounts — which have historically driven customer acquisition and retention.
While Zomato did not comment directly, it referred to the Code on Social Security, 2020 (CoSS), noting that the platform is prepared for gig-worker obligations and does not expect the rules to negatively impact long-term business sustainability.
According to Kapil Sharma of Amazon Ads, “The e‑commerce landscape will continue to evolve, but some fundamentals remain constant such as delivering value to consumers and providing advertisers with meaningful ways to engage. Our full-funnel ad solutions allow brands to focus on objectives such as new product launches, brand building, or promoting larger pack sizes, ensuring campaigns remain relevant and effective even as the ecosystem adapts to changing costs and regulations.”
e4m reached out to Swiggy, Meesho, Zepto and BigBasket for comments, but did not receive responses until the time of publishing.
Several experts told e4m that the economic model of quick commerce, built on heavily subsidised delivery and small-ticket frequent orders, is under pressure. Platforms will need to find sustainable levers to retain customers without eroding margins. The industry has started to see a strategic recalibration where speed is increasingly becoming a hygiene factor rather than a differentiator, free delivery is becoming conditional, and platforms are nudging consumers toward larger baskets, subscription models, curated bundles, and scheduled deliveries. Brands, in turn, are also shifting focus from mass discounting to premiumisation, value-led messaging, and precise cohort-based targeting.
Will Free Delivery Become Rare?
With the new social‑security obligations for gig workers under India’s labour reforms, and the added cost burden of delivery services now subject to GST, the economic logic underlying “free delivery” as a marketing lever is coming under stress. Chetan Asher, Founder and CEO of Tonic Worldwide, echoes this view, noting that quick-commerce platforms previously operated on thin contribution margins and heavily subsidised small-ticket, frequent orders. With rising delivery costs and mandatory social-security contributions, universal free delivery is becoming increasingly unsustainable.
Industry analysts point out that the new social-security mandates and GST on delivery fees have lifted per-order costs noticeably. Most quick-commerce platforms already operate at low single-digit contribution levels, making blanket “free delivery” hard to justify. It may continue, but only as a conditional incentive tied to higher basket values, subscription memberships, or flexible delivery slots, rather than as a universal subsidy.
Shradha Agarwal, Co- Founder & Global CEO, Grapes Worldwide, added from an advertising standpoint, “It’s already happened, brands like Zomato, Swiggy, Amazon and Flipkart, who know we are going to buy from them, have shifted from ‘buy now’ tactics to ‘stay with me’ strategies. Those days are gone when platforms were giving blanket discounts, now brands are the ones tightening their offers.” Citing an example she mentioned how offline pricing is ₹235, but online it is sold at ₹185, with online adding to top-line rather than bottom-line.
On promo hooks like ‘₹0 delivery’, ‘first-order free’ or ’10-minute delivery’, Agarwal said, “As labour codes, compliance costs, and social-security contributions kick in, platforms will have less room to burn cash on promos that don’t create sustainable value. Consumers care more about convenience than freebies.”
On ad spend shifts, she noted, “Offer-driven campaigns will weaken, while value-driven storytelling will rise. ATL and influencer campaigns will strengthen, and performance marketing will become more strategic. Retail media will become non-negotiable.”
From a brand perspective, Asher pointed out that quick-commerce spends are increasingly evaluated against contribution margin rather than sheer GMV growth. Discounts and zero-fee offers are losing bite as customer acquisition costs rise. First-party data, replenishment journeys, and sharper cohort-based offers are gaining importance, ensuring that incentives remain ROI-focussed rather than mass-oriented. Similarly, speed claims such as “0 delivery” or “10-minute delivery” are becoming less differentiating in top cities, where most players already deliver within 15–20 minutes. Consumers now respond better to reliable ETAs, fair fee structures, and transparent pricing than aggressive speed promises.
Adding her viewpoint, Pooja Dhamdhere, Commerce Lead at Starcom India, said, “Incentives like free delivery or first-order offers are likely to evolve rather than disappear, and platforms will explore strategies such as tiered benefits, curated bundles, or differentiated pricing for specific cohorts.”
According to serial entrepreneur Alok Chawla and Founder at Kiko Live, added that while platforms may continue absorbing delivery costs in the short term, the long-term economics will require charging for ultra-fast or low-value orders. “Once platforms pass the actual delivery costs to consumers, we expect order frequency and small-cart behaviour to change, with many users shifting to larger baskets or neighbourhood retailers offering free delivery,” he noted.
Alternative Consumer-Incentive Models
Devangshu Dutta, founder and chief executive of Third Eyesight, who is an expert in the consumer and modern retail sector, stated, “I think platforms will pass a significant portion of the new 18% GST burden on delivery to end-consumers, either through higher delivery charges or repackaged platform fees. Some of this cost may also be clawed back from restaurant partners and quick-commerce brands via revised commissions, slotting fees or mandatory participation in marketing programmes, especially in categories where the platform has stronger bargaining power. Overall, I expect higher minimum-order thresholds and a tighter margin environment for restaurants and small D2C brands that rely heavily on third-party platforms.”
Analysts highlight strategies such as minimum-order thresholds, where free or lower-fee delivery applies only above a certain cart value, nudging consumers to order larger baskets rather than frequent small-ticket items. Subscription and membership-based models are also gaining prominence, offering benefits like waived or discounted delivery, priority fulfilment, and access to exclusive promotions in exchange for a fixed fee.
Scheduled or batch delivery windows are being used to optimise logistics, reduce cost pressure on ultra-fast last-mile fulfilment, and improve operational efficiency. Meanwhile, curated bundles and value packs, including weekly or monthly combos, allow consumers to plan purchases while enhancing per-unit economics for platforms. These levers also enable brands to maintain margin integrity without over-reliance on short-term discounting.
From a marketing perspective, this shift is prompting agencies and creative-first firms to move toward value-led messaging, premiumisation, and cohort-based targeting. Dhamdhere explained, “Platforms are optimising assortments by surfacing premium SKUs, nudging higher average order values, and using search optimisation to strengthen profitability. Brands are now focusing on aspirational consumers with curated bundles, subscriptions, and value-led propositions, rather than mass discounting. Performance campaigns will continue, but clarity of value and sustainable margin-led offers are becoming key for acquisition and retention.”
2026: Will regulatory pressure force a recalibration?
As 2026 approaches, the combined impact of GST on delivery services and mandatory social-security contributions for gig workers is forcing a fundamental rethink of quick-commerce economics. With blanket discounts, zero delivery fees and ultra-fast delivery no longer viable as mass levers, platforms are shifting toward basket-building, subscriptions, curated bundles and conditional incentives. The growth thesis is evolving from “habit formation at any cost” to protecting contribution margins through reliable ETAs, transparent pricing and premium assortments rather than aggressive subsidies.
Brands are recalibrating alongside this shift. Premiumisation, value-led propositions and sharper cohort-based targeting are taking precedence over broad discounting, and campaigns are increasingly evaluated on ROI, repeat behaviour and lifetime value rather than raw GMV. Tiered memberships, scheduled deliveries and subscription-led conveniences are emerging as key retention tools, while short-form video, influencer ecosystems and retail media help articulate value in a tighter cost environment.
Chawla said platforms will have to move beyond “₹0 delivery”, “first order free” and “10-minute delivery” as core propositions because the delivery cost burn far exceeds margins on small-ticket orders. Many consumers currently place multiple micro-orders a day simply because delivery is free, but once fees come into play, behaviour will likely shift toward clubbing orders or reverting to neighbourhood retailers, who themselves are rapidly digitising through partners like Kiko Live.
In the next phase, he adds, free instant delivery will only be sustainable for larger baskets, whereas scheduled delivery may become the default for free delivery, with paid instant delivery as an optional upgrade. Subscriptions may drive loyalty, but only up to a point, since the heaviest users would consume more deliveries than the subscription fee can realistically subsidise, making it difficult for platforms to make the model profitable.
This points to a clear playbook for 2026. “Free delivery” and mass discounting are expected to fade, giving way to conditional, tier-based formats that reward higher basket values, subscriptions or specific cohorts. Brand platform partnerships will also move toward profitability rather than promotional burn, with campaigns designed to protect margins instead of fuelling discount-led spikes.
Taken together, the signs suggest that 2026 will not mark the end of convenience, but the end of convenience that is subsidised blindly. The real test now is who absorbs this new cost of convenience, platforms, brands, or consumers. And as that battle plays out, another tension is already emerging: whether small and regional advertisers can survive the rising cost of visibility in India’s digital economy.
(published in Exchange4Media)
admin
September 16, 2024

Sesa Sen, NDTV Profit
16 September 2024
As India’s economy grows and digital technologies reshape consumer behavior, the future of kirana stores—the quintessential neighbourhood grocery shops—hangs precariously in the balance.
These soap-to-staple sellers, once impervious to change, now confront an existential threat from quick commerce players like Blinkit, Instamart, Zepto, and from modern retailers such as DMart and Star Bazaar, raising a pivotal question: Can kiranas survive the pressure of change, or will they die a slow death?
The All India Consumer Products Distributors Federation, that represents four lakh packaged goods distributors and stockists, has recently raised alarms, urging Union Minister for Commerce and Industry Piyush Goyal to investigate the unchecked proliferation of quick commerce platforms and its potential ramifications for small traders.
Their concerns are not unfounded. Data suggests that the share of modern retail, including online commerce, which is currently below 10%, is set to cross 30% over the next 3-5 years. Much of this growth will come at the cost of traditional retail.
“Unless the government takes on an activist role to support the smallest of business owners, the shift toward large corporate formats is inevitable,” according to Devangshu Dutta, head of retail consultancy Third Eyesight.
Casualties Of The Boom
Madan Sachdev, a second-generation grocer operating Vandana Stores in eastern Delhi, has thrived in the recent years, adapting to the digital age by taking orders via WhatsApp and employing extra hands for home delivery.
Despite having weathered the storm of competition from giants like Amazon and BigBazaar, he now finds himself disheartened, as his monthly sales have halved to about Rs 30,000, all thanks to quick commerce.
Sachdev is worried about meeting expenses such as rent, his children’s education, and other household bills. He finds himself at a crossroads, uncertain about how to modernise his store or adopt new-age strategies in order to attract customers in an increasingly competitive market.
India’s $600 billion grocery market, a cornerstone for quick commerce, is largely dominated by more than 13 million local mom-and-pop stores.
Retailers like Sachdev are also seeing a steep decline in their profit margins from FMCG companies, which now hover around 10-12%, down from the 18-20% margins seen before the Covid-19 pandemic. The consumer goods companies are instead offering higher margins to quick commerce platforms so that they can afford the price tags.
Quick deliveries account for $5 billion, or 45%, of the country’s $11 billion online grocery market, according to Goldman Sachs. It is projected to capture 70% of the online grocery market, forecasted to grow to $60 billion by 2030, as consumers increasingly prioritise convenience and speed.
Many of the mom-and-pop shops are family-run and have been in business for generations. Yet they lack the resources to modernise and compete effectively with larger chains. Modern retail businesses, including quick commerce, begin with significantly more capital, thanks to funding from corporate investors, venture capital, private equity, and public markets.
“They can scale quickly and capture market share due to a superior product-service mix, larger infrastructure, and more robust business processes,” said Dutta.
Moreover, their ability to engage in price competition poses a challenge for small retailers and distributors, making it difficult for them to compete.
“This is something that has happened worldwide, in the largest markets, and I don’t think India will be an exception,” Dutta said, adding that it would be incomplete to single out a specific format of corporate business such as quick commerce as the sole villain in this situation.
“India is a tough, friction-laden environment at any given point in time, including government processes which don’t make it any easier,” he said.
Peer Pressure
Data from research firm Kantar shows that general trade, which comprises kirana and paan-beedi shops, have grown 4.2% on a 12-month basis in June, while quick commerce grew 29% during the same period.
Shoppers are becoming more omnichannel, rather than gravitating towards one particular channel, said Manoj Menon, director- commercial, Kantar Worldpanel, South Asia. “While the growth [for quick commerce and e-commerce] might appear to have declined compared to a year ago, a point to note is that the base for these channels has significantly grown. Therefore, achieving this level of growth is still commendable.”
Consumer goods companies such as Hindustan Unilever Ltd., Dabur India Ltd., Tata Consumer Products Ltd., etc., have acknowledged the salience of quick commerce to their packaged food, personal and homecare products. The platform currently comprises roughly 40% of their digital sales.
“We are working all the major players in the quick commerce space and devising product mix and portfolio. This is a very high growth channel for us,” according to Mohit Malhotra, chief executive officer, Dabur India.
Elara Capital analysts have pointed out that the share of quick commerce is expected to rise to60% in the near future with e-commerce and modern trade turning costlier for FMCG brands than quick commerce. “The larger brands tend to make better margins on quick-commerce platforms versus e-commerce due to lower discounts on the former,” it said in a report.
However, it is too premature to draw a parallel between kirana and quick commerce in terms of competition, given the significant size difference.
The average spend per consumer on FMCG in kirana stores stands at Rs. 21,285 annually while the same is Rs. 4,886 for quick commerce, according to Menon.
Rural Vs Urban Divide
Quick commerce is still an urban phenomenon. In contrast, in rural settings, where internet penetration is still catching up and access to large retail chains is limited, kirana stores continue to thrive.
According to Naveen Malpani, partner, Grant Thornton Bharat, while the growth of quick commerce is undeniable, this channel is not poised to replace traditional retail, which still has a wider reach in the country. “It will complement older models, filling a niche for immediate, smaller purchases. Also, a 10-20-minute delivery may not have a strong market pull in rural markets where distance and time are not much of a concern.”
Yet many others believe, even in these areas, the challenge is palpable.
The small businesses are beginning to feel the sting of same slow decline that once befell the ubiquitous telephone booths in the era of mobile phone, according to Sameer Gandotra, chief executive officer of Frendy, a start-up that is building ‘mini DMart’ in small towns where giants like Reliance and Tatas have yet to establish their presence.
As rural customers slowly start to embrace digital shopping and seek more variety, kirana stores must adapt or risk becoming obsolete, he said.
Besides, the popularity of quick commerce is set to challenge the dominance of incumbent e-commerce platforms, especially in categories such as beauty and personal care, packaged foods and apparel.
“Quick commerce is primarily operational in metros and tier 1 markets, which is impacting the sales of traditional companies in these areas. However, if quick-commerce players were to extend their operations to tier 2 and tier 3, it would even challenge companies such as DMart and Nykaa, and would pare sales and profitability,” noted analysts at Elara Securities.
Frendy’s Gandotra believes the journey for kirana stores is not a lost cause, but it requires strategic interventions. Many kirana store owners struggle to integrate point-of-sale systems, inventory management software, or even digital payment solutions. These stores need to embrace technology.
Another aspect is the need for policy support. Regulations to ensure fair competition can prevent monopolisation by large retailers. Additionally, subsidies, tax benefits, and grants for infrastructure improvements can help small businesses adapt to changing market dynamics. With renewed support, kirana stores can continue to be the backbone of Indian retail.
Nonetheless, there will be some who’ll be left behind during this shift. Analysts at Elara Capital warn that the swift rise of quick-commerce platforms, combined with aggressive discounting, could wipe off 25-30% of traditional grocery stores.
(Published on NDTV Profit)
