
admin
January 15, 2026

Sagar Malviya, ET Bureau
Mumbai, 15 January 2026
It’s mostly a tale of two halves for top western fashion labels in India after the runaway sales and retail expansion in the years soon after the pandemic.
While Marks & Spencer, Benetton, and Adidas are battling waning demand, Uniqlo and Nike are gaining fresh ground, reflecting wider choices and increasingly discerning buyers in one of the world’s fastest-growing consumer economies.
Spanish brand Zara is facing stagnant growth while it tapered off at Apparel Group, which sells Aldo, and Charles & Keith brands in India. Experts termed the divergent sales performance as a potential structural shift instead of demand slowdown in India’s fashion and lifestyle market.
Devangshu Dutta, founder of retail consulting firm Third Eyesight, said consumers have clearly shifted towards function, even as trend-led brands continue to exist though they tend to be comparatively smaller. Some brands are also finding it harder to set or even follow trends the way they once did.
“This is especially true for Gen Z, which stays closely tuned to global trends and acts as the primary driver of fashion adoption,” said Dutta. “While older consumers may have greater spending power in absolute terms, it is younger shoppers who shape trends and influence product sales.”
Growth slowed across most leading retailers and fast-fashion brands in the country in FY24 as high inflation and stagnant incomes crimped discretionary spending.
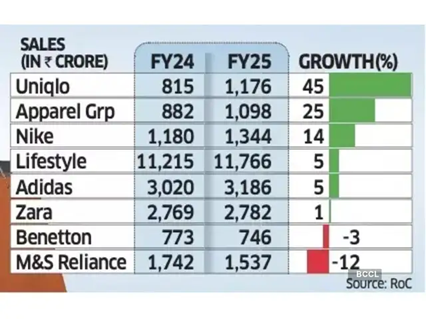
While the trend remained the same for many even in FY25, select brands staged a strong rebound. For instance, Nike India’s sales rose 14% in FY25, up from a 4% increase in the previous year, while Uniqlo accelerated growth to 45%, from 31% in FY24.
Revival after Festive Season
Even Lifestyle, India’s biggest department store chain, grew 5% last fiscal, rebounding from a 4% decline in FY24.
Uniqlo said it continues to see steady momentum in India, supported by strong customer response, retail expansion, rising brand awareness, and a strong ecommerce uplift. “India is now among Uniqlo’s fastest-growing markets in Asia and plays a meaningful role in the region’s overall business,” Kenji Inoue, chief financial officer and chief operating officer, Uniqlo India told ET. “The country’s young demographic, growing focus on quality, and increasing appreciation for functional everyday clothing have all contributed to this progress.”
According to the Retailers Association of India (RAI), sales growth in organised retail segments such as apparel, footwear, beauty and quick service restaurants (QSR) saw single-digit sales growth last fiscal year but the market has recovered after the festive season with double-digit sales performance.
“Demand has improved, but it isn’t broad-based,” said Kumar Rajagopalan, chief executive at RAI which represents organised retailers. “With more fashion options available, Indian consumers are becoming more selective, and growth is coming to brands that offer a strong value proposition and not the cheapest products, but those where prices are justified by innovation, design and quality.”
In FY25, Apparel Group recorded a 25% sales growth, slowing from a 37% increase a year ago. Inditex Trent, which sells Zara in India, saw flat sales compared with an 8% growth in FY24.
Adidas too saw its revenue growth rate slowing to 5% from 20% in the previous fiscal. Sales of M&S and Benetton fell 12% and 3% each, respectively.
Being the world’s most populous nation, India is an attractive market for apparel brands, especially with youngsters increasingly embracing western-style clothing. However, most international and premium brands have been competing for a relatively narrow slice of the sales pie in large urban centres.
(Published in Economic Times)
admin
December 7, 2025
Gargi Sarkar, Inc42
7 December 2025
The past year has been nothing short of monumental for LensKart — from reporting another operationally profitable quarter in Q2 FY26 to making the public markets leap in November, and crossing a market capitalisation of INR 70,000 Cr despite a muted stock market debut.
A clear shift this year has been Lenskart’s effort to move beyond the image of a ‘basic D2C eyewear’ brand selling prescription glasses and sunglasses. The company is now working to reposition itself as a new-age tech brand.
Further, Lenskart is rethinking where and how its products are manufactured. Currently, around 20–25% of its frames are reportedly manufactured in India. The company is ramping up its domestic production. As a new manufacturing facility in Telangana is a work in progress, Lenskart intends to gradually shift most of its manufacturing operations from China to India.
In many ways, 2025 has been about scaling up for Lenskart, and as it embarks on a fresh journey as a publicly listed company, let’s take stock of the company in 2025 and where it might be headed in 2026.
Lenskart’s Smart Eyewear Bet
Lenskart began its smart eyewear journey last year with the launch of Phonic, its audio glasses. It later deepened its push into the segment by announcing a strategic investment in Ajna Lens, a Mumbai-based deeptech company that develops AI-powered XR glasses. Back then, Peyush Bansal described the move as the “next chapter” in Lenskart’s smart glasses journey.
Cut to December 2025, the company is all set to launch its AI camera smartglasses, B by Lenskart, by the end of this month.
What makes B by Lenskart noteworthy is that it isn’t being marketed as just another pair of smart glasses. The new eyewear features an integrated Sony camera that enables hands-free photo and video capture. The glasses come with a built-in AI assistant powered by Gemini 2.5 Live. They are designed to offer natural, conversational interactions and pack in a range of advanced features — from hands-free UPI payments and live translation to wellness insights and more.
What makes the move even more significant is Lenskart’s decision to open B by Lenskart to India’s developer ecosystem. By making its AI and camera technology accessible to consumer apps and independent developers, the company is enabling integrations across categories such as food delivery, entertainment, and fitness.
“By opening its AI smartglasses to third-party developers, Lenskart is moving from a one-time product-sale model to a platform ecosystem model. In the long run, this could unlock recurring revenue streams and higher margins,” said a product developer.
Besides, the company is aligning itself with a younger customer cohort, aided by affordability, style, and technology.
“That’s what seems to define their current strategy. Over time, they’ve also brought in elements of innovation like virtual try-ons, and any product, feature, or service that brings novelty and appeals to younger customers has become part of their brand approach,” said Devangshu Dutta, the founder of Third Eyesight.
Next, the timing couldn’t be better for Lenskart to place its bet on smart glasses. An IDC report reveals that despite a slowdown in smartwatch and earwear segments in the second half of 2025, smart glass shipments shot off more than 1,000% over the last year.

However, it’s not going to be smooth sailing from here.
At its core, Lenskart is still a consumer-facing company, and it needs new products to keep its revenue growing. But the competition is already heating up. Jio unveiled its own AI-powered smart glasses, Jio Frames, at Reliance Industries’ 48th annual general meeting. And of course, Meta continues to lead the global smart glasses market.
At this point, smart eyewear is a niche category, which comes with a hefty price tag.
“Unless cost drops dramatically, mass adoption is still a distant dream. As of now, the product will only attract early adopters and tech enthusiasts, rather than the mainstream consumer,” Dutta adds.
Lenskart’s Make In India Push
Lenskart is not only widening its product range but also ramping up its manufacturing. The company currently operates centralised manufacturing facilities in India (Bhiwadi in Rajasthan and Gurugram in Haryana), Singapore, and the UAE. It also has manufacturing operations in China.

Back home, Lenskart has also signed a non-binding MoU with the Government of Telangana for setting up a greenfield manufacturing facility for optical glasses. The proposed investment stands at INR 1,500 Cr and will be supported by certain incentives and assistance from the state government.
The new production facility is expected to strengthen Lenskart’s domestic manufacturing capabilities while reducing its exposure to foreign exchange fluctuations and import-related volatility.
However, the expansion comes with its own set of challenges. While the new manufacturing plant in Telangana is expected to strengthen Lenskart’s vertical integration, it will come with a hefty cost burden.
Profitability Still A Troubling Question
The cost structure is becoming increasingly important for Lenskart. Despite its headline-grabbing profitability, the company is still operating on fairly thin margins.

Lenskart reported a net profit of INR 297 Cr in FY25, a notable turnaround from a loss of INR 10 Cr in FY24. However, market analysts caution that the business’ core operations were unprofitable. It was largely “other income” or investment income that drove the FY25 bottom line.
“Though Lenskart has increased its revenue from INR 3,789 Cr in FY23 to INR 6,651 Cr in FY25, the company’s profitability has largely improved due to a rise in other income. While it reported a PAT of INR 297 Cr in FY25, a closer look shows that the profit was driven significantly by an increase in other income, which jumped to INR 356 Cr in FY25,” SimranJeet Singh Bhatia, senior research analyst for equity at Almondz Group.
The point of concern here is that Lenskart turned operationally profitable only after its market debut. Bhatia believes that at least three to four quarters of consecutive profitability will be needed to prove the company’s underlying strength.
However, making matters worse are the company’s climbing expenses, which stood at INR 1,980.3 Cr in Q2 FY26, up 18.5% YoY.
What Lies Ahead?
The year was equally sour for the eyewear major. While its IPO generated significant buzz and saw strong subscription levels, its market debut turned out to be a muted affair.
At the upper end of its INR 382 to INR 402 IPO price band, the public issue implied a price-to-earnings (P/E) multiple of roughly 235–238 times its FY25 profits, placing it among the most expensive consumer tech listings in India.
On its first day of trading, Lenskart Solutions Ltd. was listed on the NSE at INR 395 per share, a discount of 1.74% to the issue price of INR 402. The stock, however, fell close to 9% shortly thereafter. On the BSE, it debuted at INR 390, marking a discount of nearly 3%.
After the IPO, Bhatia adds, the biggest concern surrounding Lenskart is the store-level unit economics, particularly because a significant share of the IPO proceeds is being directed toward expanding its company-owned, company-operated store network.
Entering the new year as a public company, Lenskart will have to prove that its scale-up plans are justified and that it has greater control over its balance sheet. 2026 will be a critical juncture for the company, as the next three to four quarters will be closely watched for signs of sustainable growth, improved margins, and stronger operational discipline.
[Edited by Shishir Parasher]
(Published in Inc42)
admin
December 3, 2025
Pooja Yadav, Exchange4Media
3 December 2025
Over the last few months, India’s e‑commerce and quick‑commerce ecosystem has undergone a wave of structural regulatory and tax reforms. Be it the Goods and Services Tax Council (GST Council) formally bringing “local delivery services” under the tax net with an 18% levy, or the newly implemented labour and social-security reforms expanding obligations for gig workers on aggregator platforms like Swiggy and Zomato, the cost and compliance landscape for delivery and fulfilment is shifting significantly.
The latest GST clarification, delivery fees, packaging charges, and logistics surcharges are now creating a ripple effect across pricing, platform margins, and seller compliance requirements.
The past few months have already shown concrete signals that platforms are revising their incentives, delivery promises, and fee structures. Following the GST clarification, major food‑delivery players have raised their platform fees, for instance, Zomato reportedly increased its per‑order fee from ₹10 to ₹12 (pre‑GST), while Swiggy also raised fees in select markets. Some quick‑commerce arms are also reworking free‑delivery thresholds or fee waiver conditions. Swiggy Instamart also recently updated its free‑delivery threshold to orders above ₹299, with handling and surge fees applying below that level, per reports.
Meanwhile, some platforms seem to be signalling a de‑emphasis on “ultra‑fast for every order” as universally viable; free or fast delivery now appears increasingly tied to higher order values or subscription/membership perks.
It looks like these pressures are forcing platforms to reconsider long-standing quick-commerce levers such as ultra-fast delivery, first-order free offers, zero delivery fees, and flash discounts — which have historically driven customer acquisition and retention.
While Zomato did not comment directly, it referred to the Code on Social Security, 2020 (CoSS), noting that the platform is prepared for gig-worker obligations and does not expect the rules to negatively impact long-term business sustainability.
According to Kapil Sharma of Amazon Ads, “The e‑commerce landscape will continue to evolve, but some fundamentals remain constant such as delivering value to consumers and providing advertisers with meaningful ways to engage. Our full-funnel ad solutions allow brands to focus on objectives such as new product launches, brand building, or promoting larger pack sizes, ensuring campaigns remain relevant and effective even as the ecosystem adapts to changing costs and regulations.”
e4m reached out to Swiggy, Meesho, Zepto and BigBasket for comments, but did not receive responses until the time of publishing.
Several experts told e4m that the economic model of quick commerce, built on heavily subsidised delivery and small-ticket frequent orders, is under pressure. Platforms will need to find sustainable levers to retain customers without eroding margins. The industry has started to see a strategic recalibration where speed is increasingly becoming a hygiene factor rather than a differentiator, free delivery is becoming conditional, and platforms are nudging consumers toward larger baskets, subscription models, curated bundles, and scheduled deliveries. Brands, in turn, are also shifting focus from mass discounting to premiumisation, value-led messaging, and precise cohort-based targeting.
Will Free Delivery Become Rare?
With the new social‑security obligations for gig workers under India’s labour reforms, and the added cost burden of delivery services now subject to GST, the economic logic underlying “free delivery” as a marketing lever is coming under stress. Chetan Asher, Founder and CEO of Tonic Worldwide, echoes this view, noting that quick-commerce platforms previously operated on thin contribution margins and heavily subsidised small-ticket, frequent orders. With rising delivery costs and mandatory social-security contributions, universal free delivery is becoming increasingly unsustainable.
Industry analysts point out that the new social-security mandates and GST on delivery fees have lifted per-order costs noticeably. Most quick-commerce platforms already operate at low single-digit contribution levels, making blanket “free delivery” hard to justify. It may continue, but only as a conditional incentive tied to higher basket values, subscription memberships, or flexible delivery slots, rather than as a universal subsidy.
Shradha Agarwal, Co- Founder & Global CEO, Grapes Worldwide, added from an advertising standpoint, “It’s already happened, brands like Zomato, Swiggy, Amazon and Flipkart, who know we are going to buy from them, have shifted from ‘buy now’ tactics to ‘stay with me’ strategies. Those days are gone when platforms were giving blanket discounts, now brands are the ones tightening their offers.” Citing an example she mentioned how offline pricing is ₹235, but online it is sold at ₹185, with online adding to top-line rather than bottom-line.
On promo hooks like ‘₹0 delivery’, ‘first-order free’ or ’10-minute delivery’, Agarwal said, “As labour codes, compliance costs, and social-security contributions kick in, platforms will have less room to burn cash on promos that don’t create sustainable value. Consumers care more about convenience than freebies.”
On ad spend shifts, she noted, “Offer-driven campaigns will weaken, while value-driven storytelling will rise. ATL and influencer campaigns will strengthen, and performance marketing will become more strategic. Retail media will become non-negotiable.”
From a brand perspective, Asher pointed out that quick-commerce spends are increasingly evaluated against contribution margin rather than sheer GMV growth. Discounts and zero-fee offers are losing bite as customer acquisition costs rise. First-party data, replenishment journeys, and sharper cohort-based offers are gaining importance, ensuring that incentives remain ROI-focussed rather than mass-oriented. Similarly, speed claims such as “0 delivery” or “10-minute delivery” are becoming less differentiating in top cities, where most players already deliver within 15–20 minutes. Consumers now respond better to reliable ETAs, fair fee structures, and transparent pricing than aggressive speed promises.
Adding her viewpoint, Pooja Dhamdhere, Commerce Lead at Starcom India, said, “Incentives like free delivery or first-order offers are likely to evolve rather than disappear, and platforms will explore strategies such as tiered benefits, curated bundles, or differentiated pricing for specific cohorts.”
According to serial entrepreneur Alok Chawla and Founder at Kiko Live, added that while platforms may continue absorbing delivery costs in the short term, the long-term economics will require charging for ultra-fast or low-value orders. “Once platforms pass the actual delivery costs to consumers, we expect order frequency and small-cart behaviour to change, with many users shifting to larger baskets or neighbourhood retailers offering free delivery,” he noted.
Alternative Consumer-Incentive Models
Devangshu Dutta, founder and chief executive of Third Eyesight, who is an expert in the consumer and modern retail sector, stated, “I think platforms will pass a significant portion of the new 18% GST burden on delivery to end-consumers, either through higher delivery charges or repackaged platform fees. Some of this cost may also be clawed back from restaurant partners and quick-commerce brands via revised commissions, slotting fees or mandatory participation in marketing programmes, especially in categories where the platform has stronger bargaining power. Overall, I expect higher minimum-order thresholds and a tighter margin environment for restaurants and small D2C brands that rely heavily on third-party platforms.”
Analysts highlight strategies such as minimum-order thresholds, where free or lower-fee delivery applies only above a certain cart value, nudging consumers to order larger baskets rather than frequent small-ticket items. Subscription and membership-based models are also gaining prominence, offering benefits like waived or discounted delivery, priority fulfilment, and access to exclusive promotions in exchange for a fixed fee.
Scheduled or batch delivery windows are being used to optimise logistics, reduce cost pressure on ultra-fast last-mile fulfilment, and improve operational efficiency. Meanwhile, curated bundles and value packs, including weekly or monthly combos, allow consumers to plan purchases while enhancing per-unit economics for platforms. These levers also enable brands to maintain margin integrity without over-reliance on short-term discounting.
From a marketing perspective, this shift is prompting agencies and creative-first firms to move toward value-led messaging, premiumisation, and cohort-based targeting. Dhamdhere explained, “Platforms are optimising assortments by surfacing premium SKUs, nudging higher average order values, and using search optimisation to strengthen profitability. Brands are now focusing on aspirational consumers with curated bundles, subscriptions, and value-led propositions, rather than mass discounting. Performance campaigns will continue, but clarity of value and sustainable margin-led offers are becoming key for acquisition and retention.”
2026: Will regulatory pressure force a recalibration?
As 2026 approaches, the combined impact of GST on delivery services and mandatory social-security contributions for gig workers is forcing a fundamental rethink of quick-commerce economics. With blanket discounts, zero delivery fees and ultra-fast delivery no longer viable as mass levers, platforms are shifting toward basket-building, subscriptions, curated bundles and conditional incentives. The growth thesis is evolving from “habit formation at any cost” to protecting contribution margins through reliable ETAs, transparent pricing and premium assortments rather than aggressive subsidies.
Brands are recalibrating alongside this shift. Premiumisation, value-led propositions and sharper cohort-based targeting are taking precedence over broad discounting, and campaigns are increasingly evaluated on ROI, repeat behaviour and lifetime value rather than raw GMV. Tiered memberships, scheduled deliveries and subscription-led conveniences are emerging as key retention tools, while short-form video, influencer ecosystems and retail media help articulate value in a tighter cost environment.
Chawla said platforms will have to move beyond “₹0 delivery”, “first order free” and “10-minute delivery” as core propositions because the delivery cost burn far exceeds margins on small-ticket orders. Many consumers currently place multiple micro-orders a day simply because delivery is free, but once fees come into play, behaviour will likely shift toward clubbing orders or reverting to neighbourhood retailers, who themselves are rapidly digitising through partners like Kiko Live.
In the next phase, he adds, free instant delivery will only be sustainable for larger baskets, whereas scheduled delivery may become the default for free delivery, with paid instant delivery as an optional upgrade. Subscriptions may drive loyalty, but only up to a point, since the heaviest users would consume more deliveries than the subscription fee can realistically subsidise, making it difficult for platforms to make the model profitable.
This points to a clear playbook for 2026. “Free delivery” and mass discounting are expected to fade, giving way to conditional, tier-based formats that reward higher basket values, subscriptions or specific cohorts. Brand platform partnerships will also move toward profitability rather than promotional burn, with campaigns designed to protect margins instead of fuelling discount-led spikes.
Taken together, the signs suggest that 2026 will not mark the end of convenience, but the end of convenience that is subsidised blindly. The real test now is who absorbs this new cost of convenience, platforms, brands, or consumers. And as that battle plays out, another tension is already emerging: whether small and regional advertisers can survive the rising cost of visibility in India’s digital economy.
(published in Exchange4Media)
admin
November 18, 2025

Chris Kay, Krishn Kaushik and Andrea Rodrigues in Mumbai
Nov 18 2025
Just before dawn, Kashif Sameer joins dozens of couriers zipping across Mumbai to deliver items stocked in a basement of a shopping mall run by Reliance Industries.
“I make between 20 and 30 deliveries in a day,” said the 25-year-old, who had just driven a mile across the chaotic roads of the Indian megacity to drop off groceries ordered 15 minutes earlier. “It is very popular with customers.”
The buzzing activity at the so-called dark store, a mini-warehouse operated by Reliance’s ecommerce platform JioMart, is part of a renewed push by the conglomerate’s chair and Asia’s richest man, Mukesh Ambani, to reassert his company’s position in India’s retail market.
It has added hundreds of dark stores to operate a total of nearly 20,000 physical outlets this year — almost double its pre-pandemic size — as it battles for dominance against Blinkit, Swiggy and Zepto in the country’s ballooning quick-commerce market.
“It’s a question of who runs out of money first,” said Arvind Singhal, chair of retail consultancy The Knowledge Company. “We will see some kind of a shakeout.”
Despite its large network of physical stores, Reliance has yet to corner the domestic consumer market like it did with telecoms a decade ago. It faces entrenched competition from established domestic and international rivals, as well as millions of kiranas, family-run convenience stores.
The sprawling Tata Group operates a wide range of consumer businesses, while global multinationals such as Unilever and Nestlé are important players in India’s household goods market.
Reliance Retail, the division that contains all of the conglomerate’s consumer-facing units, had shed tens of thousands of employees and closed underperforming stores following a bloated build-out during the Covid-19 pandemic and slowing middle-class spending.
But India’s most valuable company, which has a market value of more than $225bn and operates across oil refining, telecoms and entertainment, is expanding its retail reach again.
Reliance Retail’s latest results point to a rebound. In the quarter ending September, the unit reported revenue of about $10bn and profit of $390mn, up 18 and 22 per cent respectively from the previous year.
“Reliance’s scale in retail now is unmatched in India,” said Devangshu Dutta, chief executive of consumer advisory company Third Eyesight, in reference to the breadth of the conglomerate’s business. “This scale is unique in India and rare in global retail.”
Ambani’s retail ambitions are being led by his 34-year-old daughter, Isha. In August, she detailed plans for Reliance’s consumer brands subsidiary, which has a portfolio including Lotus Chocolate and the recently revived nostalgic Indian soft drink Campa Cola, to reach $11.7bn in revenue within five years.
Ultimately, the goal was to “become India’s largest FMCG company with a global presence”, said Isha Ambani during Reliance’s annual meeting.
The company told the Financial Times that it continued to “reinforce its position as India’s largest retailer, expanding its nationwide network”.

While Ambani originally indicated that he wanted to list Reliance Jio Infocomm, the telecoms unit, and Reliance Retail by 2024, people familiar with the company said the retail unit was not ready to go public. The billionaire said the Jio listing could happen in the first half of next year.
“Competitive intensity in every category in the discretionary retail side has picked up very sharply,” said Karan Taurani, executive vice-president at Elara Capital, who does not expect Reliance Retail to float for at least two years. “New competitors, new brands have come in and they are challenging the larger incumbents.”
The Ambanis, who operate as gatekeepers for foreign companies seeking access to India’s massive but challenging business landscape, have sought to cement their position through a spate of partnerships with western retail brands.
Foreign brands including West Elm, Pottery Barn and Superdry have stores in Reliance’s shopping malls in upmarket Mumbai. However, those joint ventures have largely struggled to gain traction with shoppers in India, where the per capita income remains less than $3,000.
The conglomerate’s foreign brands business housing these joint ventures lost Rs2.7bn ($30mn) in the financial year through March 2025, according to the latest available accounts. The Knowledge Company’s Singhal called Reliance’s push to bring international names to India “a vanity project”.
Reliance’s high-profile partnership with fast-fashion retailer Shein has also been underwhelming. The company returned to India this year under Reliance’s wing after being booted out in 2020 when relations between New Delhi and Beijing soured following military clashes along their disputed border.
Shein’s app has been downloaded just 11mn times, according to market intelligence firm Sensor Tower. Its discount prices are largely matched, if not undercut, by many Indian ecommerce and fashion retailers, say analysts.
Reliance is investing heavily in quick commerce, where deliveries are promised in 30 minutes or less. Bank of America estimates the market could reach $128bn by 2030.
The field is at present dominated by Blinkit, Swiggy and Zepto, which together control more than 90 per cent of the quick commerce delivery market and compete with Amazon and Walmart-owned Flipkart. None of the companies are profitable.
The Ambanis are eager to catch up. Over the past six months, Reliance has built about 600 dark stores across cities to plug gaps in its vast store network. By contrast, market leader Blinkit operates about 1,800 dark stores.
In quick commerce, “we have to be there because everybody is”, said a person close to the conglomerate. “It is a long-term strategy.”
On a call with analysts last month, Reliance Retail’s finance chief Dinesh Taluja admitted to delays in entering quick commerce. But he insisted that Reliance offered better prices, more variety and wider reach across smaller Indian cities where it is often the only formal retailer.
“The competition today is mainly in the top 10, 20 cities,” Taluja said. “We are present in almost a thousand cities. Competition will take many years to reach where we already have a head start there.”
Still, Reliance was facing an uphill battle, warned Elara’s Taurani. “JioMart is making a late entry,” he said, “it will be very tough to disrupt players here.”
(Published in Financial Times, all copyrights owned by FT)
admin
November 4, 2025
Yash Bhatia, IMPACT
4 November 2025
It started with groceries. Quick commerce started delivering milk, bread, and eggs in 10–15 minutes, which seemed revolutionary enough in 2022. Then came the iPhone 14 launch, and suddenly, quick commerce wasn’t just about convenience; it was about spectacle. Overnight, India’s app-based delivery ecosystem became the stage for a new ritual: flagship products arriving at your doorstep faster than you can say ‘checkout.’
And now? Phones aren’t the limit. You can even order motorcycles online. Yes, motorcycles. Royal Enfield has partnered with Flipkart to list its entire 350cc portfolio, which will be delivered to five cities: Bengaluru, Gurugram, Kolkata, Lucknow, and Mumbai.
The lines between e-commerce and quick commerce are becoming increasingly blurred. Flipkart’s Flipkart Minutes and Amazon’s instant delivery options are proof that speed is no longer a differentiator; it’s table stakes. And as platforms race to expand, high-ticket items are joining the frenzy, from electronics and furniture to watches, fitness equipment, and premium kitchen appliances. For platforms, these products are goldmines of margin; the challenge lies in logistics and consumer trust.
According to a report by CareEdge Advisory, India had over 270 million online shoppers in 2024, making it the second-largest e-retail user base globally, while the e-commerce market grew 23.8% in 2024 over the year-ago period, it said. The report also added that Indians ordered Rs 64,000 crore of goods from quick-commerce platforms.
From the consumer standpoint, one of the challenges for consumers to buy high-ticket items from the quick commerce platforms is to get consumer trust, which used to be the case when e-commerce started its operations. Can quick commerce move to high-ticket items? Is quick commerce looking at these items as a branding exercise, or are they looking at them as a serious revenue stream channel?
Chirag Taneja, Founder & CEO, GoKwik – an e-commerce enablement platform, says what began as a branding exercise for D2C brands has now evolved into a credible revenue stream. “In the early days, high-ticket categories on D2C platforms saw limited traction,” he explains. “Trust was still being built, customers were unsure if their orders would even reach them. There were many friction points.”
But that’s no longer the case. According to GoKwik’s network data, high-ticket purchases (above ₹2,500) are no longer outliers, they’re becoming a consistent driver of topline revenue.
Interestingly, most of these premium purchases are powered by credit instruments from no-cost EMIs to instant credit options at checkout. “This reflects a clear shift in mindset,” says Taneja. “Consumers no longer view high-value spending as a financial strain. They see it as a set of manageable, bite-sized payments that help them aspire higher, quicker. It’s not just a financial enabler, it’s a psychological unlock that makes premium consumption feel accessible and routine,” he adds.
“With strong trust in delivery reliability, smooth returns, and credible brand backing, the ecosystem has bridged the gap that once kept premium shopping offline,” says Taneja.
Devangshu Dutta, Founder of a specialist consulting firm, Third Eyesight, thinks differently and points out that high-value items still make up a small slice of quick commerce sales. “The model thrives on simplicity, a limited product range on the platform’s end, and quick, low-friction decision-making on the consumer’s,” he explains.
That said, Dutta believes quick commerce can still play a strategic role for premium brands. “For high-value products, q-comm can be an excellent lever for driving velocity, testing market response, or amplifying brand visibility. But it should be viewed as one piece of the channel mix, not the primary sales driver.”
From the platform’s perspective, however, listing high-ticket products brings its own upside. “They create excitement, boost average transaction values, and improve realised margins,” Dutta notes. “Consumers are often drawn in by novelty, exclusivity, or status appeal, especially during big launches or limited-time promotions.”
Still, he adds a note of realism: “Premium and high-ticket purchases largely remain planned decisions. Most consumers continue to prefer established offline and e-commerce channels for such buys where trust in authenticity, return policies, and after-sales services still carry greater weight than instant gratification.”
Seshu Kumar Tirumala, Chief Buying and Merchandising Officer, BigBasket, says the company doesn’t look at electronics as a high-ticket item category but rather focuses on building a complete category experience for customers. “For example, if we list an Enfield bike, we’d also want to offer spare parts, servicing options, and extended warranties, because that’s how the category functions,” he explains.
Tirumala adds that BigBasket adopted the same approach when it ventured into mobiles and mobile accessories. “When we launched this category last year, it was a trial. Today, it’s a sizable part of our business,” he says. Currently, electronics and mobile accessories contribute 5–10% of BigBasket’s monthly sales, having grown 250–300% year-on-year since the first iPhone launch on the platform.
While the launch day drives the highest demand for flagship devices like the iPhone, Tirumala notes that the following one to two months see strong accessory sales, from AirPods and headphones to chargers and power banks. “On average, mobiles and accessories account for 7–8% of our total sales, peaking at 10% during the festive season. Overall, this category has grown from zero to 7–8% of our total business in just a year, and we expect it to reach around 25% next year,” he adds.
Currently, the platform offers select models from smartphone brands, including OnePlus, Realme, Redmi, Vivo, and Oppo.
The Bengaluru-based platform is now piloting the delivery of large home appliances across across select city areas in partnership with Croma. If successful, BigBasket plans to expand this model to other cities, further broadening its quick commerce offering beyond everyday essentials.
Taneja points out that the traditional e-commerce model, once driven by discounts and affordability, is now evolving toward experience and access. Over the next few years, two major shifts will shape this transformation: credit-first commerce, where EMIs become the default mode for premium purchases, and aspirational commerce, where consumers view e-commerce as the easiest path to lifestyle upgrades. Consequently, platforms will need to reposition themselves from being “where you save more” to “where you unlock more”, prioritising personalisation, trust, and a seamless shopping experience.
As quick commerce matures, it is no longer just about instant gratification; it’s becoming a bridge between aspiration and accessibility.
Platforms are proving that speed, trust, and seamless experience can coexist with high-value purchases.
(Published in IMPACT)
