admin
November 3, 2026
Pritha Pahari, The Core
3 November 2026
India’s packaged food and soap makers are running out of easy choices. Input costs have continued to rise since late February, when the Middle East conflict began disrupting supply chains and pushing up crude-linked costs.
A visible price hike, however, risks sending shoppers to a rival. To offset this, companies have reduced package sizes. However, scope for how much these packs can be reduced is limited, especially for products already sold at low price points. Take the example of a Rs 10 pack of Parle-G biscuits.
At this price, there is little room to reduce the quantity further without risking consumer dissatisfaction. Cutting the pack size could make the product less attractive, while increasing the price may discourage price-sensitive buyers.
India’s FMCG giants have squeezed pack sizes about as far as they can go. With input costs still climbing and shoppers watching every rupee, the choice between eating the cost and raising prices is coming, likely right after Diwali.
The Hikes Are In
Britannia, Hindustan Unilever (HUL), Dabur and Godrej Consumer had already raised prices by around 2-5% in the June quarter, and were weighing more for the September quarter. FMCG companies have continued to raise prices to offset higher input costs.
FMCG companies have continued to raise prices to offset higher input costs.
Tata Consumer Products increased tea prices by 8-10% between the June and September quarters, while it raised the price of its Rs 30 salt pack to Rs 32 in May and again to Rs 34 in October.
Hindustan Unilever also took price increases of around 7.5% during the September quarter, according to media reports.
Godrej Consumer Products said it would continue calibrated price increases, particularly in soaps and liquid detergents, to manage cost pressures.
Dabur has also confirmed taking pricing actions in its October business update, while Britannia had indicated a further 1.5-2% increase, largely through smaller packs. However, the latter two companies’ September-quarter results were still awaited.
Experts said that lower-income households face greater pressure because everyday essentials take up a larger share of their budgets. Affordable products such as biscuits, noodles, soaps, detergents and cooking oils are particularly sensitive to price changes.
According to experts, some manufacturers are weighing selective price increases after Diwali, possibly from December.
Shoppers haven’t walked away yet
So far, demand is holding up. Nestlé India’s sales rose 20.5 per cent to Rs 6,782 crore in the September quarter, with double-digit volume growth.
At HUL, June-quarter underlying sales growth of 10 per cent came equally from volume and price.
The market is still nervous.
Nestlé India shares closed 7.7% lower on results day after management flagged rising input costs, especially packaging, edible oils and farm commodities.
Business Standard quoted chairman Manish Tiwary as saying, “Rising inflation, particularly food inflation, is a reality.”
India’s FMCG volume growth remains mixed, although several companies continue to report resilient demand. Tata Consumer Products’ India branded volume growth eased from 16% in Q4 FY26 to 13% in Q1 FY27 and 11% in Q2 FY27.
Marico reported that India volume growth reached near double digits in Q2 FY27, following 11% in Q1.
Dabur India recorded 5% underlying volume growth in Q1 FY27, while its October update indicated double-digit revenue growth for Q2 but did not disclose a confirmed volume figure.
Overall, demand remains resilient, but revenue growth should not be confused with volume growth, particularly as companies raise prices to offset higher input costs.
Why Smaller Packs?
Satish Meena, founder of research firm Datum Intelligence, said that companies try to absorb costs first. “They can do it for one quarter, they can do it for two quarters, but at a certain point they have to pass it on to the customer,” he said. He expects much of that to happen after the festive season.
Discounts are not an option either, since margins are thin. That leaves pack sizes. “Instead of 150 grams, we are doing 120 grams, keeping the price the same,” Meena said, describing the move.
A visible price rise carries a risk of its own.
“Your positioning in the shop will change, and customers will also perceive you as an expensive product and look for other brands,” he said. Once a rival takes the shelf space, it is hard to win it back.
Devangshu Dutta, founder of research firm Third Eyesight, says price points are hard to move. “Price points are often anchored either in the consumer’s mind or by competitive benchmark pricing, making them difficult to change,” he said.
He also said the practice now carries a reputation risk. “The shrinkflation phenomenon isn’t new, but social media has given it viral visibility, which can potentially damage brand reputation.”
Pricing Pecking Order
Meena said companies will follow a set order. First they improve buying and supply chains, then trim ad spending. Next they raise prices on premium products, where buyers are more willing to pay. Raising prices across all products comes last, so they don’t lose share.
Dutta says companies are “caught in a vice” because input costs are rising while core shoppers are cautious about spending. Companies have “no option but to cut brand-level advertising and also review overheads deeply.”
Indian FMCG companies are facing rising input costs across several product categories.
In October 2026, plastic packaging costs were reported to have increased by 30–40%, putting pressure on snack makers and household-product manufacturers.
Palm oil prices rose 21% year-on-year in September, while sunflower oil increased 14%, soybean oil 9% and mustard oil 8%.
Sugar prices climbed 18% year-on-year, adding pressure on confectionery and packaged-food producers.
Tea prices rose 10% over the same period. Coffee and cocoa also recorded increases, with Arabica coffee up 19% quarter-on-quarter and cocoa rising 48%. These increases affect biscuits, noodles, chocolates, soaps, shampoos and detergents differently.
Now What?
The next test is HUL’s September-quarter results, due after its board meets on 28 October. Meena does not expect much to change in the next one to two quarters.
He says the pressure is not seasonal. “It’s because of the war happening in the Middle East… it’s a much longer issue for them,” and he points to RBI data showing some impact on demand.
Input-cost pressures could persist into early 2027.
S&P Global’s September outlook projected elevated manufacturing costs through 2027, while October data showed plastic packaging costs 30–40% higher and key polymer prices more than 50% above pre-conflict levels.
Although prices may ease if supply routes improve, these figures suggest FMCG companies could face continued cost pressure over the next two quarters.
Dutta said only a few brands will come through easily. “Few brands or products are able to build longer-term loyalty consistently and whose value to the consumer is stickier than the resistance to price movement.”
For everyone else, the room to raise prices or shrink packs is running out.
(Published in The Core)
admin
October 30, 2026
Kartikay Kashyap, Financial Express
30 October 2026
Brands are ready to roll the red carpet for consumers this festive season. But for jewellery brands this Diwali will likely be a tad different from previous ones.
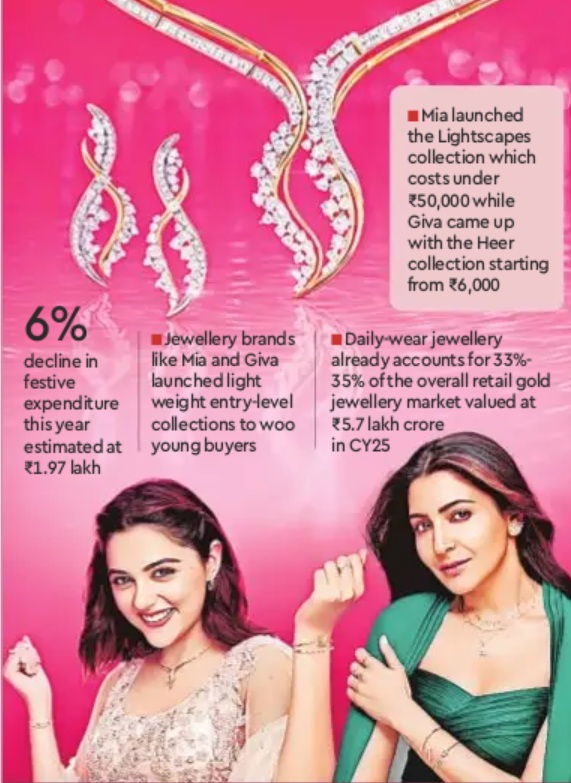
For context, consumer spending during Diwali is expected to see a decline according to Mood Of The Consumer, a survey released earlier this week by LocalCircles. On an average, urban households are looking to spend ₹20,000 in discretionary purchases this festive season, with the total spending to decline 6% from last year. The estimate puts festive expenditure at ₹1.97 lakh crores in 2026 compared with ₹2.1 lakh crores in 2025.
For jewellery brand Mia, which retails lightweight everyday jewellery, this is yet another opportunity to cast its net wider. The Titan Company-owned brand has launched Lightscapes, a new collection featuring more than 230 designs across plain gold, natural diamonds and coloured stones. The collection features a range of jhumkis, sculptural danglers, necklaces, pendants, rings and bracelets in 9KT and 14KT gold and is priced under ₹50,000 to woo first-time jewellery buyers. The supporting campaign takes forward Mia’s promise to offer women a conduit for self-expression. At the same time, the new campaign aims to push the idea of buying jewellery for festive gifting.
Mia is not the only one. Giva, which entered the gold jewellery segment during 2023 Akshay Tritiya, has introduced the Heer by Giva collection featuring polki jewellery crafted in 14 KT gold, while its Vivid Gemstone collection offers gemstone designs in 9KT and 14 КТ gold, besides a range of lab-grown diamonds. The range starts from 6,000 and goes up to ₹90,000.
The advertising pitch for jewellery brands is changing in tan-dem. If earlier they used emotion and heritage as triggers, recent advertising highlights self-expression, self-gifting and gender-neutral collections.
“The strategy to bet on affordable jewellery seems to be prompted by the surging price of gold and the hope that consumers would be keen on buying lightweight affordable jewellery this festive season,” says Devangshu Dutta, founder, Third Eyesight.
To be sure, gold prices have been volatile all of 2026. Though it has fallen more than 26% from its January record high, it is still 11.6% higher than last Diwali. For jewellery brands lightweight pieces have become the primary solution to maintaining retail volume, says Sanjeev Shukla, business advisor to fashion retailer Vinusto.in.
Lightweight jewellery has also gained traction among younger consumers in recent years. “Today’s consumers, particularly younger women, are increasingly seeking jewellery that reflects their personal style, offers versatility and fits within their budgets,” says Ajay Maurya, head of marketing & category, Mia by Tanishq. “Our focus is on making contemporary fine jewellery more accessible without compromising on design, quality or craftsmanship.”
Naresh Gupta, managing partner & chief strategy officer, Bang In The Middle, believes that younger generations especially Gen 2 buyers are drastically changing what and how they buy. Instead of heavy, occasion-led, or locker-stashed gold pieces meant strictly for weddings and festivals, they are pivoting toward lightweight, design-forward, and everyday wear. They want Indo-Western pieces that pair as well with a Diwali lehenga as they do with an office-event blazer. “The Diwali campaign strategy aligns with the jewellery retailers’ strategy to catch on the younger lot and recruit them into the ecosystem early in their stage,” says Gupta.
Daily-wear jewellery already accounts for 33%-35% of the overall retail gold jewellery market valued at 15.7 lakh crore in CY25. Organised retailers held about 37% of this market in CY25.
Apart from self-expression, light-weight jewellery also makes a good case for gifting. “Entry-level fine jewellery and budget-friendly pieces work particularly well for gifting, which makes them relevant during the festive season,” tells Disha Shah, founder, DiAi Designs.
A golden opportunity
Will Mia’s decision to take the affordability route cannibalise stable brands like Zoya and Carat Lane? If young buyers form the habit of wearing lightweight jewellery, they might do that during wedding as well, says Gupta.
One might argue that brands like Mia enable new buyers enter the fine jewellery ecosystem and move up the ladder to become the customers of brands like Tanishq and Zoya. But Vinusto’s Shukla argues repeat buying might still be a challenge for the affordable jewellery players.
For Mia, which crossed the ₹2,000-сrоге revenue milestone in the financial year 2025-26, the festive season represents a crucial window to turn up the volume. Experts say the season makes up 15-20% of the annual jewellery sales and some brands have gone on record to say they have already seen a 50% surge over pre-Diwali sales.
DiAi’s Shah remains optimistic. “We are seeing new customers explore jewellery, alongside existing customers who are looking to redesign or upgrade pieces they already own. Festive occasions provide a natural reason to enter the category, while contemporary, everyday fine jewellery can help build that relationship beyond the festive period,” she says.
(Published in Financial Express)
Devangshu Dutta
October 29, 2014
(The Hindu Businessline – cat.a.lyst got marketing experts from diverse industries to analyse consumer behaviour during the last one month and pick out valuable nuggets on how this could impact marketing and brands in the years to come. This piece was a contribution to this Deepavali special supplement.)

Two trends that stand out in my mind, having examined over two-and-a-half decades in the Indian consumer market, are the stretching or flattening out of the demand curve, or the emergence of multiple demand peaks during the year, and discount-led buying.
Secular demand
Once, sales of some products in 3-6 weeks of the year could exceed the demand for the rest of the year. However, as the number of higher income consumers has grown since the 1990s, consumers have started buying more round the year. While wardrobes may have been refreshed once a year around a significant festival earlier, now the consumer buys new clothing any time he or she feels the specific need for an upcoming social or professional occasion. Eating out or ordering in has a far greater share of meals than ever before. Gadgets are being launched and lapped up throughout the year. Alongside, expanding retail businesses are creating demand at off-peak times, whether it is by inventing new shopping occasions such as Republic Day and Independence Day sales, or by creating promotions linked to entertainment events such as movie launches.
While demand is being created more “secularly” through the year, over the last few years intensified competition has also led to discounting emerging as a primary competitive strategy. The Indian consumer is understood by marketers to be a “value seeker”, and the lazy ones translate this into a strategy to deliver the “lowest price”. This has been stretched to the extent that, for some brands, merchandise sold under discount one way or the other can account for as much as 70-80 per cent of their annual sales.
Hyper-opportunity
This Diwali has brought the fusion of these two trends. Traditional retailers on one side, venture-steroid funded e-tailers on the other, brands looking at maximising the sales opportunity in an otherwise slow market, and in the centre stands created the new consumer who is driven by hyper-opportunism rather than by need or by festive spirit. A consumer who is learning that there is always a better deal available, whether you need to negotiate or simply wait awhile.
This Diwali, this hyper-opportunistic customer did not just walk into the neighbourhood durables store to haggle and buy the flat-screen TV, but compared costs with the online marketplaces that were splashing zillions worth of advertising everywhere. And then bought the TV from the “lowest bidder”. Or didn’t – and is still waiting for a better offer. The hyper-opportunistic customer was not shy in negotiating discounts with the retailer when buying fashion – so what if the store had “fixed” prices displayed!
This Diwali’s hyper-opportunism may well have scarred the Indian consumer market now for the near future. A discount-driven race to the bottom in which there is no winner, eventually not even the consumer. It is driven only by one factor – who has the most money to sacrifice on discounts. It is destroys choice – true choice – that should be based on product and service attributes that offer a variety of customers an even larger variety of benefits. It remains to be seen whether there will be marketers who can take the less trodden, less opportunistic path. I hope there will be marketers who will dare to look beyond discounts, and help to create a truly vibrant marketplace that is not defined by opportunistic deals alone.
Devangshu Dutta
July 14, 2010
It’s curious how James Dyson consistently gets “more” (price) for “less” (components). First it was the bagless vaccum cleaner, now it is a bladeless fan. The retail price is currently pegged at £200, and the product is initially being targeted at the US and Japanese markets, which obviously have more people facing hotter temperatures for more weeks in the year than Dyson’s home country, the UK. Or perhaps a bigger market segment for the latest tech toys that perform well in addition to looking cool.
Branded the Dyson Air Multiplier, it is certainly a fan-tastic idea, and the uphill struggle should be significantly less than when he was trying to sell bagless vacuum cleaners. If anything there is now a “Dyson premium” available to him on the price.
However, in this case, the prices definitely need to be more accessible, or he’ll be facing clones within months. Fans are already a more acceptable reality in income poor countries, and the market significantly larger in those countries. At some lower price point the addressable market will be exponentially larger, and someone else will definitely tackle it. Patent or no patent.
Here’s a Youtube video of Dyson explaining how the fan works. Share your thoughts below, after you’ve watched the video.
Devangshu Dutta
May 11, 2010

REVIEW: BEATING THE COMMODITY TRAP: Richard D’Aveni (Harvard Business Press)
In his latest book, Professor Richard A. D’Aveni focusses on a topic that most businesses should be acutely concerned with: the problem of commoditization. In interviews he has accurately described commoditization as “the black plague on modern corporations” and “a deadly disease that’s spreading like crazy”.
Certainly, if one had to pick the ultimate nightmares to keep CEOs awake at night, commoditization would definitely be among the top of the list. Specifically, given the economic uncertainties around the world in the last couple of years, business leaders who are not concerned about their products or services being turned into commodities are either supremely equipped to maintain their differentiation, or immensely deluded as to their capabilities to fight market forces. Prof. D’Aveni suggests that maintaining differentiation alone is not enough to sustain business.
A product or service becomes a commodity when it is not distinguishable from competing offerings and therefore not valued above the competition. Prof. D’Aveni views commoditization along two key attributes: the benefits or features that are being offered and the price (margin) that is available to the business. Based on his model, he has identified three types of competitive stress that a business could face:
The book suggests competitive strategies that a business could take to avoid getting caught in the commodity trap. These strategies can be boiled down to the biological choice: fight or flight (escape). Professor D’Aveni echoes the basic warfare strategy laid out by many military and business strategists through the ages. He suggests that businesses need to gauge the opponents, choose their battles, and pick opponents against whom they can win. He also calls for pre-emptive action: where companies can, they should either change the business environment to avoid commodity battles entirely, or initiate the battle of commoditization and control its direction and momentum.
In fact, anticipation and pre-emption is the key to avoiding the commodity trap. To help with this, Prof. D’Aveni offers a relatively simple framework to analyse a current market situation in terms of a price-benefit matrix, and to identify the advance corrective actions to be taken.
The book is short and straight-forward enough to pick through a domestic flight, or to read in the back-seat during a long commute between office and home. The easy to understand framework gets the messages across quickly. In analysing the variations of commoditization, both in consumer and business oriented industries, the Professor also offers up something for everyone.
However, the book’s strengths also turn out to be among its biggest weaknesses. The book would have benefited from more depth to each of the concepts. Skipping quickly from one area to the other, in some places the book risks losing coherence of thought.
Some short books are like downhill hairpin bends on a mountain road; Prof. D’Aveni’s book is one of those. Much as you might be tempted to go fast, it’s advisable to go slow. If you speed through it, you might miss a nugget that actually makes sense to your business.
One of the other grouses I had was with the examples quoted. The predominantly US market examples reduce the book’s relevance for a global audience – the Professor presumes the reader will know the company and its context well enough to understand the lessons being discussed. In some cases the examples are incomplete and possibly even incorrect: one such is the example of Zara. The broad-brush attributes Zara’s business success to turning fashion into commodity, and ignores the fact that fashionability and desirability are a cornerstone of Zara’s offer, not the cheapest price. Others would possibly be far more accurate examples of commoditization in the context of price.
However, if you are sufficiently concerned about the possibility of being commoditized out of profitability, or being marginalised out of market share, I would suggest that you could easily overlook these flaws. The fundamental premise of the book is far too important to ignore. [Beating the Commodity Trap on Amazon]
(This review was written for Businessworld.)
