admin
October 30, 2026
Kartikay Kashyap, Financial Express
30 October 2026
Brands are ready to roll the red carpet for consumers this festive season. But for jewellery brands this Diwali will likely be a tad different from previous ones.
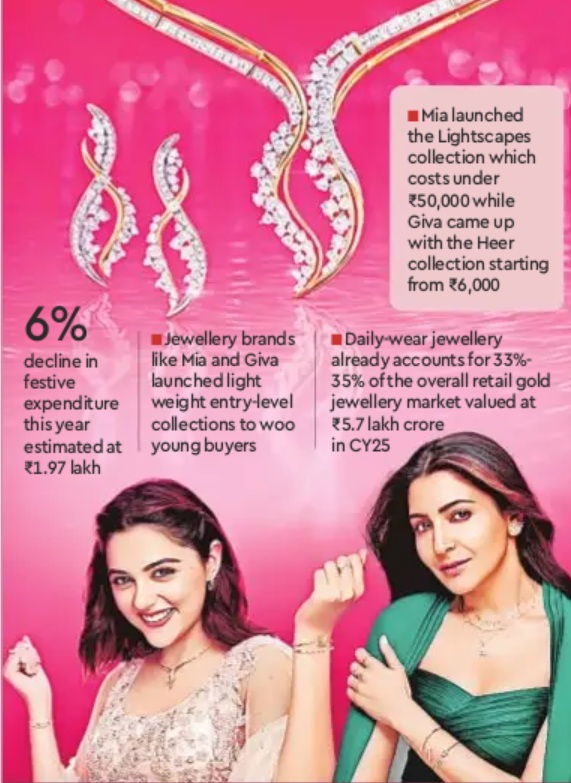
For context, consumer spending during Diwali is expected to see a decline according to Mood Of The Consumer, a survey released earlier this week by LocalCircles. On an average, urban households are looking to spend ₹20,000 in discretionary purchases this festive season, with the total spending to decline 6% from last year. The estimate puts festive expenditure at ₹1.97 lakh crores in 2026 compared with ₹2.1 lakh crores in 2025.
For jewellery brand Mia, which retails lightweight everyday jewellery, this is yet another opportunity to cast its net wider. The Titan Company-owned brand has launched Lightscapes, a new collection featuring more than 230 designs across plain gold, natural diamonds and coloured stones. The collection features a range of jhumkis, sculptural danglers, necklaces, pendants, rings and bracelets in 9KT and 14KT gold and is priced under ₹50,000 to woo first-time jewellery buyers. The supporting campaign takes forward Mia’s promise to offer women a conduit for self-expression. At the same time, the new campaign aims to push the idea of buying jewellery for festive gifting.
Mia is not the only one. Giva, which entered the gold jewellery segment during 2023 Akshay Tritiya, has introduced the Heer by Giva collection featuring polki jewellery crafted in 14 KT gold, while its Vivid Gemstone collection offers gemstone designs in 9KT and 14 КТ gold, besides a range of lab-grown diamonds. The range starts from 6,000 and goes up to ₹90,000.
The advertising pitch for jewellery brands is changing in tan-dem. If earlier they used emotion and heritage as triggers, recent advertising highlights self-expression, self-gifting and gender-neutral collections.
“The strategy to bet on affordable jewellery seems to be prompted by the surging price of gold and the hope that consumers would be keen on buying lightweight affordable jewellery this festive season,” says Devangshu Dutta, founder, Third Eyesight.
To be sure, gold prices have been volatile all of 2026. Though it has fallen more than 26% from its January record high, it is still 11.6% higher than last Diwali. For jewellery brands lightweight pieces have become the primary solution to maintaining retail volume, says Sanjeev Shukla, business advisor to fashion retailer Vinusto.in.
Lightweight jewellery has also gained traction among younger consumers in recent years. “Today’s consumers, particularly younger women, are increasingly seeking jewellery that reflects their personal style, offers versatility and fits within their budgets,” says Ajay Maurya, head of marketing & category, Mia by Tanishq. “Our focus is on making contemporary fine jewellery more accessible without compromising on design, quality or craftsmanship.”
Naresh Gupta, managing partner & chief strategy officer, Bang In The Middle, believes that younger generations especially Gen 2 buyers are drastically changing what and how they buy. Instead of heavy, occasion-led, or locker-stashed gold pieces meant strictly for weddings and festivals, they are pivoting toward lightweight, design-forward, and everyday wear. They want Indo-Western pieces that pair as well with a Diwali lehenga as they do with an office-event blazer. “The Diwali campaign strategy aligns with the jewellery retailers’ strategy to catch on the younger lot and recruit them into the ecosystem early in their stage,” says Gupta.
Daily-wear jewellery already accounts for 33%-35% of the overall retail gold jewellery market valued at 15.7 lakh crore in CY25. Organised retailers held about 37% of this market in CY25.
Apart from self-expression, light-weight jewellery also makes a good case for gifting. “Entry-level fine jewellery and budget-friendly pieces work particularly well for gifting, which makes them relevant during the festive season,” tells Disha Shah, founder, DiAi Designs.
A golden opportunity
Will Mia’s decision to take the affordability route cannibalise stable brands like Zoya and Carat Lane? If young buyers form the habit of wearing lightweight jewellery, they might do that during wedding as well, says Gupta.
One might argue that brands like Mia enable new buyers enter the fine jewellery ecosystem and move up the ladder to become the customers of brands like Tanishq and Zoya. But Vinusto’s Shukla argues repeat buying might still be a challenge for the affordable jewellery players.
For Mia, which crossed the ₹2,000-сrоге revenue milestone in the financial year 2025-26, the festive season represents a crucial window to turn up the volume. Experts say the season makes up 15-20% of the annual jewellery sales and some brands have gone on record to say they have already seen a 50% surge over pre-Diwali sales.
DiAi’s Shah remains optimistic. “We are seeing new customers explore jewellery, alongside existing customers who are looking to redesign or upgrade pieces they already own. Festive occasions provide a natural reason to enter the category, while contemporary, everyday fine jewellery can help build that relationship beyond the festive period,” she says.
(Published in Financial Express)
admin
September 1, 2026
Vikash Tripathi, Outlook Business
1 September 2026
Eight decades ago, the ‘nationalist businessman’ GD Birla helped prepare the ‘Bombay Plan’, which asked the state to pro-vide for the bare minimum needs of its people. His plan asked for 2,800 calories of well-balanced food per day, 30 yards of clothing per year and 100sq ft of housing per person.
Today, seventh-generation Aryaman Vikram Birla is betting on an entirely different opportunity: premium dining. “We continue to believe in the remarkable potential of the premium casual dining space, spurred by rising disposable income and evolving lifestyles,” the 29-year-old said after Aditya Birla New Age Hospitality acquired KA Hospitality in 2023.
The Birlas are not alone in trying to cash-in on rising prosperity in India. In the past five years alone, India’s top 10 industrial groups have announced new ventures in consumer-facing sectors or doubled down on existing ones. A rough tally of these investments crosses ₹4.8 lakh crore.
For decades, these same business houses built their dominance in core sectors like steel, power, aluminium, cement and chemicals, laying the industrial backbone of the economy. This helped the nation become a large producer of such goods and, in some cases, an exporter as well.
But as India’s economic conditions changed, so has the focus of its largest conglomerates.
For the likes of Tata, Aditya Birla, Bajaj and Bharti, that journey started way back. “What has changed in recent years is the speed and openness of the amount of capital being invested,” says Jitender Kumar, associate professor and programme chairperson, retail management programme at Birla Institute of Management Technology.
“It is not ‘opportunistic’ reasons, it’s structural reasons.”
Two factors seem to be driving the shift: the first is the arrival of an affluent consuming class that can buy branded and premium goods, and the second is the attraction of consumer businesses as a way to diversify revenue and, in some cases, improve the quality of earnings.
The Rise of Affluence
A couple of decades ago, if an Indian household had some extra cash, it often meant buying more of the same. Today, it increasingly means buying better. Even salt is being upgraded, from iodised to Himalayan pink or rock salt. The same shift is visible in bigger purchases: sports utility vehicles (SUVs) over hatchbacks, and ₹1cr-plus homes over budget flats.
But India isn’t simply consuming more. It is moving from basic consumption towards discretionary, branded and premium consumption. This boom is most clearly seen in the rapid expansion of the financial infrastructure that enables consumption. Formal retail credit penetration has more than doubled over the past decade, according to a TransUnion Cibil report, driven largely by personal loans, credit cards and consumer durable loans. Meanwhile, the government-backed Unified Payments Interface has untethered spending from the cash in a buyer’s wallet.
The signs show up across the broader consumption economy. Homes priced above ₹1cr accounted for 54% of total sales in 2025, up from just 30% in 2023—the market that decorative paints and home solutions are chasing.
Out of 4.7mn cars sold in the financial year 2025–26, SUVs accounted for more than half.
“The consumer market has grown substantially—not only through rising incomes but also the dramatic expansion of branded consumption across product verticals,” says Devangshu Dutta, founder of management-consulting firm Third Eyesight.
The bets are also getting more varied, from Reliance Retail tying up with global brands like Fenty and Skims to the Bharti Group bringing Olive Garden to India.
The Lure of Returns
For a passenger walking through an airport, the flight is only one part of the journey. There is coffee before boarding, food between flights, a lounge, retail outlets, parking and a host of other things to spend money on. For Adani Airports, those non-aero businesses are increasingly becoming the more lucrative part.
Its non-aero operations already generate about ₹2,500cr, with returns in the high-20% range, against roughly 12% from regulated aeronautical operations.
Jeet Adani, director of Adani Airport Holdings, expects the share of aeronautical revenue to fall to around 10% of total revenue, with non-aero becoming the bigger growth driver. The motivation can be seen as an escape from a return ceiling as much as a bet on rising affluence.
As Kumar puts it, consumer businesses help the conglomerates in two major ways. First, they help insulate them from volatile and often punishing commodity cycles, and second, they often offer far better returns with lower capital intensity and faster cash conversion.
Reliance Industries (RIL) shows how significant that shift can become. By 2025–26, its consumer-facing arms, Jio Platforms, Reliance Retail Ventures and Reliance Consumer Products, together contributed over 40% of group revenue and nearly 60% of operating profit.
And there is another advantage. “A small business, when it wants to build a new venture, faces constant margin pressure and often has to build its supply chain from scratch. A large conglomerate can leverage its existing scale, infrastructure and supply chain to enter a new business far more efficiently,” explains Kranthi Bathini, equity strategist at WealthMills Securities.
Different Strokes
In chasing consumers, some conglomerates are following the fastest-growing categories, while others are using their existing industrial capabilities to enter consumer-facing businesses. One is trying to build an entire ecosystem around it. But the lines between these approaches are not always clean.
Tatas is doing both: building entirely new consumer brands while also using the industrial ecosystem it has built over decades.
For Tatas, the consumer opportunity has largely been about following where spending is moving. Their consumer ventures have followed this arc longest. It began decades ago with Lakmé (1952), Tata Tea (1962) and Titan (1984). Tanishq and the expansion of Trent under brands such as Zudio are only the latest examples.
At Tata Consumer Products, once largely a staples business built around salt, tea and pulses, the focus has been shifting towards value-added foods and beverages, with ₹7,000cr spent on the acquisitions of Capital Foods and Organic India in 2024. Across companies such as Tata Digital, Indian Hotels, Air India and Tata Motors Passenger Vehicles, the group has announced close to ₹93,180cr in investment over the past five years.
Aditya Birla’s jewellery chain Indriya and its move into premium hospitality belong to the same category of ‘pull-based’ diversification.
JSW is taking a different route. It is taking its existing industrial strengths one step closer to the buyer. The group, which has traditionally been focused on areas such as steel, energy and cement, has expanded into consumer-facing areas such as auto, paints and home solutions.
It launched JSW Paints in 2019, and acquired a controlling stake in paintmaker AkzoNobel India for ₹8,986cr last year. Its strategy is to leverage an established network of contractors, dealers, architects and builders to reach consumers.
The same strategy can be seen in its push into autos, acquiring a 35% stake in the Indian unit of China’s MG Motor in 2024, leveraging synergies with its established steel business.
At Tatas, too, group companies like Tata Steel, Tata Power, Tata AutoComp, Tata Technologies and TCS are doing significant businesses with Tata Motors.
Adani is also using an asset it already controls to move further into the consumer’s wallet. Adani Airports announced a ₹20,000cr investment in June to develop hotels, retail, entertainment and commercial infrastructure around its eight airports, and has signed hotel management agreements with IHG Hotels & Resorts for five hotels. City-side developments could contribute 30–40% of Adani Airport Holdings’ non-aero revenue.
Yet another example of the extension strategy is Aditya Birla Group’s attempt to diversify from cement, metals and textiles into decorative paints with Birla Opus.
RIL took a different approach: trying to connect multiple consumer businesses into one ecosystem. It expanded its retail network through new formats and acquisitions, added brands and partnerships, and then built a consumer-goods business around acquisitions such as Campa Cola and Lotus Chocolate.
That expansion was helped by billions of dollars raised by both Jio Infocomm and Retail Ventures from foreign investors in 2020. The group now plans to spend another ₹8,000cr expanding consumer goods manufacturing. The advantage of having that kind of scale is clear. If RIL has Ajio at a mall and, next to it, GAP and Herschel, it can negotiate better rental terms.
For conglomerates, Kumar points out, the next level of competition will not be based on investment, “but on the ability to create different consumer experiences, foster innovation and create lasting brand loyalty through the integration of these capabilities”.
Can Scale Win?
When Reliance Fresh opened its first stores in 2006, it was part of a rush by some of India’s biggest business groups to crack organised retail. Aditya Birla Group, RP-Sanjiv Goenka Group’s Spencer’s and Kishore Biyani’s Future Group were all betting that organised retail could transform the way Indians shopped. What followed was years of experimentation, losses and, for some, eventual retreat.
Birlas essentially gave up on grocery retail after a decade of heavy losses and exited entirely.
Future was pushed into insolvency after a controversial ₹24,713cr deal with RIL. Spencer’s is still trying to find its footing, with ₹249.33cr in net losses in 2025–26.
Conglomerates may have deeper pockets, but that does not automatically make them better at selling to consumers. India has seen some of those bets fail or take years to work. And even among today’s biggest players, the results are still mixed.
Tata Sons has been in this segment longer than the Ambanis, yet its consumer businesses still make up less than 40% of its total revenue —a share that has not changed since 2020.
These groups have what most standalone consumer companies don’t: capital, distribution, infrastructure, brands, scale.
But winning consumers takes something else entirely—reading what people want, building brands, innovating fast and earning loyalty.
“In B2B [business to business], it’s about manufacturing at scale, getting your costs down. Then you can compete. In B2C [business to consumer], it’s all about the product. With the right product at the right price, you have a chance to win in the market,” Parth Jindal, managing director of JSW Cement and JSW Paints, told Outlook Business in 2025.
Tata Sons’ chairman N Chandrasekaran hit the same wall while revamping the group’s consumer unit. “I have the money. But I don’t have the team to run it,” he had told Sunil D’Souza while hiring him to lead Tata Consumer Products in 2020.
Reliance and Tatas have had the longest head start, but even their journeys show how difficult it is to turn scale and capital into consumer businesses. Birla, JSW and Adani are now trying to make that transition in their own ways.
A longer tail—Bajaj in hospitals, L&T in retail finance and education, Mahindra in insurance and hospitality, Murugappa in electric mobility—is playing it safer, going deeper into what it already owns rather than chasing new categories.
What ties them together is a bet on consumers buying not just more but better, and on those consumers being worth more per rupee of capital than the industrial customers who built these houses.
The prize is growing, but so is the competition. Capital and scale may get these conglomerates through the door. They won’t guarantee a seat at the table.
(Published in Outlook Business)
admin
July 27, 2026
Vaeshnavi Kasthuril, MINT
Bengaluru, 27 Jul 2026
Over the past six years, Trent Ltd has grown its revenue more than fivefold, outpacing Titan Co. Ltd, Tata Consumer Products Ltd (TCPL) and Voltas Ltd to become the fastest-growing established company in Tata Sons’ consumer and retail portfolio.
Trent, incorporated in 1998, is the youngest among the Tata group’s four major listed consumer businesses. Voltas was incorporated in 1954, TCPL traces its origins to Tata Tea, established in 1962, while Titan was incorporated in 1984.
While Titan remains the group’s largest consumer business by revenue, Trent has overtaken Voltas and nearly caught up with TCPL.
Trent’s revenue rose to ₹20,189 crore in FY26 from ₹3,635 crore in FY20, showed Tata Sons’ FY26 annual report. In comparison, Titan’s revenue expanded 4.2 times, while TCPL and Voltas grew 2.1 times and 1.8 times, respectively. Six years ago, Trent accounted for just 8.6% of the combined revenue of the group’s four major consumer businesses. In FY26, that share has climbed to 14.1%, close to TCPL’s 14.3%.
Trent’s portfolio includes Westside and Zudio in fashion, Samoh and Burnt Toast in newer lifestyle formats, and Star in grocery retail.
Zudio effect
The growth has been driven by Trent’s aggressive expansion across value and premium fashion. Zudio has emerged as the retailer’s biggest growth engine, benefiting from rising demand for affordable fashion among middle-income consumers, while Westside has continued to strengthen its presence in the premium apparel and lifestyle segment.
Zudio has been “a phenomenal driver of revenue growth”, with the retailer aggressively expanding the format over the past few years, said Devangshu Dutta, founder of retail consulting firm Third Eyesight.
He said Trent has also benefited from a structural shift in the country’s retail landscape as consumers increasingly move from fragmented, unorganised markets to organised retail. “The conversion from informal to formal happens not so much driven by demand but by availability. So if you open a new outlet… you have something which was not there earlier, which becomes a magnet for footfall,” Dutta said.
He said that Zudio’s combination of fashion-led products and sharp pricing has helped it stand out in the crowded value apparel market.
The retailer has simultaneously expanded beyond apparel into adjacent categories such as beauty and personal care, home décor, footwear, and accessories through Westside, while also nurturing newer concepts, including Samoh, Burnt Toast, and Star.
During FY26, Trent added 289 stores, taking its total network to 1,286 outlets across 321 cities and expanding its retail footprint to more than 17.7 million sq. ft.
The company said it sees opportunities to increase store density in existing markets while expanding into new cities, particularly as demand for organized retail continues to deepen beyond the country’s largest metropolitan areas.
The next phase of growth is likely to be driven by Westside. According to media reports, Trent plans to significantly accelerate the expansion of its flagship premium fashion chain by opening up to 100 stores annually, nearly double its historical pace. The chain, which had 300 stores at the end of FY26, is expected to expand into newer geographies, including the northeastern states, while strengthening its presence in key metropolitan markets.
Dutta said macroeconomic uncertainty, including the impact of geopolitical tensions and softer employment conditions, could weigh on discretionary spending. “If there is uncertainty, then you tend to be a little bit more careful,” he said.
Dutta said that while consumer demand may fluctuate in the short term, the long-term shift towards modern retail remains firmly intact.
Noel Tata’s farewell message
The FY26 annual report also carries Noel Tata’s final message as chairman of Trent, marking the end of an era for the retailer he helped transform into one of India’s largest fashion retailers.
Tata reiterated his long-held ambition of building Trent into a platform capable of creating and scaling multiple consumer businesses rather than relying on a single retail format. “I have long believed that Trent is not intended to be defined by a single brand, but rather by a portfolio of brands,” he wrote, adding that Westside, Zudio and Star continue to have significant runway for growth.
Looking ahead, he said Trent should aspire to build Indian brands with global relevance and generate a material share of revenues from overseas markets.
He also recalled his vision, first articulated in 2023, of making Trent ten times larger in terms of revenue with commensurate profitability, noting that the company’s revenue and profitability run rate have already grown more than 2.5 times since then.
The company has not yet named a successor to Noel Tata, who is set to retire as chairman in November.
(Published in MINT)
admin
June 30, 2026
Vaeshnavi Kasthuril, MINT
30 June 2026, Mumbai
Advent International-backed Modenik Lifestyle Pvt. Ltd is doubling down on its portfolio of legacy innerwear brands, planning to scale each label into a sizeable business rather than rely on a single flagship brand.
“Each of the brands must grow big enough to be called a company of its own,” Shekhar Tewari, chief executive and executive director, told Mint.
The company has four brands: premium women’s innerwear label Enamor, value brand Slimz, mass-premium men’s label Dixcy Scott, and premium men’s innerwear brand Levi’s. “These brands are very strong in their respective segments. They complement each other rather than compete,” Tewari said.
Levi’s Innerwear is priced between ₹250 and ₹550, Dixcy Scott and Slimz between ₹100 and ₹350, while Enamor’s products start at ₹500 and go beyond ₹2,500.
The strategy comes as India’s innerwear market, particularly women’s lingerie, has become one of the country’s most fiercely contested apparel categories, with established retailers and digital-first brands vying for market share.
Modenik’s focus on innerwear deepened after private equity firm Advent brought Enamor and Dixcy together under Modenik Lifestyle, following its acquisition of Enamor from Gokaldas Exports in 2019.
Both brands had expanded into adjacent categories such as athleisure, loungewear, sleepwear and outerwear, but struggled to keep pace with rising competition from fashion retailers and digital-first brands. The company has since exited much of its outerwear portfolio, taking a revenue hit.
“We took a conscious hit on the top line because we wanted to become a focused innerwear company,” Tewari said. “If you’re trying to be everything to everyone, you end up not being known for anything. We wanted consumers to think of us first when they think of innerwear.”
Revenue has remained largely flat at around ₹1,200 crore over the past three years, though losses have narrowed sharply. FY25 revenue stood at ₹1,224 crore, while net loss halved to ₹24.8 crore from ₹50.8 crore a year earlier.
Modenik aims to outpace the industry’s single-digit growth by increasing branded penetration in women’s innerwear, expanding its premium portfolio and adding exclusive store network, expected to cross 100 outlets in the near term.
The company sees significant headroom in women’s innerwear, where it estimates the market at more than ₹20,000 crore, but organised brands account for only ₹3,000-4,000 crore. It expects formalization, premiumization and product innovation to accelerate brand adoption.
According to Devangshu Dutta, chief executive of retail consultancy Third Eyesight, the market’s increasing fragmentation makes a multi-brand strategy more effective.
“You can’t have one brand stretching across multiple segments. The product has to be different, pricing strategies are different, the messaging and the distribution channel mix also varies depending on the consumer segment you’re trying to target,” he said.
According to industry estimates, India’s innerwear market is valued at over ₹90,000 crore (about $10.9 billion) and is expected to grow at a 6-7% compound annual growth rate (CAGR) over the next decade.
Advantages and avenues
Tewari believes Modenik has structural advantages over many digital-first rivals. Unlike online-first brands that typically outsource manufacturing, the company controls product development and manufacturing while leveraging decades-old relationships with distributors, department stores, exclusive brand outlets and multi-brand retailers.
“Those capabilities have been built over decades. They cannot be replicated overnight,” he said.
The company is also expanding across channels. Enamor is available through 6,000-7,000 multi-brand outlets, nearly 80 exclusive stores, department stores, including Shoppers Stop, Lifestyle, Central and Pantaloons, besides online marketplaces and quick commerce platforms. E-commerce contributes over 30% of Enamor’s revenue.
Although digital commerce is growing rapidly, Tewari believes physical retail will continue to play a critical role in the category.
“Innerwear is a category that requires understanding of fit, size and functionality. Consumers still want to touch, feel and try products before making the switch from unbranded to branded,” he said.
Rather than pursuing acquisitions, the company plans to unlock growth from its existing portfolio.
The strategy comes as competition in India’s innerwear market is intensifying. Page Industries dominates through Jockey, while Reliance Retail, which houses brands such as Clovia, Marks & Spencer and Hunkemöller, acquired digital-first lingerie platform Zivame, and added premium lingerie brand amanté. Aditya Birla Fashion and Retail has expanded Van Heusen Innerwear, while Trent has strengthened its innerwear offering through its private label brands at Westside and Zudio. New-age brands such as Shyaway, Bummer and Nykd by Nykaa have also stepped up investments in their products.
(Published in MINT)
admin
June 22, 2026
Sharleen D’souza & Shivani Shinde, Business Standard
Mumbai, 21 June 2026
Online beauty marketplaces Reliance Retail Ventures’ Tira and Nykaa have a common mantra: growing in-house brands. Successful brand acquisitions and margin growth seem to fuel the push.
“With private labels, margins are better. It also helps both companies plug the gap in the market which other brands are not present in,” Devangshu Dutta, chief executive officer (CEO) of Third Eyesight, told Business Standard. Within in-house brands, products need some investment in research and development (R&D), he explained.
Harish Bijoor, brand and business strategy consultant at Harish Bijoor Consults, said that margins are better for platforms with in-house brands.“Typically most companies are getting insular. The idea is to own brands and own the profits from those brands. When you are a marketplace, you put in effort for other brands, this strategy helps marketplaces lock in on profits instead of losing out to other brands, which sell on the platform,” he said.
At the 49th annual general meeting of Reliance Industries (RIL) on Friday, Isha Ambani, executive director of Reliance Retail Ventures Ltd, and non-executive director of RIL, had laid out plans for Tira. “We will scale our own brands to consumers across India and beyond, ensuring Indian beauty prod-
ucts stand proudly alongside the world’s leading global giants.”
Its in-house brands include Puraveda, Pahadi Local, haircare brand Anomaly, which was recently acquired from actress Priyanka Chopra Jonas, and skincare and make-up brand Akind, which it co-created with Mira Rajput Kapoor. Its portfolio also includes Nails Our Way and Dream Immerse Play.
Ambani’s statement had come a day after Nykaa’s management had also hinted at expanding its in-house brands on its investor day on Thursday. The platform, operated by FSN E-Commerce Ventures, outlined an ambitious road map to become an over $5 billion beauty and lifestyle business.
The growth of Nykaa’s “House of Brands” is expected to be significant. The management aims to be the largest house of brands business in India by financial year 2030 (FY30). Management has guided toward a net sale value (NSV) compounded annual growth rate (CAGR) of 30 per cent over FY26-30, taking the NSV from Rs. 1,700 crore in FY26 to Rs. 5,000 crore by FY30.
The “House of Nykaa” GMV grew over 65 per cent in FY26, with an improvement in profitability. In a report on the company’s focus on in-house brands business, Motilal Oswal said, “House of Brands is expected to grow faster than the core marketplace business and become a meaningfully larger contributor to group revenues and profits by FY30. We believe profit contribution is expected to increase disproportionately, given the higher gross margins, stronger pricing control, and lower dependence on third-party brands.”
Nykaa’s platform creates a structural incubation advantage, it said. “Fashion today serves about 300,000 styles across categories, while customer discovery increasingly happens through content, personalisation, and creator-led commerce. This allows the company to identify emerging brands and categories early, before allocating capital behind them,” the report added.
As of the fourth quarter of financial year (FY26), “House of Nykaa” had 12 brands across Beauty and Fashion categories at various growth stages, and two successful acquisitions of Dot & Key and Earth Rhythm. Dot & Key has grown 13 times over the last three years, while Kay Beauty has grown three times over this period, said the company. During the Q4FY26 results, the company had said that the strong performance of “House of Nykaa” had impacted margins positively. P Ganesh, chief financial officer, FSN E-Commerce while explaining the margin growth said, “…with gross margin improving by 132 basis points
in FY26, led by strong performance of House of Nykaa and improved service income across businesses.”
For FY26, “House of Nykaa” delivered a strong Rs. 3,176 crore of GMV. “That’s an about 50 per cent year-on-year increase. Served more than 17 million consumers and expanded distribution beyond online as well to 150,000 GT doors. As a reminder, this unit includes brands across beauty and fashion, seven brands in Beauty and in Fashion five brands, with an increased focus on one in particular, which is Nykd,” said Adwaita Nayar, executive director, cofounder and chief executive officer, “House of Nykaa Brands”, during the fourth quarter results.
(Published in Business Standard)
