
admin
January 28, 2026

What does it actually take to build a fashion brand in India?
This panel (“Beyond the Noise- How D2c Fashion Brands Are Reinventing Retail”) at the 25th Edition of India Fashion Forum focussed on some real answers, in a refreshing, down-to-earth conversation moderated by Devangshu Dutta (Founder, Third Eyesight), with the founders of DeMoza (Agnes Raja George), The Mom Store (Surbhi Bhatia), Miraggio (Mohit Jain), BeyondBound (Tejasvi Madan), and Bari (Sameer Khan Lodhi).
No fluff, no “disrupting the industry” talk. Just founders being honest about what’s worked, what hasn’t, and what they’d do differently. A few things that struck a chord:
• Every single brand started because the founder couldn’t find something they personally wanted: inclusive activewear, affordable handbags that didn’t look cheap, good maternity wear. Sometimes the simplest observation is the best business idea.
• Inventory management came up often. One founder took their inventory cycle from 6 months down to 4. Another re-shuffles stock every 15 days based on what’s selling where. Unglamorous? Yes, but this is what actually keeps a business alive.
• The marketing conversation highlighted a move away from traditional advertising toward things that actually make people feel something. One founder talked about turning a farmhouse into a full “apricot colour” experience for customers. Another shoots content with real customers, not influencers.
• And the most memorable line of the whole discussion came from the most experienced founder in the room sharing a learning: “I won’t open stores fast.” No explanation needed, really.
Building a brand is exciting. Keeping it alive is the harder, quieter work. This panel was a good reminder of that. Worth a watch if you’re building something in this space.
admin
December 15, 2025
By Saumyangi Yadav, Entrepreneur India
Dec 15, 2025
India’s D2C ecosystem has grown rapidly over the past five years, but scale remains elusive. While thousands of brands have launched and many have crossed early revenue milestones, only a small fraction manage to break past INR 100 crore in annual revenue. According to a new report by DSG Consumer Partners, based on a survey of over 100 Indian D2C founders and operators, the problem is not demand or product-market fit, it is how brands attempt to scale.
The report shows that around 60–65 per cent of Indian D2C brands remain stuck in the INR 1–50 crore revenue band, with very few reaching the INR 100 crore mark. This stage marks the point where early traction exists, but growth begins to strain unit economics, teams, and operating systems.
Insights from over 100 D2C founders reveal that India’s fastest-growing brands win on fundamentals rather than speed alone. Clear product-market fit, disciplined data tracking, strong unit economics, creative velocity, and an early focus on retention consistently separate scalable brands from those that plateau. Founders also admit that performance marketing mistakes, pricing missteps, and weak creative systems slow growth far more than budget constraints. In a booming D2C landscape, capability gaps in operations, brand-building, and supply-chain depth are widening the divide between breakout brands and those stuck in the performance plateau.
Industry observers argue that this is where many brands mistake rapid online growth for sustainable scale.
As Devangshu Dutta, Founder & CEO, Third Eyesight, explains, “Scaling up online can be very rapid, but is also capital-hungry in terms of CAC. Given the intense competition, the lack of customer stickiness and the power of platforms, there is a constant churn of marketing spend which is a huge bleed for growing brands.”
CAC Inflation is The Real Constraint
One of the clearest findings from the playbook is that acquisition efficiency, rising CAC and unstable ROAS, is the single biggest blocker to growth, cited by more founders than funding or category expansion. Moreover, over 70 per cent of brands rely on Meta as their primary acquisition channel, increasing vulnerability to auction pressure and platform-driven volatility.
Dutta links this directly to the limits of a digital-only mindset. “Limited offline expansion can trap brands in narrow urban digital markets, blocking broader scale,” he said.
This over-reliance on online performance marketing often leads to growth that looks strong on dashboards but weak on cash flow.
Highlighting their report, Pooja Shirali, Vice President, DSG Consumer Partners, said, “Across over 90 consumer brands we’ve partnered with at DSGCP, one truth is clear: brands that master Meta’s ecosystem don’t just grow, they change their entire trajectory through strategic clarity and disciplined execution. The real drivers of scale have less to do with viral moments, and everything to do with the long-term fundamentals that make milestones like the first INR 100 crore predictable, not accidental.”
Why Omnichannel is Unavoidable
The report suggests that brands that scale sustainably are those that reduce overdependence on paid digital acquisition and expand their distribution footprint. However, offline expansion brings its own complexity.
Dutta stresses that omnichannel is not an optional add-on, but a strategic shift. “D2C brands must adopt an omnichannel approach, blending online with offline retail for sustainable and scalable reach. Clearly the channels work very differently and management teams have to be prepared and capitalised for the long haul to tackle acquiring customers with channel-appropriate strategies,” he adds.
This aligns with the DSGCP report’s broader insight that scale breaks down when brands fail to adapt operating models as they grow.

Even within digital channels, performance weakens over time. The playbook finds that 62 per cent of founders report creative fatigue, where repeated creatives fail to sustain ROAS despite higher spends. At the same time, 55 per cent admit to under-investing in CRM and retention, with most brands reporting repeat purchase rates of just 10–30 per cent.
Both the data and expert opinion point to a common theme: brands that cross the INR 100 crore mark are structurally different. They obsess over unit economics, processes, and capital efficiency rather than topline growth alone.
As Dutta puts it, “Scalable brands that cross the growth hump have leadership obsessed with unit economics and omnichannel execution rather than chasing vanity metrics. Cash always was and is king, especially at early stages of growth.”
He adds that execution strength matters as much as strategy. “They are able to grow and steer teams that build and replicate processes fast rather than spending time, effort and money reinventing all the time, and do so without constant CXO intervention.”
As competition intensifies and capital becomes more selective, the next generation of INR 100 crore D2C brands is likely to be defined not by speed, but by the ability to compound cash flows, institutionalise processes, and scale distribution beyond digital platforms.
Saumyangi is a Senior Correspondent at Entrepreneur India with over three years of experience in journalism. She has reported on education, social, and civic issues, and currently covers the D2C and consumer brand space.
(Published in Entrepreneur India)
admin
November 13, 2025

Saumyangi Yadav,Entrepreneur
Nov 13, 2025
India’s consumer landscape is undergoing a decisive shift in 2025. While D2C brands that once thrived on digital-only distribution are now aggressively building an offline footprint, legacy FMCG majors are simultaneously acquiring digital-first brands to strengthen their portfolios and tap into new consumer behaviours.
As analysts suggest, these trends signal a maturing phase for India’s D2C ecosystem, one that blends physical retail and strategic consolidation.
Offline Push Accelerates
According to a recent CBRE report, ‘India’s D2C Revolution: The New Retail Order’, D2C brands leased nearly 5.95 lakh sq ft of retail space between January and June 2025, accounting for 18 per cent of all retail leasing during this period, up sharply from 8 per cent in the first half of 2024. Fashion and apparel dominated the expansion, contributing close to 60 per cent of D2C leasing, followed by homeware and furnishings and jewellery at about 12 per cent each, while health and personal care brands accounted for roughly six per cent. The shift is equally visible in the choice of retail formats: 46 per cent of D2C leasing went to high streets, 40 per cent to malls, and the remaining to standalone stores, reflecting the category’s growing focus on visibility, trial and experiential discovery.
Experts suggest that it represents a strategic pivot to blended engagement.
As Devangshu Dutta, CEO of Third Eyesight, notes, “India’s D2C surge is powered by digital-first consumers, tremendous improvement in seamless logistics, and low-cost market entry, supported subsequently by substantial amounts of investor capital chasing those startups that stand out from the competition. Yet, lasting success demands a more holistic view: the divide between online and offline is a business construct, not a consumer reality. The larger chunk of retail sales still happens through physical channels and, for brands that want to be mainstream, an omnichannel presence is absolutely essential.”
This also aligns with the broader market outlook. The India Brand Equity Foundation (IBEF), in its Indian FMCG Industry Analysis (October 2025), estimates the value of India’s D2C market at USD 80 billion in 2024, with expectations of crossing USD 100 billion in 2025. Much of this growth is being led by categories that combine frequent purchase cycles with strong digital discovery, beauty, personal care, and food and beverage segments where consumers are open to experimentation but demand authenticity, transparency, and a compelling product narrative.
“The Gen Z and millennial consumer cohorts value newness but also authenticity and unique product stories, which are best communicated in spaces that are controlled by the brand,” Dutta added, “In the launch and growth phases, this could be the brand’s digital presence including website and social media, but over time this can include pop-up stores, kiosks, shop-in-shops and even exclusive brand stores.”
CBRE’s data reflects this shift clearly, with D2C brands increasingly opting for flexible store formats and high-street locations to maximise traffic and visibility.
M&A Gains Momentum
Parallel to the offline push is a noticeable wave of consolidation. Large FMCG companies are accelerating acquisitions to capture emerging consumer niches and strengthen their digital-native capabilities.
In recent years, Hindustan Unilever has acquired Minimalist; Marico has bought Beardo, Just Herbs, True Elements, and Plix; ITC has taken over Yoga Bar; and Emami has secured full ownership of The Man Company. These deals, reported widely across business media in 2024 and 2025, point to the need for established companies to fast-track entry into high-growth, ingredient-forward, and youth-focused categories without the lead time of in-house incubation.
“Legacy FMCG companies are acquiring D2C brands to rapidly gain access to new consumer segments, product innovation, and digital-native capabilities, including direct engagement and insights. Such deals enable large companies to diversify portfolios, accelerate entry into trending segments by-passing the initial launch risks, and rejuvenate their brands with modern digital marketing expertise,” Dutta explained.
Challenges and Risks
But the acquisitions do not come without risk and challenges, analysts warned.
“However, integrating D2C operations also poses challenges, including cultural differences, the risk of stifling entrepreneurial agility, and the need to harmonise data and omnichannel strategies. The ability to nurture acquired brands without diluting their distinctive appeal will determine acquisition success,” Dutta added.
Yet even as the ecosystem expands, challenges remain. Offline stores add operational complexity, inventory planning, staffing, last-mile logistics, and real-time data integration. Still, the bottom line is that India’s D2C sector is moving into a hybrid era defined by tighter omnichannel integration, sharper product storytelling, and portfolio realignment through acquisitions.
(Published in Entrepreneur)
admin
September 5, 2025

Shalinee Mishra, Exchange4Media
5 September 2025
Retailers in India are waking up to a hard truth: customer acquisition can no longer ride on advertising alone. Digital ad spends grew by 14-17% in 2024, touching nearly ₹50,000 crore (as per Pitch Madison report) and accounting for 46% of India’s total ad market. But with customer acquisition costs (CAC) rising 30-35% year-on-year and consumer attention fragmented across platforms, the ad-first growth engine is showing strain. What is emerging instead is an ecosystem where content in the form of video, celebrity-led storytelling, or creator-driven engagement is becoming the direct funnel to commerce.
Flipkart for instance is building influencer production hubs and embedding shoppable videos, Myntra has rolled out its video-first Glamstream, and Amazon has long blurred the line between streaming and shopping through Prime Video and Fire TV. From short videos to celebrity gossip, from beauty blogs to shoppable livestreams, e-commerce giants are no longer just marketplaces; they are evolving into media houses and the trend is only growing.
According to Mindshare’s latest Content Trend Report, India’s branded content marketing industry is now worth ₹10,000 crore, growing at nearly 20% annually, with video formats making up almost half of all spends.
India already has over 270 million online shoppers, a number that Bain projects will rise to 350 million by 2027, making it the world’s second largest e-retail user base. That scale is creating fertile ground for shoppable video and live commerce to take off.
Globally, branded content spend is projected to cross $500 bn by 2027. As per PwC estimates, India’s share is still <2% but among the fastest growing.
Video commerce today largely follows two prominent models. The first is driven by social platforms such as YouTube, Instagram, and Facebook, where shoppable posts allow users to move directly from content to purchase. The second is led by e-commerce platforms like Amazon, Myntra, Nykaa, and Flipkart and others which have added video sections to create immersive shopping experiences within their apps.
Within this, live commerce has emerged as a high-potential format. Meesho and Flipkart, for example, are leading the charge with 2-3% conversion rates, generating an estimated $150-200 million in GMV during festive 2024. Events like Flipkart’s Big Billion Days show how timed livestreams can capture active, purchase-ready audiences.
Meanwhile, influencer-led short videos are driving conversion rates as high as 63%, with beauty and personal care (BPC) and food & beverages (F&B) among the top categories benefiting from this shift. Redseer projects India’s live commerce market could touch $4-5 bn GMV by 2027, up from less than $300 mn today. This surge in shoppable video and live commerce is only the surface of a deeper structural change, one where content itself is becoming the moat that protects brands from rising ad costs, fragmented attention, and fickle consumer loyalty.
Beyond ads: Why content has become retail’s strongest defence
Chirag Taneja, co-founder of e-commerce enablement company GoKwik, framed the trend as a fundamental shift in ownership.
“It’s not just about enhancing top-of-funnel reach, it’s about owning demand, connection, and the touchpoint with end shoppers. For years, brands relied on ads to bring traffic. But acquisition costs have been rising, attention is fragmented, and privacy shifts have made targeting difficult. That’s why content is now the moat. When companies acquire content firms, they’re not just buying eyeballs, they’re securing access to communities that trust and engage with that content.”
According to him, content is collapsing the traditional funnel. “One short video or livestream can take a consumer from awareness to purchase in under a minute. That’s why we see D2C brands treating content as a compounding asset, not just an expense,” he added.
Devangshu Dutta, founder and CEO of management consulting firm Third Eyesight, echoed the sentiment.
“Large companies are buying or partnering with content-driven platforms to capture attention beyond transactional touch points. Short video, regional language content, and influencer-driven discovery are embedding commerce within entertainment. If you want to sell more than a commodity, storytelling is critical. Content builds credibility, differentiation, and trust in a cluttered and price-sensitive market.”
Flipkart bets big on media and creators
The shift is already reshaping strategy at India’s biggest retailers, and Flipkart has moved fastest. Its move to acquire a majority stake in Pinkvilla, a platform built on entertainment and celebrity news signals a clear push to deepen ties with Gen Z and millennials, a cohort that consumes content first and shops later.
“Our acquisition of a majority stake in Pinkvilla is a critical step in our mission to deepen our engagement with Gen Z. Pinkvilla’s robust content IPs and strong connection with its loyal audience base are assets that will accelerate our efforts to leverage content as a key driver of growth,” said Ravi Iyer, Senior Vice President, Corporate at Flipkart.
Flipkart in the last year has exited investments in companies like Aditya Birla Fashion & Retail, where it sold its 7.5% stake in the owner of Pantaloons, Van Heusen, Louis Philippe and Forever 21, as well as BlackBuck, the trucking marketplace that powers India’s mid-mile logistics.
At the same time, the company has doubled down on content and creators. Its Pinkvilla acquisition gives it access to a platform reaching over 60 million monthly users, while in-house features like Flipkart Feed already clock 5–6 million daily video views, highlighting how commerce and content are converging at scale.
Alongside this, Flipkart has launched Creator Cities in Mumbai, Bengaluru and Gurgaon, production hubs designed for influencers to shoot and scale shoppable content.
It has also introduced Flipkart Feed, a TikTok-style vertical video feature embedded in its app, offering bite-sized, influencer-led, fully shoppable videos. Myntra, its fashion arm, has developed Glamstream, with more than 500 hours of video-first shopping content across music, beauty, travel and weddings, featuring stars like Badshah, Tabu, Zeenat Aman and Vijay Deverakonda.
Flipkart has also partnered with YouTube Shopping, allowing creators with over 10,000 subscribers to tag Flipkart products in videos, Shorts and livestreams, enabling viewers to buy directly while creators earn commissions.
Amazon’s head start in content-commerce convergence Flipkart is not alone. Its biggest rival Amazon has long understood this convergence. Through Prime Video and its original programming slate, Amazon has built an entertainment ecosystem that doubles as a commerce funnel. The shows and films on Prime do not merely entertain; they drive shopping behaviour, influence trends, and lock audiences into Amazon’s larger universe of services. With Fire TV and Alexa integrations, the company has blurred the line between watching and buying, a model others are now racing to replicate.
D2C brands treat content as growth engine
Closer home, the Good Glamm Group, now closed, had pioneered a content-led commerce ecosystem in beauty and personal care. Through acquisitions like ScoopWhoop and MissMalini Entertainment, the group stitched together a portfolio where content platforms brought in audiences, who were then nudged towards its direct-to-consumer brands.
This “editorial-to-checkout” model demonstrated how cultural capital could be translated into purchase pathways. Alibaba has taken the strategy global. With stakes in Youku, a leading video-streaming platform, and Alibaba Pictures, the e-commerce titan integrates entertainment with retail operations. Taobao Live has shown how livestream shopping can dominate consumer behavior, particularly inAsia, creating billion-dollar shopping events entirely dependent on
entertainment-driven discovery.
Shopify, meanwhile, has invested in tools that empower merchants to become content creators themselves. Its partnerships with agencies like Sanity and investments in platforms such as Billo reflect a clear intent to enable retailers to embed storytelling, gamification, and user-generated content into their selling journey. Unlike large marketplaces, Shopify’s vision is not to own the content but to democratize access to it for small and mid-sized businesses.
From content to commerce
This content includes newsletters, creator partnerships, branded podcasts, and niche communities on social media. The idea, as industry experts note, is to treat content as an asset that compounds, not just as a cost.
Unlike ads, content continues to generate discovery and engagement long after it’s published. That’s why more D2C brands are making content central to their growth strategies.
Several big names are experimenting in this space. Durex, Plum, Mother Dairy, and HDFC Bank have launched their own podcasts where celebrities share stories along their brand journey. Founder-led podcasts too are on the rise on YouTube, with voices like Nitin Kamath and Deepinder Goyal drawing large audiences in India.
The big question, however, is whether content consumption can effectively be converted into product discovery and purchase pathways. “It’s already happening at scale,” said Taneja. “Content is redefining every aspect of the traditional funnel. In the past, you had awareness at the top, intent in the middle, and purchase at the bottom. Today, one short video or live stream can take a consumer through that entire journey in under a minute.
“From a D2C lens, this convergence is even more critical. D2C brands thrive on agility, the ability to turn trends, storytelling, and community engagement directly into sales. Platforms like Instagram, YouTube, TikTok, and even WhatsApp have embedded shoppable features, which means the content is no longer just ‘top-of-funnel.’ It’s the storefront. But the magic lies in authenticity and design. Consumers don’t want to feel ‘sold to’, they want to feel entertained, inspired, or educated. If the content does that well, conversion becomes a natural byproduct. For example, an athleisure brand showing a workout routine isn’t just demonstrating leggings, it’s giving value. The leggings purchase becomes an easy next step, not a forced pitch.”
The big question: Will content sustain sales at scale?
Taneja further reveals how content is driving sales and long-term growth. “The smartest brands, especially in D2C, have realized that high-quality
content is their most defensible growth engine. Performance marketing will continue to play a role, but the real long-term moat is the kind of content that builds relationships, trust, and recall. Consumers today are spoiled for choice. They don’t buy just products, they buy stories, values, and communities.
“High-quality content allows a brand to consistently show up in ways that feel relevant and credible. And from a business lens, it directly impacts unit economics: it reduces CAC because organic discovery compounds over time, improves LTV because content nurtures loyalty and repeat purchases, and builds resilience because brands with strong content ecosystems are less dependent on fluctuating ad platforms.”
The D2C ecosystem in India is already proving this point. Beauty and personal care brands now run editorial-led platforms alongside commerce, while fashion labels thrive on creator collaborations and storytelling-driven product drops. Their growth is not accidental but built on content strategies that treat every piece not just as a post, but as a business driver.
As an enabler, Taneja adds, the results are visible across platforms. “Brands that invest in content see better conversions on our checkout stack, lower cart drops, and stronger repeat cohorts. Content doesn’t just spark sales it sustains them.”
For all the optimism, the test for content-driven commerce will lie in scale and sustainability. Rising conversions in beauty, fashion, and food show the model works, but questions remain on whether every category can replicate that success, or whether consumers will tire of content-heavy shopping pitches.
(Published in Exchange4Media)
admin
August 31, 2025
Akanksha Nagar, Storyboard18
31 August 2025
The latest round of US tariffs- a steep 50% duty that kicked in last week- is reshaping the playbook for Indian brands eyeing global markets. While exporters brace for tighter margins and logistical hurdles in the US, experts say this disruption could be a defining moment for Indian consumer brands to shine globally by leaning on innovation, design strength, and the untapped potential of India’s domestic consumption story.
“With the 50% tariffs kicking in, what will India do? Expect an inward-looking India! Expect a deep focus on #IndiaForIndia as marketers develop the India-consumption story for Indian produce. Expect even a Swadeshi movement Ver 3.0. MNCs in India face pressure,” says brand guru Harish Bijoor, founder of Harish Bijoor Consults Inc.
Riding high on this wave is India Circus, which is emerging as one of the fastest-growing players in the new-age home décor space. With a growing appetite for aesthetics, the brand is redefining how Indians furnish their homes. As urban consumers grow more design-aware and seek products that reflect personal taste and cultural identity, design-forward brands are carving out their own niche.
“Consumers today want more than just functionality. They want form, flair, and a sense of identity in their living spaces,” says Devangshu Dutta, founder and CEO of Third Eyesight. This shift, he explains, is creating tailwinds for brands that can deliver both design value and cultural resonance.
But he also adds a note of caution in the tariff context: “Indian brands that are being exported to the US face margin pressures and reduced US market access, both due to import tariffs and due to logistical barriers. They may need to hold inventory in the US to reduce the tariff and shipping impact, but that would also be at a certain cost and loss of agility.
It is an opportune time to focus on exports to other markets. Of course, no other single market would have the scale offered by the USA, so it will perhaps be more expensive and a more fragmented growth.”
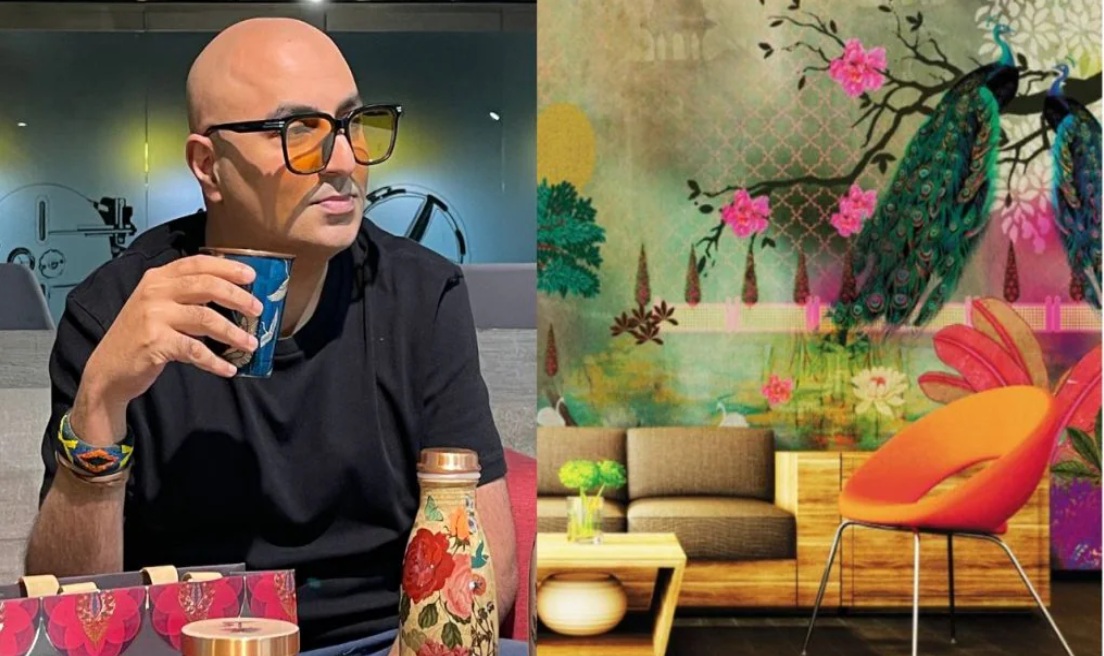
Founded by Krsnaa Mehta and now part of the Godrej Enterprises Group, India Circus has found the sweet spot between Indo-contemporary aesthetics and wide accessibility.
From crockery with 22-carat gold accents to tropical wallpapers and statement furniture, its design-led offerings have struck a chord with India’s style-conscious consumers. The brand has also forayed into fashion, while preparing to tap international markets through a new e-commerce platform. “Design is not just an add-on for us; it is our core. Every collection begins with a story, and that’s what keeps our customers coming back,” says Mehta.
On the impact of Trump’s tariffs, Mehta clarifies that the brand remains largely insulated.
“Our major consumer base is in India, we have been focused on expanding our reach and tapping unexplored markets in India. India has so much potential- the newer markets of tier-2 cities like Lucknow, Gurugram, Chandigarh, Ambala are exceptional and the buying power of our consumers has increased significantly in the past few years. So we are not really worried about the tariffs, considering that our designing, production and selling is totally in India. Yes, we do export to the US, but it is not really comparable to what we do in India.”
Yet, he views the moment as a wake-up call for Indian brands globally.
“As a proud Indian brand, we have always been at the forefront of innovation, evolving our design aesthetics from bold prints to more contemporary ones. Our consumers are now visually informed and thus we must keep evolving. It is not just moving ahead but also embracing our roots and creating what is best for not just one but for all. India Circus has always tried to democratise design, by making it affordable and providing great quality at great prices.”
India Circus’s growth is fueled by an omnichannel strategy that blends a strong digital presence with 18 (soon to be 28) offline stores, while aggressively expanding in tier-2 cities.
The brand is targeting ₹400 crore in revenue by FY2026, up from its current ₹100 crore. Having recently launched international website to serve the Middle East and Asia, tt is also exploring categories such as gifting, licensing, and royalty-based partnerships, alongside plans to scale manufacturing. Warehousing in Europe and North America is also under evaluation.
“The growing demand for sustainable, high-quality products has contributed to our growth, as consumers increasingly seek out brands that share their values. Our designers leverage consumer insights, in-house research, and sales data to create products that are both stylish and relevant. We proudly invest in Indian craftsmanship and manufacturing, eschewing imports from countries like China. This approach not only supports local economies but also enables us to maintain quality standards,” Mehta says.
Meanwhile, brands like Chumbak, who were once synonymous with playful, funky aesthetics, have had a patchier journey in the domestic market. At one point, Chumbak had drawn strong private equity interest and grew aggressively, only to later downsize and recalibrate. But Bisen cautions against equating it with India Circus: “Chumbak has always been broader in scope, and that universality may have made it less nimble when it came to capturing specific consumer segments within home decor.”
India Circus, in contrast, has stayed tightly focused, defining its identity around a clear aesthetic and target audience. This discipline, experts say, is crucial in a market that’s growing but fragmented.
“Most brands in the design-led home space operate in sub-categories. Very few cover the full décor spectrum,” Dutta notes. “The key is having a well-defined look and sticking to it.”
According to Statista, in 2025, India’s home décor market was worth $2.13 billion and is projected to grow at a CAGR of 8.6% through 2029. In comparison, the US market stands at $37 billion.
India’s growth is powered by its rising middle class, a young population hungry for differentiated products, and cultural emphasis on interior design. With gifting and new household formation boosting demand further, design-led Indian brands are positioned for deeper expansion, both at home and abroad.
For now, India Circus is leading that charge, proving that even as tariffs disrupt trade flows, Indian creativity, design, and resilience are ready to outshine globally.
(Published in Storyboard18)
