admin
October 30, 2026
Kartikay Kashyap, Financial Express
30 October 2026
Brands are ready to roll the red carpet for consumers this festive season. But for jewellery brands this Diwali will likely be a tad different from previous ones.
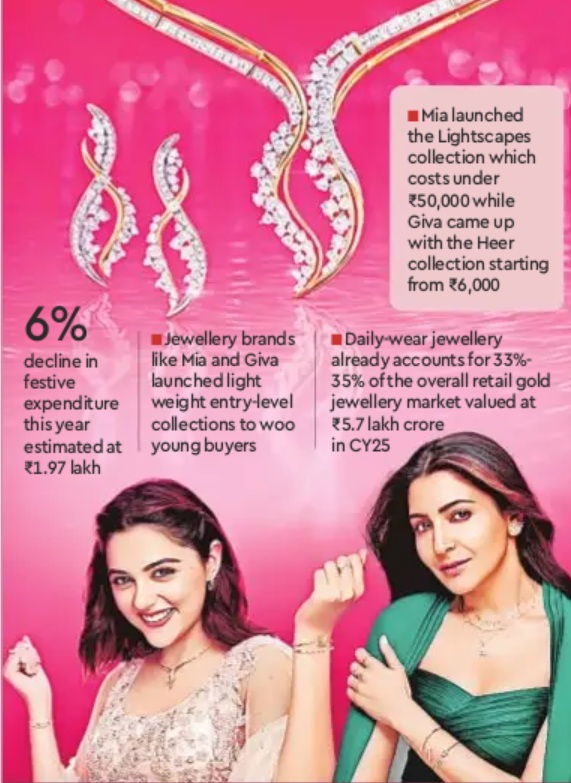
For context, consumer spending during Diwali is expected to see a decline according to Mood Of The Consumer, a survey released earlier this week by LocalCircles. On an average, urban households are looking to spend ₹20,000 in discretionary purchases this festive season, with the total spending to decline 6% from last year. The estimate puts festive expenditure at ₹1.97 lakh crores in 2026 compared with ₹2.1 lakh crores in 2025.
For jewellery brand Mia, which retails lightweight everyday jewellery, this is yet another opportunity to cast its net wider. The Titan Company-owned brand has launched Lightscapes, a new collection featuring more than 230 designs across plain gold, natural diamonds and coloured stones. The collection features a range of jhumkis, sculptural danglers, necklaces, pendants, rings and bracelets in 9KT and 14KT gold and is priced under ₹50,000 to woo first-time jewellery buyers. The supporting campaign takes forward Mia’s promise to offer women a conduit for self-expression. At the same time, the new campaign aims to push the idea of buying jewellery for festive gifting.
Mia is not the only one. Giva, which entered the gold jewellery segment during 2023 Akshay Tritiya, has introduced the Heer by Giva collection featuring polki jewellery crafted in 14 KT gold, while its Vivid Gemstone collection offers gemstone designs in 9KT and 14 КТ gold, besides a range of lab-grown diamonds. The range starts from 6,000 and goes up to ₹90,000.
The advertising pitch for jewellery brands is changing in tan-dem. If earlier they used emotion and heritage as triggers, recent advertising highlights self-expression, self-gifting and gender-neutral collections.
“The strategy to bet on affordable jewellery seems to be prompted by the surging price of gold and the hope that consumers would be keen on buying lightweight affordable jewellery this festive season,” says Devangshu Dutta, founder, Third Eyesight.
To be sure, gold prices have been volatile all of 2026. Though it has fallen more than 26% from its January record high, it is still 11.6% higher than last Diwali. For jewellery brands lightweight pieces have become the primary solution to maintaining retail volume, says Sanjeev Shukla, business advisor to fashion retailer Vinusto.in.
Lightweight jewellery has also gained traction among younger consumers in recent years. “Today’s consumers, particularly younger women, are increasingly seeking jewellery that reflects their personal style, offers versatility and fits within their budgets,” says Ajay Maurya, head of marketing & category, Mia by Tanishq. “Our focus is on making contemporary fine jewellery more accessible without compromising on design, quality or craftsmanship.”
Naresh Gupta, managing partner & chief strategy officer, Bang In The Middle, believes that younger generations especially Gen 2 buyers are drastically changing what and how they buy. Instead of heavy, occasion-led, or locker-stashed gold pieces meant strictly for weddings and festivals, they are pivoting toward lightweight, design-forward, and everyday wear. They want Indo-Western pieces that pair as well with a Diwali lehenga as they do with an office-event blazer. “The Diwali campaign strategy aligns with the jewellery retailers’ strategy to catch on the younger lot and recruit them into the ecosystem early in their stage,” says Gupta.
Daily-wear jewellery already accounts for 33%-35% of the overall retail gold jewellery market valued at 15.7 lakh crore in CY25. Organised retailers held about 37% of this market in CY25.
Apart from self-expression, light-weight jewellery also makes a good case for gifting. “Entry-level fine jewellery and budget-friendly pieces work particularly well for gifting, which makes them relevant during the festive season,” tells Disha Shah, founder, DiAi Designs.
A golden opportunity
Will Mia’s decision to take the affordability route cannibalise stable brands like Zoya and Carat Lane? If young buyers form the habit of wearing lightweight jewellery, they might do that during wedding as well, says Gupta.
One might argue that brands like Mia enable new buyers enter the fine jewellery ecosystem and move up the ladder to become the customers of brands like Tanishq and Zoya. But Vinusto’s Shukla argues repeat buying might still be a challenge for the affordable jewellery players.
For Mia, which crossed the ₹2,000-сrоге revenue milestone in the financial year 2025-26, the festive season represents a crucial window to turn up the volume. Experts say the season makes up 15-20% of the annual jewellery sales and some brands have gone on record to say they have already seen a 50% surge over pre-Diwali sales.
DiAi’s Shah remains optimistic. “We are seeing new customers explore jewellery, alongside existing customers who are looking to redesign or upgrade pieces they already own. Festive occasions provide a natural reason to enter the category, while contemporary, everyday fine jewellery can help build that relationship beyond the festive period,” she says.
(Published in Financial Express)
admin
October 19, 2026
Vaeshnavi Kasthuril, MINT
19 October 2026
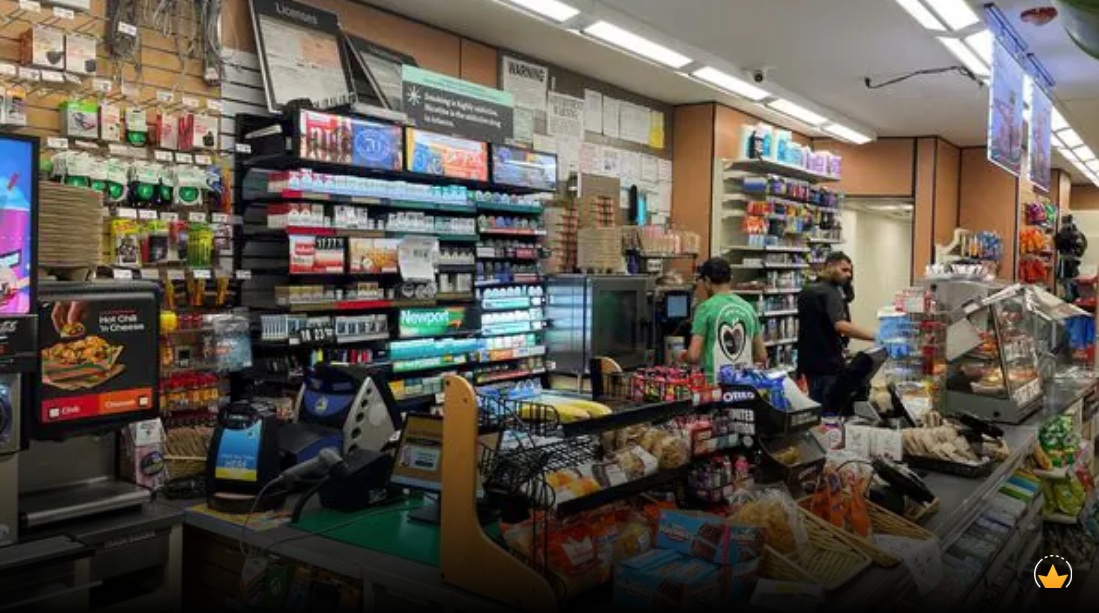
India’s quick-commerce boom is turning up the heat on grab-and-go convenience stores, leaving these chains struggling to stay relevant as doorstep deliveries become faster and easier. Caught between neighbourhood kiranas, large supermarkets and quick-commerce apps, these outlets face a tough battle for customers, with high rents and staffing costs leading to an existential squeeze.
The closure of all 31 remaining 7-Eleven stores in India on 30 September, following the end of its franchise arrangement with Reliance Retail, underscores the challenges of scaling the format. The chain entered India in 2021 and expanded to around 60 outlets at its peak. Its Japanese parent, Seven & i Holdings, said it would explore options for a long-term presence in India. The exit follows Godfrey Phillips India’s decision in April 2024 to exit its 24Seven convenience-store business.
The appeal of convenience stores lies in easy access to daily essentials, grab-and-go food and extended operating hours. But in India, kiranas and quick-commerce platforms offer many of the same products, making it harder for organized chains to justify the cost of branded outlets, staff and commercial rents.
“Convenience stores have only started really struggling after the launch of quick commerce,” said Devangshu Dutta, founder of retail consultancy Third Eyesight. Delivery platforms offer everyday products at customers’ doorsteps within minutes, reducing the need to visit a nearby store, he said.
A Redseer Strategy Consultants-Google report of 7 October found that quick commerce captures less than 5% of spending on monthly grocery stock-ups among occasional users, compared with 15-20% of spending on daily or immediate needs.
Convenience stores occupy an awkward position between large retailers and neighbourhood kiranas, Dutta said. Supermarkets can offer wider assortments and higher-margin products, while kiranas benefit from lower operating costs and can adapt quickly to local demand. Smaller outlets have limited space for products and higher operating costs per square foot than supermarkets, while average transaction values are lower.
For operators, the challenge is to find a model that can expand without allowing costs to erode margins. Aastha Alamast, co-founder of convenience-store chain The New Shop, said franchising is key to making the economics work.
“One of the key covenants of convenience retail that we know and understand is that it’s a franchise-led industry,” Alamast said. The New Shop initially ran 60-70 company-operated stores before a franchise-first model shift in 2022.
Setting up a new store costs less than ₹20 lakh, including capital expenditure and inventory, she said. The regular outlets typically span 600-800 sq. ft, while its Bengaluru flagship is about 2,000 sq. ft.
The company became profitable after opening about 110 stores and has remained profitable for three years, Alamast said. But raising capital has been difficult. Discussions with Indian venture capital firms often turned into questions about why the company wanted to franchise its stores. “Nobody really understood convenience retail,” she said, adding that the firm had raised money largely from American and Korean investors.
It is also trying to make its outlets destinations for beyond everyday shopping. “It’s a hangout spot. It’s a lifestyle store,” Alamast said. They also offer services such as courier pick-up, ticket booking and electric vehicle charging.
AMPM, another convenience-store chain, is taking a different approach after encountering problems with franchises. Founder Shubham Gupta said some franchisees skipped operating procedures, while other arrangements led to payment disputes.
“We are converting all our existing stores to company-owned, company-operated outlets only,” Gupta said. AMPM has 12 operational stores, with others under construction and more than 18 store pacts signed, he said.
The company plans to add local deliveries within 10-30 minutes once it reaches 50-100 stores. Licencing has also slowed expansion. He began researching the concept in 2012 and opened his first outlet in 2017 after working through regulatory hurdles.
Wellness Forever, a chemist chain, is betting on specialist service, rather than convenience alone. The pharmacy chain remains “pharmacy first”, said co-founder Ashraf Brian.
“Now, it is almost 60-65% would be coming from pharma. Thirty-five to 40% would be coming from non-pharma,” he said.
Quick commerce has prompted the chain to trim its food assortment after sales of products such as cold drinks, ice cream and ready-to-eat food fell. “Slowly, slowly, if you see the food items in our stores have been drastically reduced due to quick commerce,” he said.
Wellness Forever has expanded categories such as skincare, vitamins and supplements, where access to product advice can help differentiate a physical store from an online delivery platform.
Location and assortment will be critical to the format’s prospects, Dutta said. “Smaller formats can work depending on location and the kind of customers you cater to. Metro stations, for instance, are suitable for grab-and-go retail because people are in a hurry and are looking for products they can consume immediately. You have to get the assortment and location right, while keeping costs under control.”
The challenges have not deterred international players.
Japan’s Lawson plans to open five directly managed stores in Mumbai in 2027 and expand to about 100 outlets in India by 2030. This will test whether a different operating model can succeed where 7-Eleven struggled.
(Published in MINT)
admin
October 7, 2026
Vidya Sathyapriyan, ET Brand Equity
7 October 2026
Every single month, leather-goods brand Hidesign changes the storefront of its airport stores. The reason: “You can’t bore the man or woman who’s coming to the airport every week,” says founder Dilip Kapur.
But then what makes the airport shopper any different from someone walking into a high-street or mall store? Affluent? Sure. Willing to spend? Mostly. Time-poor and seeking convenience? Definitely.
That mix presents a particular challenge for brands: understanding what and why travellers will buy, and how quickly they can buy it.
Some have learnt to make the often lopsided economics work. Others are running an expensive billboard with a billing counter attached.
Crunching Numbers
The economics are punishing.
Airport rents, minimum guarantees, revenue-share, staffing and operating costs can make them significantly more expensive than conventional retail. For example, a good mall in Chennai charges roughly Rs. 350-800 per sq ft monthly in retail rent, compared with Rs. 150-200 per sq. ft. on the high street. Airport rentals can rise to as much as Rs. 6,000 per sq. ft. Similar differentials play out in other major cities.
Yet brands keep signing on because the alternative would be an advertising site with no retail attached. “A hoarding is for all and sundry and 1D,” says S. Shriram, founder of Miles2Go Consulting Services. “In the airport, captive audience, engagement is 3D and sometimes even 4D – touch and feel, trial, buy, and even return elsewhere.”
For deep-pocketed brands, spending on airport visibility can be justified even when store-level profitability is modest or even non-existent. Others gotta move on.
Go Colors, for instance, is rationalising stores at airports where the economics are not working. “The opportunity remains strong, but the location must justify the cost of access to the consumer,” says CMO Vatsal Koolwal. “As a broad benchmark, rentals in the range of 15-20% of revenue can work, provided the rest of the cost structure is managed effectively.”
The right sell
Six of Hidesign’s top-10 stores in India are at airports, says Kapur. The average Hidesign airport store generates roughly twice the turnover of an average mall store, while its smaller footprint pushes sales per square foot even higher.
A key reason is the skew in merchandise mix towards gifting.
Around 40% of the products sold in Hidesign’s airport stores are gifts. “If you have a product which can be gifted, can be purchased quickly and is work-oriented, you’ve covered most of the problematic variables.”
An overwhelming majority of domestic air travellers are men, who may not spend two hours browsing a mall, but can quickly buy a premium handbag for someone back home. Time is their scarcest resource, not money.
“Those are breaks (from routine). These are things that they would normally not have time to do,” adds Forest Essentials executive director Samrath Bedi on why premium skincare too commands attention in an airport environment.
But categories such as perfumes, cosmetics, watches, sunglasses, travel accessories and bags have an obvious advantage – they can be bought quickly and generally don’t require fitting rooms or extensive trial. As Pravat Paikray, VP-Commercial, Bangalore International Airport, says, these “one-size-fits-all” categories perform well.
Right-Sizing
Apparel, jewellery and other categories involving multiple sizes, fits or lengthy considerations have a harder job.
“Standalone apparel and niche lifestyle stores would typically be loss-making,” says founder, Third Eyesight, Devangshu Dutta.
Shriram believes even these categories are being held back by conventional merchandising assumptions. He points out that a business traveller does not necessarily need another blazer simply because they are at an airport. What they may need is a pair of track pants for an overnight trip, a gift for someone at home, or a product they discover while waiting for a flight.
For instance, Ramraj Cotton’s proposition works partly because of its local-brand resonance and partly because of its gifting-driven merchandising. “There are a lot of combos which work very well for gifting,” says Radhakrishnan. He says passengers are usually concerned about weight restrictions, so the store even repackages the items as per requirement. The brand declined Brand Equity’s interview request.
Airport merchandise can carry a 20-40% premium, he says, because the customer is paying partly for convenience. The traveller does not necessarily want to step out into the city just to save a few hundred rupees.
Front of the Queue
Paikray says Bengaluru airport explicitly designs its retail proposition around this time constraint. Brands are expected to adapt their store design, assortment, staffing, service and operations rather than simply transplanting their city format. “If a brand has 100 stores, don’t come and open 101st store in an airport, ” he says.
For Forest Essentials, what changes is also the reason the consumer is being shown the product, says Bedi. Hydration for flying, sleep on long journeys, stress relief, gifting, replenishment, etc. “It’s just about how you angle it.”
Bengaluru airport is also lowering the barriers for brands to test the market by using pop-up stores to let newer brands test travel retail without committing to long-term contracts.
Paikray says challenger and D2C brands are increasingly considering airports earlier in their expansion journeys.
But the opportunity is not on auto-pilot. Only those who adapt can turn the minutes before boarding into something more valuable than visibility – a sale.
(Published in ET Brand Equity)
admin
October 5, 2026
Sagar Malviya, Economic Times
5 October 2026
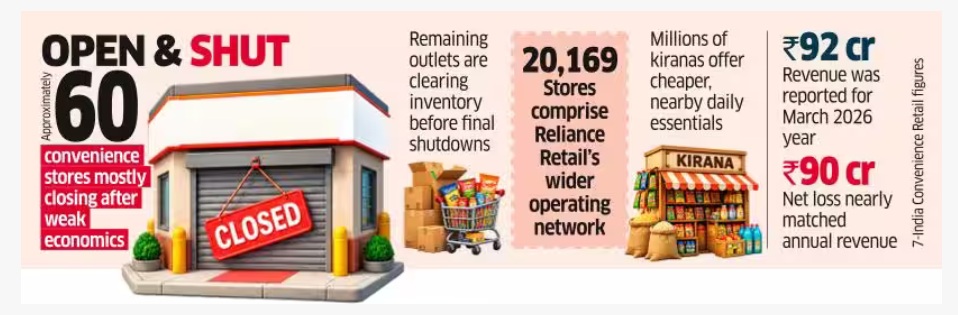
Reliance Retail and 7-Eleven are ending their five-year franchisee deal in India, closing most of the nearly 60 convenience stores they operated under the partnership, after struggling to make the format profitable, people familiar with the matter said.
A handful of outlets are clearing the inventory before shutting, they said. 7-Eleven may look for another Indian partner to keep a foothold in the market, although no decision has been made, the people said.
The exit highlights an unusual squeeze that convenience stores are facing in India, with millions of small kirana stores that have long served consumers’ immediate needs on one side and quick-commerce companies that are bringing the same snacks, groceries and daily essentials to doorsteps within minutes on the other.
Reliance and 7-Eleven did not respond to ET’s queries.
The partnership, struck in 2021, was intended to bring the world’s largest convenience-store chain to India through Reliance’s retail network. But the business struggled to achieve the scale needed to offset the relatively high costs of running branded stores.
The 7-India Convenience Retail venture reported revenue of about ₹92 crore ($10.6 million) and a net loss of nearly ₹90 crore in the year ended March 2026, according to its financial statements.
“Reliance wants to reach consumers across every channel, but sustainability ultimately matters. Convenience stores have faced increasing pressure from quick commerce since the pandemic, with both formats offering similar assortments and serving the same immediate-needs occasions,” said Devangshu Dutta, founder and CEO of Third Eyesight, a consumer-sector consultancy.
“Kiranas operate with far lower overheads and different margin expectations than corporate-run convenience stores. Reliance’s exit could therefore signal a broader rethink of the format, particularly in markets where quick commerce has become a strong alternative.”
Globally convenience stores have become powerful retail businesses in several markets despite the expansion of supermarkets and hypermarkets. 7-Eleven in Japan, Taiwan, Thailand and Singapore; Lawson in Japan and Oxxo in Mexico are among the largest retailers in their respective markets.
7-Eleven’s Japanese parent, Seven & i Holdings, operates more than 85,000 stores globally, making it one of the world’s largest retail networks. Yet the company has been restructuring its overseas operations and closing stores in North America as consumer behaviour and store economics change.
In India, however, organised convenience retail has struggled to replicate the success seen in other Asian and emerging markets. EasyDay, More and Spencer’s have either shut stores or shrank their smaller-format networks over the years, underscoring the difficulty of building profitable neighbourhood stores at scale.
Packaged consumer goods companies continue to derive roughly three-fourths of their sales from small neighbourhood stores, underlining the strength of the traditional distribution network. Quick commerce platforms are, meanwhile, expanding rapidly.
That makes it difficult for organised convenience stores to charge a premium or generate sufficient sales density to cover higher rents, staffing, inventory and logistics costs.
Convenience retail works best when operators achieve high store density and productivity, supported by strong supply chains and differentiated offerings such as fresh food and private labels.
Reliance initially expanded the 7-Eleven network in Mumbai and other markets, but the footprint remained small compared with the company’s wider retail operations.
(Published in Economic Times)
admin
September 1, 2026
Pritha Pahari, The Core
1 September 2026
Reliance has spent more than a decade bringing together a long list of names such as Burberry and Tiffany & Co. to India. Its latest focus seems to be luxury celebrity brands, adding global pop star Rihanna’s Fenty Beauty and now media personality Kim Kardashian’s shapewear label SKIMS to its luxury brands portfolio.
Isha Ambani, executive director of Reliance Retail, has fronted most of these announcements herself.
Meanwhile, Nykaa, the beauty platform Reliance Retail keeps getting compared to, spent the last year going after some of the same celebrity founders.
In August 2025, Fenty Beauty moved from Nykaa’s platform to an exclusive deal with Reliance’s Sephora India and Tira. In June 2026, Nykaa answered by signing pop star Selena Gomez’s Rare Beauty. A month later, Reliance landed SKIMS.
India’s luxury and celebrity-brand market is split between Reliance’s scale and Nykaa’s beauty expertise, with Fenty, Rare Beauty and SKIMS showing how ownership, reach and brand fit are shaping who gets the biggest names.
Big Brands, Different Bets
Reliance wins brands through scale (20,169 stores, 396 million customers) and ownership ties; Fenty’s move to Sephora India is less a market choice than an internal LVMH routing decision, given LVMH’s stakes in both Fenty and Sephora.
But Nykaa is holding its own by competing on specialism, not size; its beauty-literate audience and curated community pulled in Rare Beauty and Chanel.
The brand fit, not just distribution muscle, still decides who signs where, and some brands (like Birkenstock) skip both platforms entirely.
The economics behind these deals are harder to pin down than the headlines suggest. None of the three — Fenty, Rare Beauty, or SKIMS — have disclosed minimum guarantees, royalty rates, or sales targets for their India entries; these are announced as partnerships, not filed joint ventures.
SKIMS raised $225 million in November 2025 at a $5 billion valuation, nearing $1 billion in annual net sales.
Fenty tells a different story: $450 million in 2024 sales, now valued at $1-2 billion, down sharply from a $2.8 billion estimate in 2021, with Jay-Z’s MarcyPen Capital Partners in talks to buy LVMH’s stake.
Rare Beauty’s India entry rides on Nykaa’s own momentum; the company’s revenue from operations rose 29% year on year (YoY) to Rs 2,782 crore in Q1 FY27, up from Rs 2,154.9 crore a year earlier. In the last quarter of FY26, revenue stood at Rs 2,648.1 crore.
The Core has reached out to Reliance and Nykaa for their response, and will update this report if and when they respond.
Why Fenty Chose Reliance
Fenty’s move looks more like an internal one, according to Suumit Kapoor, a brand growth consultant.
LVMH owns 50% of Fenty Beauty through its beauty incubator Kendo Brands, a stake it has held since co-founding the brand with Rihanna in 2017. LVMH also owns Sephora globally, and Sephora in India is run by Reliance.
“When Fenty enters a new market through Sephora, LVMH is effectively distributing its own equity stake through its own global retail infrastructure,” Kapoor said. For a brand with that kind of ownership overlap, he added, the choice of partner is “close to an internal routing decision” and not a genuine trade-off.
That ownership overlap is itself now in a pickle.
LVMH has been exploring a sale of its 50% Fenty stake since October 2025, working with investment bank Evercore, according to Reuters. As of June 2026, American rapper and businessman, Jay-Z’s investment firm MarcyPen Capital Partners was reported to be among the parties in talks to buy it.
No sale has closed yet, so the Reliance-Sephora-LVMH alignment still holds for now, but it isn’t guaranteed to outlast the current ownership structure.
Fenty’s India journey backs this up. The brand’s first India listing wasn’t through Reliance at all.
It ran on Nykaa’s Cross Border Store, a low-commitment digital shelf that was discontinued before Fenty’s August 2025 relaunch, an exclusive omnichannel deal with Reliance spanning more than 50 stores across 16 cities on day one.
Kapoor doesn’t think of the switch as a deliberate strategic upgrade.
“The Cross Border Store listing may simply have underperformed on its own terms, without much marketing support behind it,” he said, adding that there is no clear evidence that Reliance stole the brand away.
Devangshu Dutta, founder of the research firm Third Eyesight, said celebrity backing only buys a brand little room.
“When a company or an investor buys into an early-stage celebrity brand, they are acquiring instant brand equity which acts as a top-of-the-funnel magnet and potentially lower CAC,” he said. “However, the ‘fame premium’ runs out if product and service execution isn’t compelling enough to drive repeat business and customer retention.”
Ownership decides the biggest deals before “competition” even enters the picture, Fenty landed at Reliance’s Sephora because LVMH owns half of each, though that alignment is shakier than it looks, with Jay-Z’s MarcyPen Capital Partners now the leading bidder for LVMH’s Fenty stake.
Beyond ownership, it’s a straight trade-off.
For brands chasing scale, Reliance’s tens of thousands of stores will get you reach. If brands want to chase community, Rare Beauty did by picking Nykaa specifically to tap its affluent, digitally engaged beauty shoppers and build loyalty. Some brands skip the fight altogether, like Birkenstock, which walked into India solo.
The Distribution Gap
Where Reliance doesn’t need an ownership story to make its case is scale. Reliance Retail closed the quarter ended June 2026 with 20,169 stores across 78.4 million square feet, 396 million registered customers, and 568 million transactions in that single quarter, up 46% year on year, according to the company’s Q1 FY27 earnings release. JioMart alone served 5,500 pincodes through its rapid delivery network in the same period.
Nykaa, by comparison, operated 324 physical stores across 105 cities as of its FY26 numbers, with a cumulative customer base of around 42 million, per its own disclosures and Business Standard’s reporting on the company’s results.
“That gap generally buys a brand not just bigger numbers, but reaches into places where a beauty specialist has no reason to be,” Kapoor said. For brands thinking beyond beauty into wellness, gifting, or lifestyle crossovers, he said that scale “is not a nice-to-have. It is the entire argument for choosing Reliance over a beauty-only platform.”
Satish Meena, founder of Datum Intelligence, a research firm, made a similar point on Reliance’s pull with brands weighing an India entry.
“With the kind of strength they have, they can always give a better deal,” he said, referring to Reliance’s ability to commit capital and guarantee scale that a newer entrant typically cannot promise on its own. He pointed to Reliance’s existing retail relationships, including Marks & Spencer, as part of the track record that makes brands comfortable signing with the group.
Experts say over the past two to three years, Nykaa has been the more prolific launch platform for major international beauty brands, while Reliance has had greater strength in international luxury and fashion.
According to experts, Nykaa reported more than 70 luxury-brand additions over the last three years, including names such as NARS, Prada Beauty, La Prairie, Chanel Beauty, Armani Beauty and Maison Margiela. Reliance, meanwhile, has built a luxury portfolio spanning Valentino, Balenciaga, Bottega Veneta, Tiffany & Co., Burberry and others, and most recently brought SKIMS to India. Reliance’s public disclosures do not provide a comparable 2–3-year count of new international brand entries.
Reliance is arguably a major gateway for international luxury/fashion, but calling it the default gateway for international brands overall is too broad.
Where Nykaa Still Wins
Reliance’s advantage on raw numbers doesn’t fully explain why Nykaa keeps landing brands too.
Nykaa built its beauty audience before it built its stores, using tutorials and curated storytelling to create what Kapoor called “a beauty-literate customer base that arrives already primed to trust the platform’s recommendations.”
That specialism is what pulled in Rare Beauty. Nykaa’s June 2026 launch made the brand available through its website, app, and 30 stores nationwide, and came from a company reporting its highest quarterly profit since listing at the time, per its own disclosures.
In a company statement announcing the launch, Anchit Nayar, Nykaa Beauty’s executive director and CEO, said the brand fit a “new generation of highly informed and globally engaged consumers seeking elevated brand experiences.” Rare Beauty’s chief executive, Scott Friedman, said in the same announcement that India was “a very important market” for the brand, citing Nykaa’s beauty community in the country as the reason to partner with it specifically.
Nykaa has run a similar playbook before. Chanel strengthened its India fragrance and beauty presence on Nykaa in 2025, Obagi Medical entered India through the platform specifically for its clinically driven skincare positioning, and Estee Lauder’s incubation arm has run its India beauty programme, Beauty and You, with Nykaa as lead partner every year since 2022.
Dutta pointed to Kay Beauty, Nykaa’s own celebrity line with actor Katrina Kaif, as an example of why platform fit matters as much as platform size. Contrasting it with 82°E, actor Deepika Padukone’s skincare brand on Tira, he said Kay Beauty had two advantages: it was priced for a much larger audience, and it had “Nykaa’s active participation across channels for merchandising and visibility.”
Not The Only Door
Reliance’s pull is real, but it isn’t the only route into India.
Reliance benefits from international-brand partnerships through retail economics, distribution and, in some cases, ownership or joint-venture economics. The potential conflict emerges because Reliance can simultaneously act as a brand’s market-entry partner and control substantial retail and digital routes to consumers. Public filings, however, do not establish that Reliance uses this position to disadvantage partner brands or competing retailers.
Meena pointed to Birkenstock, which entered by opening its own stores rather than partnering with either platform. Birkenstock and similar labels operate as single-brand retail; they can use India’s foreign direct investment rules to set up shop directly, bypassing the need for a local partner altogether.
“If the brands think that they have enough pull in the market and they can bring customers, they are opening these stores without any partnership,” Meena said. He added that most global brands take the partner route anyway because India, for many of them, is still a small share of global sales, and testing the market with an established partner for a few years is lower risk than building from scratch.
Kapoor flagged one risk worth watching no matter which partner a brand picks. Exclusive deals give a retailer more control. But Tira has also started building its own private-label products, including a colour cosmetics line, and sells them in the same stores as the global brands it distributes.
“A retailer can be a brand’s distribution partner and, on an adjacent shelf, its competitor, at the same time,” he said, a tension he noted that Nykaa’s marketplace model, without a comparable private label push against premium brands, does not carry in the same way.
For brands already tied to Reliance through ownership, like Fenty, there isn’t much of a decision to make. For everyone else, Nykaa signing Rare Beauty and Reliance signing SKIMS within weeks of each other shows this fight for celebrity founders in India is far from over.
(Published in The Core)
