admin
October 7, 2026
Vidya Sathyapriyan, ET Brand Equity
7 October 2026
Every single month, leather-goods brand Hidesign changes the storefront of its airport stores. The reason: “You can’t bore the man or woman who’s coming to the airport every week,” says founder Dilip Kapur.
But then what makes the airport shopper any different from someone walking into a high-street or mall store? Affluent? Sure. Willing to spend? Mostly. Time-poor and seeking convenience? Definitely.
That mix presents a particular challenge for brands: understanding what and why travellers will buy, and how quickly they can buy it.
Some have learnt to make the often lopsided economics work. Others are running an expensive billboard with a billing counter attached.
Crunching Numbers
The economics are punishing.
Airport rents, minimum guarantees, revenue-share, staffing and operating costs can make them significantly more expensive than conventional retail. For example, a good mall in Chennai charges roughly Rs. 350-800 per sq ft monthly in retail rent, compared with Rs. 150-200 per sq. ft. on the high street. Airport rentals can rise to as much as Rs. 6,000 per sq. ft. Similar differentials play out in other major cities.
Yet brands keep signing on because the alternative would be an advertising site with no retail attached. “A hoarding is for all and sundry and 1D,” says S. Shriram, founder of Miles2Go Consulting Services. “In the airport, captive audience, engagement is 3D and sometimes even 4D – touch and feel, trial, buy, and even return elsewhere.”
For deep-pocketed brands, spending on airport visibility can be justified even when store-level profitability is modest or even non-existent. Others gotta move on.
Go Colors, for instance, is rationalising stores at airports where the economics are not working. “The opportunity remains strong, but the location must justify the cost of access to the consumer,” says CMO Vatsal Koolwal. “As a broad benchmark, rentals in the range of 15-20% of revenue can work, provided the rest of the cost structure is managed effectively.”
The right sell
Six of Hidesign’s top-10 stores in India are at airports, says Kapur. The average Hidesign airport store generates roughly twice the turnover of an average mall store, while its smaller footprint pushes sales per square foot even higher.
A key reason is the skew in merchandise mix towards gifting.
Around 40% of the products sold in Hidesign’s airport stores are gifts. “If you have a product which can be gifted, can be purchased quickly and is work-oriented, you’ve covered most of the problematic variables.”
An overwhelming majority of domestic air travellers are men, who may not spend two hours browsing a mall, but can quickly buy a premium handbag for someone back home. Time is their scarcest resource, not money.
“Those are breaks (from routine). These are things that they would normally not have time to do,” adds Forest Essentials executive director Samrath Bedi on why premium skincare too commands attention in an airport environment.
But categories such as perfumes, cosmetics, watches, sunglasses, travel accessories and bags have an obvious advantage – they can be bought quickly and generally don’t require fitting rooms or extensive trial. As Pravat Paikray, VP-Commercial, Bangalore International Airport, says, these “one-size-fits-all” categories perform well.
Right-Sizing
Apparel, jewellery and other categories involving multiple sizes, fits or lengthy considerations have a harder job.
“Standalone apparel and niche lifestyle stores would typically be loss-making,” says founder, Third Eyesight, Devangshu Dutta.
Shriram believes even these categories are being held back by conventional merchandising assumptions. He points out that a business traveller does not necessarily need another blazer simply because they are at an airport. What they may need is a pair of track pants for an overnight trip, a gift for someone at home, or a product they discover while waiting for a flight.
For instance, Ramraj Cotton’s proposition works partly because of its local-brand resonance and partly because of its gifting-driven merchandising. “There are a lot of combos which work very well for gifting,” says Radhakrishnan. He says passengers are usually concerned about weight restrictions, so the store even repackages the items as per requirement. The brand declined Brand Equity’s interview request.
Airport merchandise can carry a 20-40% premium, he says, because the customer is paying partly for convenience. The traveller does not necessarily want to step out into the city just to save a few hundred rupees.
Front of the Queue
Paikray says Bengaluru airport explicitly designs its retail proposition around this time constraint. Brands are expected to adapt their store design, assortment, staffing, service and operations rather than simply transplanting their city format. “If a brand has 100 stores, don’t come and open 101st store in an airport, ” he says.
For Forest Essentials, what changes is also the reason the consumer is being shown the product, says Bedi. Hydration for flying, sleep on long journeys, stress relief, gifting, replenishment, etc. “It’s just about how you angle it.”
Bengaluru airport is also lowering the barriers for brands to test the market by using pop-up stores to let newer brands test travel retail without committing to long-term contracts.
Paikray says challenger and D2C brands are increasingly considering airports earlier in their expansion journeys.
But the opportunity is not on auto-pilot. Only those who adapt can turn the minutes before boarding into something more valuable than visibility – a sale.
(Published in ET Brand Equity)
admin
October 5, 2026
Sagar Malviya, Economic Times
5 October 2026
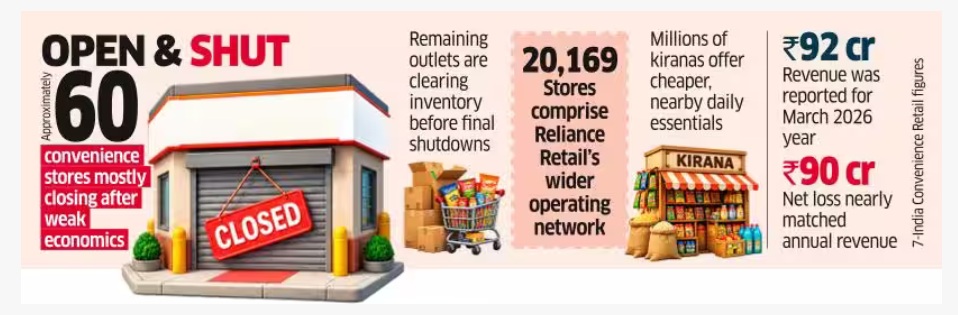
Reliance Retail and 7-Eleven are ending their five-year franchisee deal in India, closing most of the nearly 60 convenience stores they operated under the partnership, after struggling to make the format profitable, people familiar with the matter said.
A handful of outlets are clearing the inventory before shutting, they said. 7-Eleven may look for another Indian partner to keep a foothold in the market, although no decision has been made, the people said.
The exit highlights an unusual squeeze that convenience stores are facing in India, with millions of small kirana stores that have long served consumers’ immediate needs on one side and quick-commerce companies that are bringing the same snacks, groceries and daily essentials to doorsteps within minutes on the other.
Reliance and 7-Eleven did not respond to ET’s queries.
The partnership, struck in 2021, was intended to bring the world’s largest convenience-store chain to India through Reliance’s retail network. But the business struggled to achieve the scale needed to offset the relatively high costs of running branded stores.
The 7-India Convenience Retail venture reported revenue of about ₹92 crore ($10.6 million) and a net loss of nearly ₹90 crore in the year ended March 2026, according to its financial statements.
“Reliance wants to reach consumers across every channel, but sustainability ultimately matters. Convenience stores have faced increasing pressure from quick commerce since the pandemic, with both formats offering similar assortments and serving the same immediate-needs occasions,” said Devangshu Dutta, founder and CEO of Third Eyesight, a consumer-sector consultancy.
“Kiranas operate with far lower overheads and different margin expectations than corporate-run convenience stores. Reliance’s exit could therefore signal a broader rethink of the format, particularly in markets where quick commerce has become a strong alternative.”
Globally convenience stores have become powerful retail businesses in several markets despite the expansion of supermarkets and hypermarkets. 7-Eleven in Japan, Taiwan, Thailand and Singapore; Lawson in Japan and Oxxo in Mexico are among the largest retailers in their respective markets.
7-Eleven’s Japanese parent, Seven & i Holdings, operates more than 85,000 stores globally, making it one of the world’s largest retail networks. Yet the company has been restructuring its overseas operations and closing stores in North America as consumer behaviour and store economics change.
In India, however, organised convenience retail has struggled to replicate the success seen in other Asian and emerging markets. EasyDay, More and Spencer’s have either shut stores or shrank their smaller-format networks over the years, underscoring the difficulty of building profitable neighbourhood stores at scale.
Packaged consumer goods companies continue to derive roughly three-fourths of their sales from small neighbourhood stores, underlining the strength of the traditional distribution network. Quick commerce platforms are, meanwhile, expanding rapidly.
That makes it difficult for organised convenience stores to charge a premium or generate sufficient sales density to cover higher rents, staffing, inventory and logistics costs.
Convenience retail works best when operators achieve high store density and productivity, supported by strong supply chains and differentiated offerings such as fresh food and private labels.
Reliance initially expanded the 7-Eleven network in Mumbai and other markets, but the footprint remained small compared with the company’s wider retail operations.
(Published in Economic Times)
