
admin
May 12, 2026
Anushka Jha & Kausar Madhyia, Afaqs
12 May 2026
On May 10, Prime Minister Narendra Modi, in his address to the nation, made some appeals to the citizens of India. In addition to asking Indians to re-adopt Covid-like practices of working from home and refraining from travel abroad, the prime minister also appealed to the citizenry to stop buying gold for weddings for a year.
The appeals come in response to the global energy crisis and economic instability triggered by the US-Iran war and the consequent West Asia conflict, which makes import-dependent commodities like gold especially vulnerable.
The market reaction was almost immediate. Following the Prime Minister’s appeal, jewellery stocks saw sharp declines on the BSE. According to PTI, Senco Gold fell nearly 11%, Kalyan Jewellers dropped close to 10%, and Titan Company declined around 8%, while Tribhovandas Bhimji Zaveri slipped over 6%.
National interest and gold monetisation
Industry leaders have responded by balancing the Prime Minister’s vision with structural solutions.
“India’s economic strength must always come before individual preferences. Hon’ble Prime Minister’s appeal regarding responsible gold consumption reflects the larger national concern of rising imports and pressure on foreign exchange reserves,” says Rajesh Rokde, chairman of the All India Gem and Jewellery Domestic Council (GJC).
He suggests that a revitalised Gold Monetisation Scheme (GMS) could “mobilise idle household gold” and “convert dormant gold into productive national capital”.
“Nation First. Responsible Gold Ecosystem Next,” he adds.
Avinash Gupta, the vice chairman of GJC, emphasises the emotional and cultural connection of gold to Indian households.
“But today, the nation also faces the challenge of balancing gold demand with economic stability.” He believes the GMS can channel gold into the formal economy, “reducing imports, easing CAD pressure and strengthening India’s financial ecosystem.”
India’s cultural fabric and the market reality
According to a report by MoneyControl, India imports 90% of its gold needs, making the country as one of the largest gold importers globally.
Gold is an integral part of India’s cultural fabric. It is not only a fitting gift for various auspicious occasions but also constitutes one of the most expensive elements of the ‘great Indian weddings’. Additionally, there are specific religious days dedicated solely to the purchase of gold, such as Akshaya Tritiya and Dhanteras.
However, external pressures are already weighing on the market.
Devangshu Dutta, founder of Third Eyesight, a retail management consulting firm, observes: “Jewellery retailers are already suffering from higher raw material costs, and rising gold and silver prices have driven several customers to postpone or reduce their purchases, including on significant dates such as Akshaya Tritiya.”
He notes that while wedding demand may remain strong, discretionary purchases will face a setback. “Companies will need to lean into lighter, more contemporary designs and lower caratage to sustain year-round demand.”
The potential impact of the appeal
Despite rising gold prices, approximately 700 to 800 tonnes of gold are consumed every year by Indian households, weddings, festivals, investment purchases, and rural savings, as per the same Money Control report.
Given the popularity of PM Modi, industry veterans expect a tangible shift in consumer behaviour.
“There will certainly be an impact,” says Arun Iyer, founder and creative partner at Spring Marketing Capital and former chief creative officer at Lowe Lintas, who played a significant role in the creation of Tanishq and several of its iconic advertisements.
“Given that the Prime Minister obviously has a very, very deep influence on our society, I think there will be an impact. People will think twice before buying gold.”
He further notes that while critical purchases will continue, “this quarter is expected to pose some challenges for the jewellery brands”.
Adaptation and brand strategy
According to the India Brand Equity Foundation, India’s gems and jewellery market stood at Rs 7,31,255 crore in January 2025 and is projected to increase to Rs 11,18,390 crore by 2030.
To sustain this growth, players like Suvankar Sen, CEO and MD of Senco Gold Ltd, are focusing on recycling.
“Today, almost 50% of our overall business is driven through recycled gold. This not only helps consumers optimise the value of their existing gold holdings but also contributes towards reducing dependence on fresh gold imports,” he says.
From a brand perspective, Saurabh Parmar, fractional CMO, believes the strategy must shift.
“In a scenario when the head of state says something like this, the brand faces a credibility problem, not a sales problem. The play is to shift from category promotion to category trust, lean on heritage, on long-term value, and on gold’s role in Indian culture.” He advises brands not to appear opportunistic but to signal, ‘We have always been there.'”
Given the popularity of Prime Minister Modi in India, his influence is likely to affect the performance of leading jewellery brands in the next quarter. This may include major players such as Tanishq, Malabar Gold & Diamonds, and Kalyan Jewellers, among others.
(Published in Afaqs)
admin
May 9, 2026
Writankar Mukherjee, Economic Times
Kolkata, 9 May 2026
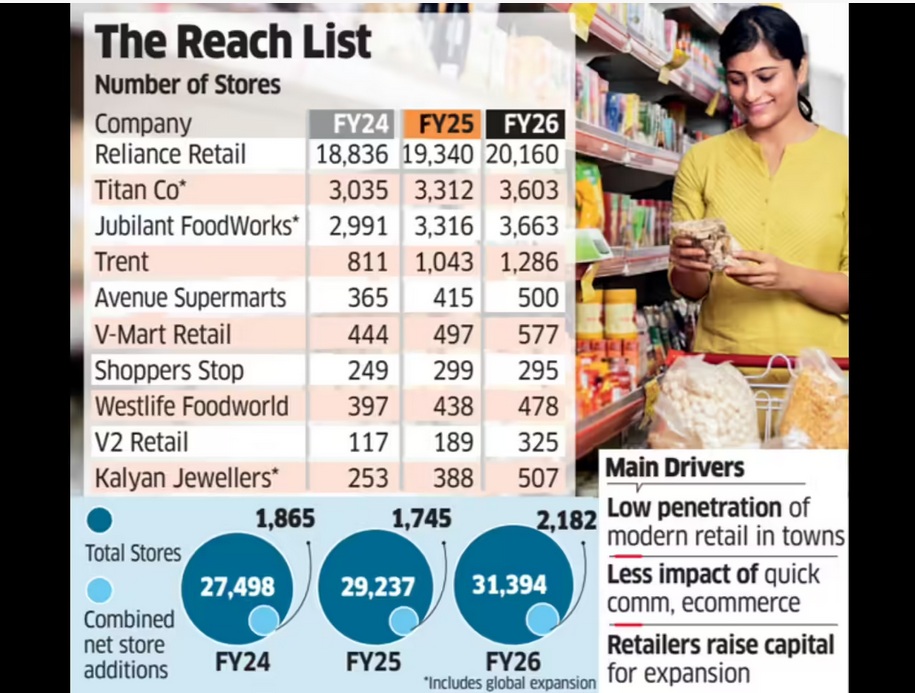
India’s top retail chains including Reliance Retail, DMart, Trent, Titan Company, Jubilant FoodWorks, and V-Mart Retail opened the highest number of stores in three years in FY26, seeking to capitalise on a demand recovery and a clean-up of unviable outlets added during the post-Covid revenge-spending period.
Entry into smaller towns and cities where many consumers continue to prefer shopping at physical stores over online is also influencing the expansion plans.
An ET study of the 10 largest listed retailers showed they added 25% more stores in the last fiscal year compared to FY25. Additions are on a net basis after accounting for loss-making outlet closures.
Collectively, the retailers added 2,182 stores in FY26, equivalent to six new stores a day on a net basis. In comparison, they added 1,745 stores in FY25 and 1,865 in FY24.
Retailers attributed the store expansion spree to improving consumer sentiment, helped further by cuts in income tax and goods and services tax (GST) rates last fiscal, along with low penetration of organised retail in smaller towns and cities. Together, the ten retailers had 31,394 stores operational as of March 2026.
Expansion Set to Continue
V-Mart Retail chief executive officer Lalit Agarwal said the ongoing shift from unorganised to organised retail is fuelling this expansion as several companies are meeting their sales growth expectations. “Many retailers have also raised capital, which they are deploying to grow topline,” he said, adding that the “growth phase will continue in the current fiscal as well.”
Companies surveyed by ET also include Shoppers Stop, Westlife Foodworld, V2 Retail and Kalyan Jewellers. Together, the ten retailers had 31,394 stores operational as of March 2026. Their combined store count grew 7% in FY26, ahead of a 6% expansion in the year before.
Reliance Retail alone added 820 net stores last fiscal, rebounding from a slowdown in FY25 when it shut several unviable outlets that were opened immediately post Covid, impacting overall industry growth rates. The country’s largest retailer had added 504 net stores in FY25, 796 in FY24, and 2,844 in FY23.
Similarly, Tata-owned Titan added 532 stores in FY23, but expansion moderated to 280-290 stores annually in FY25 and FY26.
India’s retail industry saw hyper expansion in late FY22 and FY23 as retailers sought to tap a boom in post-pandemic revenge shopping.
“Retail expansion now is more organic and measured as compared to the post Covid phase when there was a huge backlog of demand and over expansion,” said Devangshu Dutta, founder and CEO at Third Eyesight, a consultancy in consumer space.
(Published in Economic Times)
admin
March 1, 2026

Apoorva Mittal, Economic Times
1 March 2026
Resshmi Nair, 31, had grown used to the dotted red bumps on her arms. Her dermatologist diagnosed it as keratosis pilaris aka strawberry skin. It is a harmless skin condition that often affects legs and arms but Nair, a Mumbai-based marketing consultant, wanted it gone. She slathered lotions and salves but to no avail. Then she chanced upon an Instagram reel which showed an oil-based in-shower spray that promised to take care of her problem. “It was very tempting as it resonated with a personal concern,” she says. She is now on her third bottle. The bumps haven’t disappeared entirely, but they have become smaller, she says.
Like Nair, there are many who seek solutions tailormade for their beauty bugbears. Consumers who once searched for moisturisers and shampoos now look for niche products for hair and skin. They want to repair skin barrier, tame baby hairs and minimise facial pores.
A new generation of Indian beauty and personal care (BPC) brands are both listening to them and leading them. Focused products, they realise, could help them stand out in a crowded sector dominated by FMCG giants. While problems like acne, frizzy hair and rough skin have always been around, experts say the commercial importance of solving them narrowly and packaging that specificity as a brand strategy have become more intense of late.
India’s direct-to-consumer (D2C) beauty and personal care market—which is heavily invested in micro-problem targeting—is estimated to be $4.5 billion in FY2025, according to consulting firm Redseer. The new-age brands could account for 25-35% of total BPC spends by 2030. “Three major factors have contributed to this: one, the rise of digital medium for both commerce and marketing, which created a segue for new brands to launch and scale; two, younger consumers (Gen Z and young millennials) have become ingredient literate and look for results over broad promises; and three, competitive intensity in the market is pressing brands to position as per the right niches,” says Kushal Bhatnagar, associate partner, Redseer.
The shift is measurable on beauty retailer Nykaa’s platform. “Consumer vocabulary is far more evolved,” says a company spokesperson. Searches driven by specic concerns or ingredients are growing faster than broad category items. While foundational concerns like acne and brightening remain relevant, the platform is seeing strong growth in queries around pigmentation, barrier repair, pore care and specic hair issues. “This fragmentation is actually a sign of a more informed and aware consumer base,” the spokesperson adds.
ZOOMING IN
For young D2C brands, this behavioural shift has opened a narrow but potent entry point. Instead of launching another shampoo or moisturiser, they launch a product targeting a single problem and market it in an easily demonstrable short-video format. In the current beauty landscape, the market has shifted from general solutions to hyper-targeted efficacy.
Moxie Beauty, founded by Nikita Khanna in 2023, illustrates the playbook. Khanna, who previously worked at McKinsey, began with a focus on wavy and frizzy hair, a segment she herself belongs to. But it was one particular styling product, the flyaway hair stick, that went viral, propelling the brand into visibility. She says, “The wavy hair routine required us to educate people, which took time. But one can understand the flyaway wand in five seconds.” And it targeted what she calls a “widely held pain point”. That helped Moxie cut through crowded feeds and end up on consumer shelves. “Being synonymous with a category helps,” she says. “When people want a wax stick or flyaway stick, they search for our brand.”
That shift—from paying for visibility to being searched for directly—is critical in a market where customer acquisition costs (CAC) can be punishingly high. For many D2C brands, launching a sharply defined product is a way to reduce discovery friction and lower early-stage CAC. But a brand cannot be built or scaled on gimmicks, says Khanna. “If you solve only for what will look good in a video and will go viral, you won’t be able to scale. And if it’s a gimmick, people won’t repeat the purchase,” she adds.
Divanshee Jindal, cofounder of the brand The Solved Skin, says companies have to get the “product-communication fit” right. Her brand’s liquid pimple patch, which is designed to mask acne under makeup, is quickly emerging as its hero product. “People get excited when a product feels relatable and authentic,” says Jindal. “A new, convenient format that solves a real pain point makes consumers willing to try a new brand. But if it’s a standard product, say, a salicylic acid face wash, they will often default to a brand they already trust.”
SMALL IS BEAUTIFUL
The idea is to start small but evolve. Moxie, for instance, has moved beyond textured hair into solving broader “Indian hair problems” like damage repair and anti-dandruff that has brought in male consumers as well. “Curly or wavy hair was a huge, underserved problem,” says Khanna. “But the thought was always to solve other problems as well.” Moxie, which recently raised $15 million in a funding round led by Bessemer Venture Partners, says it has crossed Rs. 100 crore in annual recurring revenue on its two-year mark, and is seeing roughly 50% consumers coming back in six months across platforms. However, it says profitability is harder to crack because of intense competition from new brands and changing channel mix.
Mani Singhal, MD of the consulting firm Alvarez & Marsal, points out that most successful D2C brands started out with a sharply defined hero product. “Earlier it was natural vs chemical or price disruption; today it’s much more about efficacy proof, ingredient transparency, visible results and credible
storytelling,” she says.
From the manufacturer’s side, Nishit Dedhia of Kain Cosmeceuticals, a cosmetics manufacturing company, says, “It is easier today for brands to target special concerns. That specificity helps them build a differentiated product earlier on.” Most brands, he explains, x a major problem such as acne, dryness, pigmentation and then layer in a niche twist. Strawberry skin, once not a mainstream concern, is now a category. “People didn’t know the term. Once you give it a name, they identify with it,” he adds.
Dedhia describes the portfolio strategy as 8-2 or 9-1 where eight or nine products are general, incremental variations of core needs, while one or two are “category-building products” that require significant consumer education or product communication but create their own search demand. “That is the only way you get out of the vicious cycle of paying for visibility,” he says. “When people search for your brand directly, CAC comes down.”
Devangshu Dutta, founder of management consulting firm Third Eyesight, says micro-problem framing is “co-created” by consumers and companies. “The fragmentation is real, but the language used to describe it is heavily brand-driven,” he says. Terms like “strawberry skin” or “glass skin” correlate with influencer campaigns but label pre-existing dissatisfactions that mass products did not address sharply.
However, sometimes, in the race to differentiation, brands go for outlandish ideas. Dedhia says brands increasingly approach manufacturers with amusing asks in the quest to stand out. For instance, beard fillers packaged like mascara or plumpers for face and neck.
PRODUCE & PERISH
The problem is that the mortality rate of skincare brands is very high in India. Dedhia estimates that around 60% companies shut down in three years. Many brands burn through capital chasing ads and trends without building repeat customers or a community.
“For a brand to cross over from being a curiosity-driven purchase to being part of a regimen needs a minimum 25-30% of customers showing up as repeats after three months, while truly successful brands reach higher repeat numbers,” says Dutta.
Subscriptions are an even stronger test. “Generic formulations, me-too products and influencer spends can get you first users, but repeats will happen only from the user getting demonstrated value,” says Dutta.
But growth does not equal stability. CAC typically starts low for niche products, rises during scaling-up and stabilises only if organic demand takes over, says Bhatnagar of Redseer. Quick commerce accelerates discovery but compresses margins due to the high commission rates on these platforms, promotional expectations and lower average order values.
Singhal, who says a consolidation phase is underway, adds: “Niche entry can work extremely well if the problem is frequent enough and the solution is demonstrably effective.” Durable brands deliver consistent performance, build adjacencies beyond the first niche and maintain disciplined unit economics.
“If repeat rates don’t stabilise, economics becomes very challenging, very quickly.”
PERSONALISATION AHEAD
For Aparna Saxena, founder of Delhi-based beauty brand Antinorm, the next decade will be defined by even greater personalisation. Her brand has multifunctional products that are timesaving. Saxena says she surveyed about 250 women above 25 years of age and found that five-step routines typically do
not last after two months. Antinorm’s architecture rests on multifunctionality, like a leave-in cream that doubles as heat protectant and promises a “presentable” hair look without a blow-dry. Its most popular product is a spray that cleanses and moisturises, which they dub as “instant shower” or “facial in a flash”.
She says the brand, which launched in July last year, will close next fiscal with about Rs. 25 crore in revenue. Repeat rates are currently under 25% “because the denominator is expanding rapidly”, she adds. “Between 2020 and 2025, customers moved away from incumbents and got used to having options and trying newer brands,” she says. “Now they have routines in place. The next five years will be defined by more and more personalisation and micro-problem solving.” The beauty is about to go really skin deep.
(Published in Economic Times)
admin
February 14, 2026

This episode of theUpStreamlife is a freewheeling conversation between Vishal Krishna and Devangshu Dutta, founder of Third Eyesight, with insights into the growth of modern retail and consumption in India, brand building and M&A, the balance of power between brands and retailers/platforms, sustainability vs growth and many other aspects, and is well-suited for founders and teams who want to be building for the long run in India.
admin
February 12, 2026

Vaeshnavi Kasthuril, Mint
Bengaluru, 6 February 2026
Global fragrance maker Bath & Body Works Inc. is betting on a reset to revive growth after years of heavy discounting and weak product innovation dulled its brand momentum across markets. The Columbus, Ohio-based retailer is pivoting to a “consumer-first” formula strategy centered around upgraded formulations, more disciplined marketing, and fewer promotions.
The reset matters as India is emerging as one of the company’s fastest-growing and best-performing markets and is also becoming a testing ground for how the brand evolves its retail model. India now ranks among Bath & Body Works’ top five international markets by growth.
“We’re seeing strong engagement across stores (in India), digital marketplaces and even quick commerce, which gives us confidence as we evolve the brand and introduce more innovation,” said Tony Garrison, global vice president at Bath & Body Works, in an interview with Mint.
The fragrance maker entered India in 2018 in partnership with Dubai-based Apparel Group and has since expanded to about 50 stores across major metros, while also building an online presence through platforms such as Nykaa, Myntra, and Amazon. Apparel Group brings over 80 global brands to India, including Victoria’s Secret, Charles & Keith, Aldo, Crocs, and Tim Hortons.
“We’re learning a lot from how the Indian consumer shops across platforms, especially the speed and convenience expectations,” Garrison said. “It’s helping us think differently about assortment, pack sizes and how we show up digitally”.
Even as discretionary spending softened, the brand’s franchise partner, Apparel Group, delivered double-digit sales growth in India and high single-digit comparable store gains in FY25. It reported a 26% year-on-year jump in FY25 revenue to ₹1,118 crore and a net profit of ₹20.5 crore, reversing a loss in the previous year.
Globally, Bath & Body Works’ earnings reflect soft consumer demand as well as margin pressures. Its revenue declined 1% to $1.59 billion in the third quarter of FY25, while net income fell 27% year-on-year to $577 million.
Reviving the fragrance engine
While legacy scents such as Japanese Cherry Blossom, Champagne Toast, and Thousand Wishes remain global blockbusters, the company admits it hasn’t produced enough new hits at a similar scale in recent years. Japanese Cherry Blossom is a $250 million fragrance.
“I think we haven’t done the best job of keeping up with some of the fragrance trends. We haven’t done a lot of innovation, and that’s what you’re going to see this year. This is a big change year for us,” Garrison said.
The company plans to elevate its home fragrance portfolio, bringing in more premium candle collections, gift-ready packaging, and deeper, more sophisticated scent profiles. The broader goal is to encourage shoppers to trade up within the brand rather than wait for markdowns. “We want customers to see the value in the product itself… not just the promotion,” Garrison said.
New retail formats
To test new retail formats, the company and Apparel Group plan to pilot a small “neighbourhood store” format of roughly 500 square feet in select non-metro markets later this year. These stores will focus heavily on core body care lines and hero fragrances, while creating a more discovery-led environment for first-time shoppers.
India is also emerging as a key market in testing how far premiumisation can go. Garrison noted that the company has not seen a slowdown locally: “India has actually been one of our strongest markets in the post-Covid period. Even when consumers are careful, they still spend on small luxuries that make them feel good”.
What experts say
Retail experts caution that the reset in India won’t be without challenges. Devangshu Dutta, founder of Third Eyesight, noted that brands often fall back on discounting when volumes don’t come through. He added that the personal care market has become intensely crowded, making brand clarity critical.
While the brand is leaning into quick commerce and smaller stores, Dutta cautioned that premium brands still need larger formats to build experience-led differentiation. “Neighbourhood stores can be spokes, but you still need the hub—the large store—to communicate the brand experience,” he said.
Race Intensifies
The turnaround plan comes at a time when rivals, including The Body Shop and Forest Essentials, are also vying for the Indian consumer’s wallet. The Body Shop plans to achieve ₹1,100 crore in revenue in India within the next three to five years. India’s fragrance market was valued at $1.0 billion in 2024 and is projected to grow at a 13.9% CAGR to $3.23 billion by 2033.
(Published in Mint)
