
admin
July 13, 2026
Sowmya Ramasubramanian, Vaeshnavi Kasthuril (MINT)
Bengaluru, 13 July 2026
India’s vertical quick-commerce startups across categories like baby care, medicines and fashion, backed by venture capital heavyweights, are beginning to redefine what “quick” means.
For some, the race is no longer about cutting delivery times by a few more minutes. Instead, founders are increasingly talking about better assortment, sharper curation, stronger supply chains and healthier unit economics as the factors that will decide whether the model survives.
Baby care platform Ozi, backed by Blume Ventures and RTP Global, has settled on a roughly 60-minute delivery promise. Founder Amit Sah told Mint the company would rather optimise for “quality selection” than chase ultra-fast deliveries, arguing that customers today are looking for reliable availability and curated choices rather than insisting on receiving products in 10 minutes.
Lightspeed-backed fashion startup Slikk is pursuing a similar path. Founder Akshay Gulati said the company’s focus since inception has been building a wide catalogue rather than aggressively acquiring users.
The shift comes as the sector enters a more pragmatic phase. Quick fashion startup Blip shut down within a year of launch last June, while rival Klydo has recently pivoted its business model, raising questions about the viability of firms in every category.
The crop of vertical quick commerce startups—focused on rapid delivery within a single, specific product category—has largely emerged over the past two years, inspired by the explosive growth of grocery-focused pioneers such as Blinkit, Swiggy Instamart and IPO-bound Zepto, which have accustomed consumers to receiving groceries and everyday essentials within minutes.
Other prominent startups include Plazza for quick delivery of medicines, Instafix for mobile repairs within minutes, and Dazzl for at-home salon services.
Kalaari Capital noted in its 2025 report that quick commerce had already captured about two-thirds of online grocery orders and around 10% of India’s overall e-retail spending in 2024, transforming consumer behaviour and building the infrastructure for specialised vertical players to emerge.
“Speed was never a real moat but became a hygiene factor once every significant player could promise 10-30 minute delivery,” said Devangshu Dutta, founder and chief executive of consultancy Third Eyesight. “Assortment depth, availability, trust, and sustained price-value have been, and will remain, the true differentiation levers. For categories such as medicines and baby products, credibility and compliance outweigh saved minutes, apart from urgent purchases.”
“Unit economics can become healthier only where there’s a clear reason for frequent and repeated purchases. Groceries and medicines are repeat, low consideration categories, while fashion is high consideration, driven by fit, styling and browsing. The best quick commerce categories have low or no returns and high order frequency, whereas rapid fashion delivery faces high return rates due to product mismatch against customer expectations (sizing, fit, fabric and colour),” Dutta said.
Different categories, different playbooks
While fashion startups are investing heavily in discovery and inventory refreshes, Ozi believes the opportunity in baby care lies in curation and premiumisation.
Sah said each sub-category within baby care presents a different operational challenge. Consumables require deep availability of long-tail brands, while fashion depends on filtering products for quality rather than listing everything available. Ozi, which delivers wipes, diapers, and baby food, deliberately curates brands instead of maximising assortment, targeting parents willing to pay slightly more for trusted products.
“The customer behaviour has shifted from discovery first to search first,” Sah said, adding that shoppers today are not necessarily looking for ultra-fast delivery, but nor are they willing to wait several days. “A modern-age customer values quality. They are happy to pay an 8-10% or 12% differential, but they need quicker access to better brands and better assortment.”
Fashion startups argue that their challenge is different altogether.
Gulati said Slikk has built its business around supply rather than customer acquisition, claiming that stronger assortment has helped steadily reduce acquisition costs. The company replaces 30-40% of inventory in every dark store each month and is expanding neighbourhood by neighbourhood instead of spreading rapidly across cities.
Slikk might also consider introducing private brands for apparel, given their higher margins, Gulati said.
Bengaluru-based fast-fashion e-commerce startup Knot, which raised $5 million from 12 Flags and Kae Capital in December 2025, is investing heavily in back-end technology. Its app captures user preferences through swipe-based interactions, while its dark stores carry much wider assortments than horizontal quick commerce operators – offering a vast, multi-category collection of goods – and customise inventory based on local demand.
“We look at fashion as a data science problem and not really an intuition problem,” co-founder and chief executive officer (CEO) Archit Nanda said.
Nanda said fashion’s long-tail nature—which relies on selling small quantities of several unique products rather than depending on a few popular items – means inventory commonality across dark stores is significantly lower than grocery, requiring specialised supply chains and hyperlocal merchandising.
The profitability test
The changing strategies also reflect growing investor scrutiny of unit economics.
Slikk’s Gulati said investors continue to back the category but increasingly want proof that businesses can balance growth with profitability rather than relying on heavy customer acquisition spending. He believes execution in neighbourhood-level operations, assortment and brand partnerships will ultimately determine the winner.
Knot’s Nanda said that fashion combines high average order values with healthy margins, making the category attractive despite its complexity.
However, analysts believe that not every vertical is equally suited to the model.
“Looking ahead, horizontal cross-subsidy will work better, with established, well-capitalised players (Myntra’s M-Now, Nykaa Now) including quick delivery into an existing catalogue and logistics network rather than building it standalone. For narrow, high-trust verticals (medicines, baby care) where the value is availability and authenticity rather than impulse, and where margins can support the delivery cost, quick commerce can work,” Dutta noted.
Kalaari Capital’s 2025 report on vertical quick commerce similarly argued that specialised players will win by solving category-specific pain points, with assortment depth, customer experience, and category expertise emerging as key differentiators.
(Published in MINT)
admin
July 13, 2026
Viveat Susan Pinto, S Shanthi (Financial Express)
13 July 2026
India’s new-age coffee chains are accelerating expansion despite continuing losses, as investors bet that the country’s under-penetrated branded cafe market can deliver long-term growth.
Third Wave Coffee plans to open 100 cafes this financial year while targeting company-wide break-even. Blue Tokai aims to expand from 240 outlets to 800 by FY30 and is preparing for an eventual public listing. Nothing Before Coffee (NBC), which has grown to 114 cafes across 45 cities, plans to more than double its network over the next two years.
The expansion comes even as profitability remains elusive. Investors, however, are increasingly prioritising store-level economics over headline profits, arguing that India’s cafe market is still in its early stages of growth.
“The earlier failures in the cafe segment were largely capital-discipline failures, not failures of the category itself,” said Vish Narain, managing partner at Pulsar Capital, which is backing Blue Tokai’s international expansion.
“Chains expanded store count before proving unit economics. Investors today understand that India’s per-capita coffee consumption is still in its early stages. They are reading past shutdowns as wrong execution, not wrong thesis,” he said.
Dissecting the Balance Sheets
The numbers highlight the challenge.
Heissette Beverages, the parent of Third Wave Coffee, accumulated losses of Rs 320 crore between FY21 and FY25, while total assets stood at Rs 538 crore at the end of FY25, according to Tracxn. Muhavra Enterprises, Blue Tokai’s parent, reported accumulated losses of Rs 175 crore over the same period, with total assets of nearly Rs 370 crore. Financials for FY26 are not yet available with Tracxn.
NBC accumulated losses of nearly Rs 3 crore over FY24 and FY25 against total assets of Rs 18 crore. Mumbai-based premium chain Subko Coffee, with 16 outlets in India and one in Dubai, posted losses of Rs 45 crore over five years, while total assets stood at Rs 61 crore at the end of FY25.
Third Wave Coffee said around 90% of its outlets are Ebitda-positive and expects to achieve company-wide break-even during FY27. Blue Tokai, backed by Verlinvest, is targeting profitability by March 2028.
NBC declined to specify a profitability timeline but said it has adopted a franchisee-invested, company-operated (FICO) model to reduce cash burn while retaining operational control.
“FICO lets us expand quickly with franchisee capital while keeping operational control,” said Ankesh Jain, co-founder and chief executive officer, Nothing Before Coffee.
Structural Shifts
Experts attribute the investor interest partly to improving outlet economics as operators shift from large dine-in formats to compact grab-and-go and cloud-kitchen models.
“These formats materially cut capex per outlet and shrink payback timelines, making the category venture-fundable rather than just a slow-and-steady, self-funded business,” said Krishna Dev Pathak, investment banker and advisor to early-stage startups.
Lower capital requirements have strengthened unit economics, reinforcing investor confidence despite delayed company-level profitability.
Investors are also betting on a broader shift in consumer behaviour. Anuj Kejriwal, chief executive officer and managing director of Anarock Retail, said rising incomes, urbanisation and changing preferences are gradually moving India from “a tea economy to a coffee economy”. The shift is widening the addressable market for organised coffee chains beyond the metros into smaller cities.
Consumers increasingly use cafes as workspaces, meeting points and all-day dining destinations, prompting chains to diversify into food, desserts, packaged coffee, vending solutions and merchandise.
“The cafe model is now well established as part of consumers’ lifestyles,” said Devangshu Dutta, founder and chief executive of retail consultancy Third Eyesight.
Challenges remain. Rentals in premium locations have surged, coffee prices remain volatile, and labour and supply-chain costs continue to pressure margins.
For now, investors appear willing to fund rapid expansion, betting that disciplined execution and improving unit economics will eventually turn India’s cafe boom into a profitable business.
(Published in Financial Express)
admin
July 12, 2026
Nivedita Mookerji, Business Standard
12 Jul 2026
Recently, fast moving consumer goods distributors posed some existential questions to the government: Have the rules changed for foreign-owned ecommerce firms? With that, the All India Consumer Products Distribution Federation made a plea to the government to examine if foreign-funded ecommerce and quick commerce players can run inventory-led businesses through warehouses and dark stores.
The question mark is around the operating model of the big daddies of retail — both from America — under the current foreign direct investment (FDI) guidelines. One of them is Bentonville-headquartered Walmart, which holds a controlling stake in e-commerce major Flipkart. And the other is Seattle-based Amazon. Both Flipkart and Amazon are upping their quick commerce play, a development that the Indian retail ecosystem players fear would hit them hard.
For context, foreign e-commerce companies are allowed to do business through the marketplace model as opposed to the inventory-led format. Marketplace operators such as Amazon and Flipkart (Walmart) are permitted to have sellers on their platforms and those sellers own the goods (inventory) which are sold to customers. Indian companies in the e-commerce business can own the goods and sell them directly to the consumers.
This is not the first time that there’s noise around the business practices of foreign majors and their alleged violations of the rulebook in relation to anything from the legality of the operating model to predatory pricing and deep discounting. The protests of the domestic traders against foreign players — that started decades ago with an agitation against the government’s multi-brand retail policy — have resulted in a series of amendments in the FDI rules, intervention of the competition watchdog CCI (Competition Commission of India), Supreme Court observations, making of laws and keeping them in abeyance. But, the complaints — from different quarters of the domestic business — have remained.
Devangshu Dutta, founder and CEO of consulting firm Third Eyesight, argued that since 1996-97, when foreign investment in retail was first banned, governments of different political hues have been walking the regulatory tightrope with respect to foreign investment in retail, whether offline or online. “The government’s caution on retail policy was aimed at protecting domestic interests, though it is arguable whether it was for the small retailer, or the larger corporates who had identified this as a growth sector at the time,’’ Dutta said.
(Published in Business Standard)
admin
June 30, 2026
Vaeshnavi Kasthuril, MINT
30 June 2026, Mumbai
Advent International-backed Modenik Lifestyle Pvt. Ltd is doubling down on its portfolio of legacy innerwear brands, planning to scale each label into a sizeable business rather than rely on a single flagship brand.
“Each of the brands must grow big enough to be called a company of its own,” Shekhar Tewari, chief executive and executive director, told Mint.
The company has four brands: premium women’s innerwear label Enamor, value brand Slimz, mass-premium men’s label Dixcy Scott, and premium men’s innerwear brand Levi’s. “These brands are very strong in their respective segments. They complement each other rather than compete,” Tewari said.
Levi’s Innerwear is priced between ₹250 and ₹550, Dixcy Scott and Slimz between ₹100 and ₹350, while Enamor’s products start at ₹500 and go beyond ₹2,500.
The strategy comes as India’s innerwear market, particularly women’s lingerie, has become one of the country’s most fiercely contested apparel categories, with established retailers and digital-first brands vying for market share.
Modenik’s focus on innerwear deepened after private equity firm Advent brought Enamor and Dixcy together under Modenik Lifestyle, following its acquisition of Enamor from Gokaldas Exports in 2019.
Both brands had expanded into adjacent categories such as athleisure, loungewear, sleepwear and outerwear, but struggled to keep pace with rising competition from fashion retailers and digital-first brands. The company has since exited much of its outerwear portfolio, taking a revenue hit.
“We took a conscious hit on the top line because we wanted to become a focused innerwear company,” Tewari said. “If you’re trying to be everything to everyone, you end up not being known for anything. We wanted consumers to think of us first when they think of innerwear.”
Revenue has remained largely flat at around ₹1,200 crore over the past three years, though losses have narrowed sharply. FY25 revenue stood at ₹1,224 crore, while net loss halved to ₹24.8 crore from ₹50.8 crore a year earlier.
Modenik aims to outpace the industry’s single-digit growth by increasing branded penetration in women’s innerwear, expanding its premium portfolio and adding exclusive store network, expected to cross 100 outlets in the near term.
The company sees significant headroom in women’s innerwear, where it estimates the market at more than ₹20,000 crore, but organised brands account for only ₹3,000-4,000 crore. It expects formalization, premiumization and product innovation to accelerate brand adoption.
According to Devangshu Dutta, chief executive of retail consultancy Third Eyesight, the market’s increasing fragmentation makes a multi-brand strategy more effective.
“You can’t have one brand stretching across multiple segments. The product has to be different, pricing strategies are different, the messaging and the distribution channel mix also varies depending on the consumer segment you’re trying to target,” he said.
According to industry estimates, India’s innerwear market is valued at over ₹90,000 crore (about $10.9 billion) and is expected to grow at a 6-7% compound annual growth rate (CAGR) over the next decade.
Advantages and avenues
Tewari believes Modenik has structural advantages over many digital-first rivals. Unlike online-first brands that typically outsource manufacturing, the company controls product development and manufacturing while leveraging decades-old relationships with distributors, department stores, exclusive brand outlets and multi-brand retailers.
“Those capabilities have been built over decades. They cannot be replicated overnight,” he said.
The company is also expanding across channels. Enamor is available through 6,000-7,000 multi-brand outlets, nearly 80 exclusive stores, department stores, including Shoppers Stop, Lifestyle, Central and Pantaloons, besides online marketplaces and quick commerce platforms. E-commerce contributes over 30% of Enamor’s revenue.
Although digital commerce is growing rapidly, Tewari believes physical retail will continue to play a critical role in the category.
“Innerwear is a category that requires understanding of fit, size and functionality. Consumers still want to touch, feel and try products before making the switch from unbranded to branded,” he said.
Rather than pursuing acquisitions, the company plans to unlock growth from its existing portfolio.
The strategy comes as competition in India’s innerwear market is intensifying. Page Industries dominates through Jockey, while Reliance Retail, which houses brands such as Clovia, Marks & Spencer and Hunkemöller, acquired digital-first lingerie platform Zivame, and added premium lingerie brand amanté. Aditya Birla Fashion and Retail has expanded Van Heusen Innerwear, while Trent has strengthened its innerwear offering through its private label brands at Westside and Zudio. New-age brands such as Shyaway, Bummer and Nykd by Nykaa have also stepped up investments in their products.
(Published in MINT)
admin
June 12, 2026
Christina Moniz, Financial Express/Brand Wagon
12 June 2026
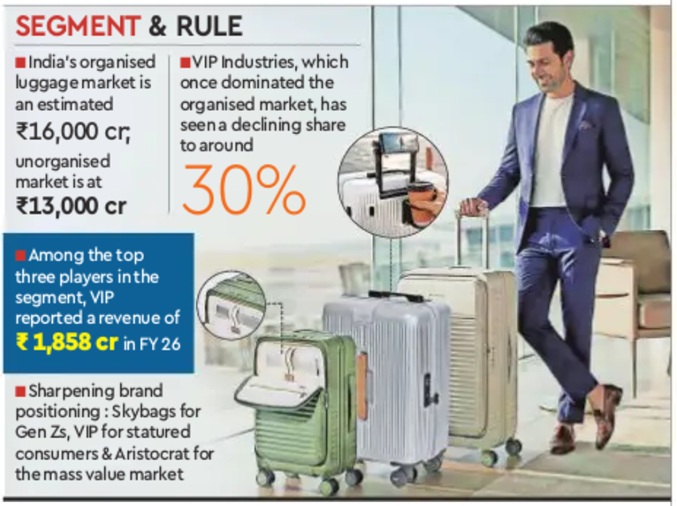
Legacy luggage brand VIP Industries is shedding some of its old baggage. The company, which manufactures Skybags and Aristocrat along with its flagship VIP range, has gone beyond cringey makeovers solely to attract Gen Z, and has embarked on a transformation journey that leverages its legacy to purvey a fresh range of offerings.
The company is modernising its digital presence and supply chain to catch up with competitors.
Managing director Atul Jain admits that the company has been a bit slow on the e-commerce front. It is reinventing its online store, while also making its products available across other e-commerce channels. “Quick commerce is becoming an important channel since there are several use occasions and segments within the luggage market. For instance, consumers often make last-minute purchases for a weekend trip via quick commerce. School bags and backpacks for kids, also great gifting options, are seeing good demand on these platforms,” he says
The company, which once dominated the ₹16,000 crore organised luggage market in India, saw a bit of a shakeup last year when the Piramal family sold 32% of its stake to a private equity firm. But it continues to be among the top three players in the category with a 29-30% market share. “Luggage plays the role of a traveller’s companion. We are creating designs to fit that role,” says Jain. “For example, our new VIP suitcases have a coffee cup holder and our cabin trolley bag has an easy access compartment for devices like laptops and iPads.”
The transformation goes beyond the product. VIP’s 350 exclusive physical retail touchpoints in the country are being revamped to offer a new customer experience.
Unpacking opportunities
Overits 55 years, VIP has grown from a briefcase brand into Asia’s largest luggage maker, housing labels like Skybags, Aristocrat, and Carlton (premium segment). While VIP is a premium offering targeted at business and travellers, its Aristocrat brand operates in the mass market and the budget-friendly Alfa targets consumers who typically shop in the unbranded segment. Aristocrat and Alfa together contributed upwards of 40% to the company’s revenue in FY25, followed by Skybags (28%) and VIP (20%).
Like many legacy brands, the VIP Industries’ faces the challenge to ia, stay relevant among Gen Z buyers as a plethora of digital-first brands swamp the market. “VIP has lost ground on relevance and desirability to a generation for whom luggage, like sneakers, is an expression of identity. To them, VIP feels like their parents’ brand,” says Nisha Sampath, managing partner, Bright Angles Consulting. D2C players in the category operate in the business of “lifestyle accessories” and not for “luggage” per se, she points out.
With a design-forward approach, incorporating features like compression systems, silent wheels and charging ports, these new-age brands have embedded themselves in travel “culture”, while also being Instagram worthy, say experts.
Jain says Skybags is VIP’s Gen Z focussed brand, which has over 8,20,000 Instagram followers. “We are sharpening our positioning for Skybags in our design, advertising and marketing outreach, especially on social platforms. The brand has a clear differentiation with youthful colours and prints to attract younger consumers,” he adds.
While D2C players have seen notable growth in recent years, they don’t have the kind of trust and brand equity that VIP has cultivated across its brands, nor do they have the scale or revenue that legacy brands have, he says.
Experts believe there is a significant growth opportunity for legacy players given that the unbranded market still accounts for ₹13,000-14,000 crore. The important lever for legacy brands is to clearly demonstrate value beyond price. “The unorganised market competes heavily on affordability, so organised players need to communicate durability, warranty, after-sales service, and consistent quality – areas where they have a strong inherent advantage over unorganised alternatives,” says Praveen Govindu, partner at Deloitte India. He adds that these brands should also invest in advertising and communicate this value to the end consumer.
Not only are the needs different among different consumer groups, competitive pressures are also diverse. “VIP can segment the market more cleanly with its portfolio of brands if it maintains absolute distinction to ensure clear consumer targeting across not just product attributes and pricing, but also communication and channels,” says Devangshu Dutta, CEO, Third Eyesight.
(Published in Financial Express)
