
admin
August 1, 2026
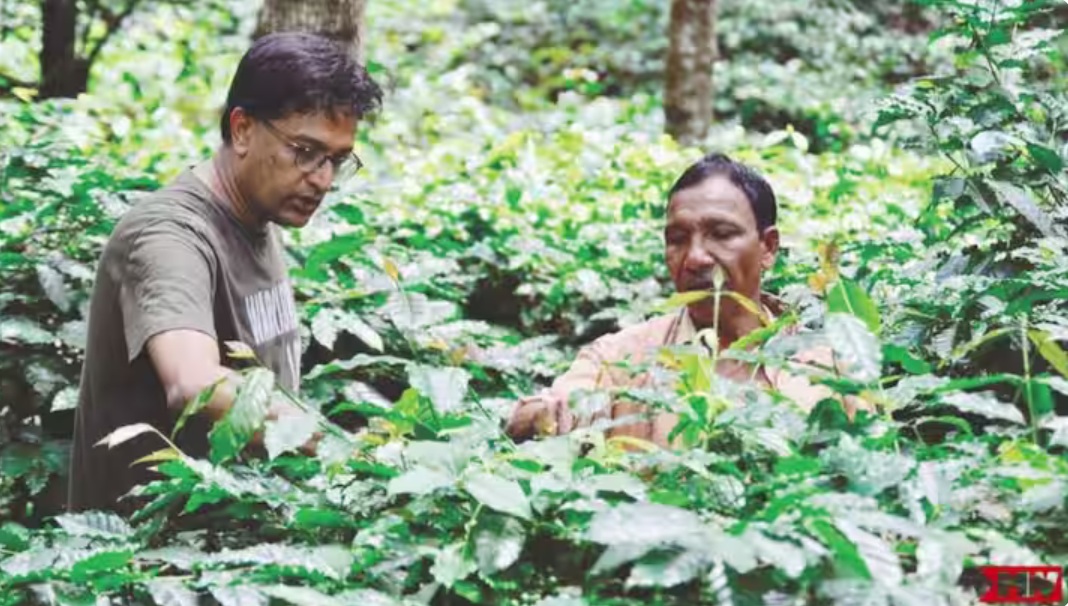
Murali K Menon, Firstpost
1 August 2026
The next time you are shopping for veggies on a quick commerce app, we’d suggest you hop onto the organic produce section and consider where those vegetables came from. Chances are, they have travelled through a supply chain pretty different from the one that bought veggies to your kitchen just five years ago. Some of that produce is supplied by Urban Farms Co., a little-known company that is rethinking food systems.
Urban Farms works with about 2,000 small farmers on the outskirts of several of India’s cities, as well as in states like Rajasthan and Maharashtra to grow vegetables using regenerative practices and supplies them to urban consumers via quick commerce and modern retail. The definition of renegenrative agriculture changes depending on who you ask, but broadly it refers to an approach that seeks to restore soil health, as opposed to conventional, chemical-intensive farming.
About 1% of global farmland is now under regenerative practices, according to a 2025 World Resources Institute study. Urban Farms, whose farmer network grows over 50 varieties of vegetables, handles around 12,000 tonnes annually and is targeting a twenty-fold jump in revenue from its current Rs 30 crore in the next five years.
That target might sound ambitious until you look at its origins. Urban Farms was founded by members of the team behind Araku Coffee, the specialty coffee brand that put Indian coffee on the global map. Both Araku Coffee and Urban Farms are backed by the Hyderabad-based Naandi Foundation, among the country’s largest, multi-sector non-profits. The NGO was set up by Dr. Reddy’s Laboratories founder, the late Kallam Anji Reddy, and counts Kris Gopalakrishnan and Anand Mahindra on its board.
The broad details of Araku Coffee’s success are well known, but the model that underpins it is much less discussed. Over two decades, the project worked with thousands of tribal farmers to promote regenerative farming practices, restore degraded land, and improve farmer incomes while building a globally recognised premium coffee brand. The same spirit animates Urban Farms. Instead of tribal farmers, it works with small farmers on the outskirts of India’s cities. Instead of a premium export crop, it is betting on everyday vegetables sold through quick commerce and modern retail. But can a model proven in a premium niche survive in the toughest, most commoditised part of Indian agriculture?
Beyond coffee
Coffee was just a conversation-starter, says Manoj Kumar, the lead architect of the Araku Coffee project and the founding CEO of the Naandi Foundation. The developmental economist says that the project proved two things. “It proved at scale that our regenerative organic agricultural science worked for 20 years in every crop, from coffee to millet, consistently season after season, without any drop in yield. And, just as importantly, that we could do world-class excellence at scale with very ordinary poor people.”
The eventual goal was improving farmer economics. “In India, 85% of farmers have less than one hectare of land,” Kumar says. “The question is: what do we do with small and marginal farmers?” Urban Farms is one answer to that question. Unlike Araku Coffee, though, it isn’t built around a single crop.
“Urban Farms is about doing a system change. We are changing food systems,” says Vikash Abraham, the company’s CEO. So, what does that mean for something as everyday as a lady finger? Before it reaches your kitchen, Urban Farms is involved in almost every stage of its journey. It supplies regenerative fertilisers to farmers, works with them through the growing season, buys back their produce, and sells it to retailers and quick commerce platforms.
Urban Farms
“We procure from the farmer at the same price as conventional produce. We do not pay a premium per kilogram because we believe profitability is about cost of cultivation versus the entire income you get from your farm,” Abraham says. In other words, with Urban Farms, farmers don’t earn more because they sell lady finger at a higher price. They earn more because regenerative farming lowers their costs while giving them an assured buyer. A typical vegetable grower could earn as much as Rs 20,000 to Rs 30,000 more per acre annually, says Abraham, with savings increasing over time. A first-season comparison conducted by the company across 56.5 acres in Wardha, Maharashtra, found that soybean yields rose 12% and total cultivation costs fell by 8%.
Spending on farm inputs dipped from ₹9,750 to ₹5,267 per acre, while profits increased from ₹12,550 to ₹19,195. The model does not rely on government subsidies and farmers pay for the inputs themselves. According to Abraham, Urban Farms doesn’t approach farmers from a moral standpoint, or talk about climate change. “We go to them with a business proposition, and the business proposition is about making profitability.”
From trial to habit
Urban Farms’ residue-free vegetables generally cost about 40% more than conventional produce, although the gap varies by crop, market prices, and platforms. Lady finger, for instance, was priced at ₹24 for a 250gm pack on Zepto in Azadpur, in north Delhi, earlier this week compared with ₹17 for conventional produce; on Blinkit, the same pack was sold at ₹35.
Quick commerce accounts for 65% of its business under the residue-free category, with modern trade and other channels making up the rest. Abraham says part of that premium reflects the cost of maintaining a separate, traceable supply chain. The company supplies Blinkit, Zepto, Swiggy, and Flipkart as well as Reliance, Jubilant, and Country Delight, among others.
Devangshu Dutta, founder of retail consultancy Third Eyesight, says that he expects demand to grow, as incomes rise and consumers become more conscious of the food they are eating. But he thinks a 40% premium may be too high for regular consumption because vegetables, unlike coffee or craft chocolate, are staples.
“You could have a premium of maybe 20% to 30%. Some products could be higher than that, but that is something that has to be managed carefully.” For category growth to accelerate, he says, the produce must become “a fixture in the consumer’s pantry, in the consumer’s kitchen, on the consumer’s plate.”
Dutta believes that quick commerce is well-suited to fresh produce because Indian households have traditionally bought vegetables frequently rather than stocking up. “The bottleneck really is having the product range that consumers will buy over a period of time again and again.” That requires farmers growing different crops across regions and climatic zones. And building a wide range of vegetables also means working with farmers and ensuring farmer retention in the system season after season. “You don’t just sign up a farmer and say he’s going to be there forever,” Dutta says.
Urban Farms says it has managed to do that so far. In May this year, Anand Mahindra posted on X that 80 to 90% of the farmers who work with the company return every season. “Not out of loyalty to a movement, but because the economics work,” he wrote, pointing to yields comparable with conventional farming, lower input costs and produce that consistently tests residue-free.
Abraham says that Urban Farms would like to work with about 100,000 farmers by 2030, and the company’s growth will depend on how quickly it can both build and nurture relationships with its partners across the country. Applying the Araku model to a far more unpredictable market won’t be easy, but if Urban Farms can keep both farmers and shoppers in the system as it grows, coffee, as Manoj Kumar said, may indeed have been just the conversation-starter.
(Published in Firstpost)
admin
August 1, 2026
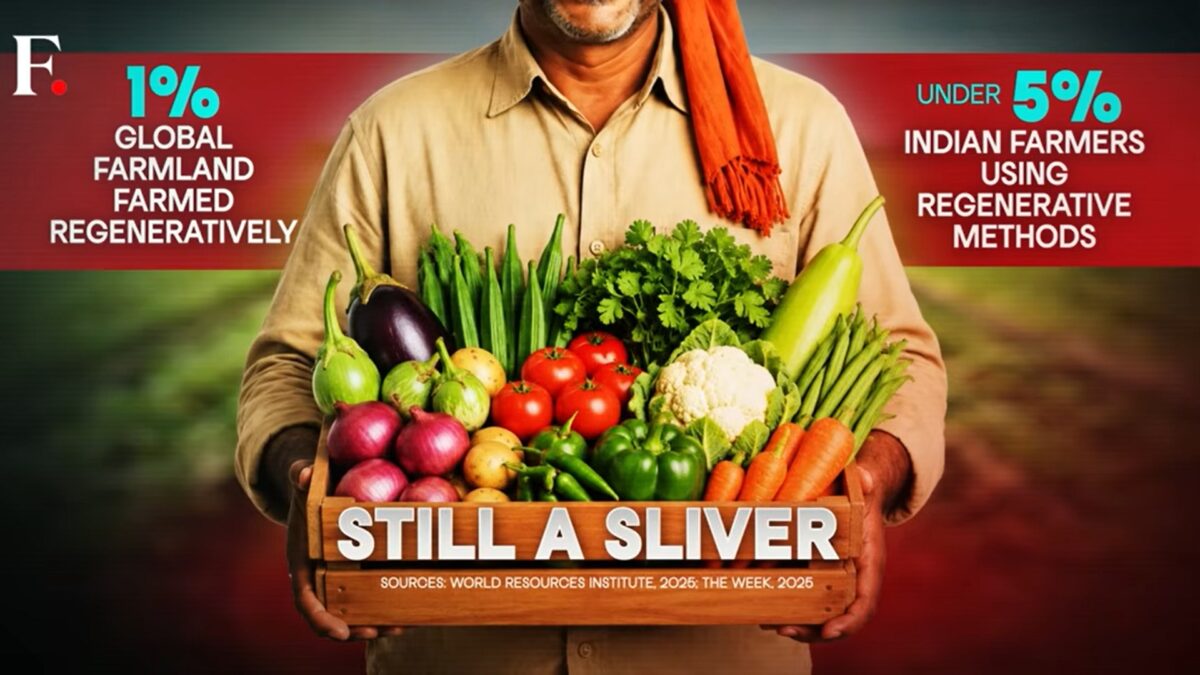
Two decades ago, the team at the Naandi Foundation turned tribal farmers in a remote Andhra valley into some of the world’s best-paid coffee growers. Araku Coffee now sells in Paris, and the best of it goes for thousands of rupees a kilogram. Now the same team is trying to do it again — this time with everyday vegetables. Their company, Urban Farms Co., works with regenerative farmers and sells their produce on apps like Blinkit and Zepto. The bet is that what worked for premium coffee can work for staples too. But vegetables aren’t coffee. They’re cheap, everyday, and something people buy all the time. Can this really scale, and does it actually leave farmers better off?
admin
September 7, 2016
Horticulture production in India has been surpassing the production of food grains for many years. In 2014-15, the total production of horticultural produce was estimated by the Department of Agriculture, Cooperation and Farmers Welfare, Ministry of Agriculture to be approximately 281 million tonnes as against 252 million tonnes of food grain production and 275 million tonnes of oilseeds.
Horticulture and floriculture have result in growing foreign earnings, and India’s domestic market is also growing. In fact the demand for many types of vegetables and fruits which are not native to India such as lettuce, broccoli, gherkins, as well as for exotic flowers such as orchids, gerberas, carnations, is soaring. These crops were initially being cultivated only for export, but are now being bought by the urban population within India as well, as a result of growing familiarity with other cultures, and shifts in cuisines and lifestyles.
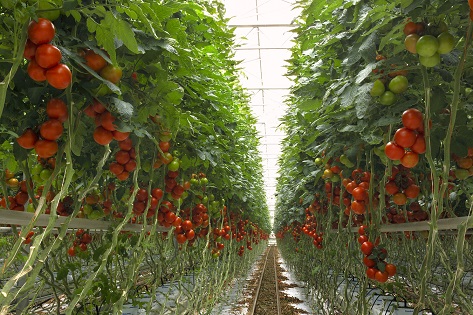
Many of these crops require specific climatic conditions which are not available in all parts of India, hence, cultivating them in controlled environments is a preferred option. Other than providing them a hospitable environment, the yield of the crop can be significantly better and availability can be all-year round, providing better market prices in the off-season. Greenhouses can be used by farmers for years to grow and sell exotic vegetables and other high-value commodities. Moreover, greenhouses help reduce the expenditure on pesticides by warding off insects and pests, many of which are carriers of viral and other infections. There is, therefore, considerable merit to extending the area under this system of cultivation, for the benefit of both producers and consumers.
While greenhouses have existed for more than one and a half centuries in various parts of the world, in India use of greenhouse technology started only during 1980’s and it was mainly used for research activities. The commercial utilization of greenhouses started from the late-1980s and with the introduction of the Government’s liberalization policies and development initiatives, several businesses were set up as 100 per cent export oriented units. Now many progressive farming organisations and individual farmers are using varied levels of technology in order to control the environment in which agriculture is done.
Although, there is an upfront capital cost involved in the setting up of a greenhouse, the scale of the greenhouse and proper management helps in yielding viable results. Most of the greenhouse projects in India at this point of time are on landholdings of up to 1 acre. However interest is seen to be growing towards projects of larger landholdings. Capital costs per acre range from Rs. 15 lakhs for a basic green house with simple techniques to control temperature and humidity, to Rs. 1.5 crore for automated greenhouses with superior humidity and temperature control, more closely managed water and nutrient dispersal etc.
Protected cultivation is one the important interventions of the National Horticulture Mission. Various patterns of assistance in the form of subsidies (ranging up to 50% of the cost of setting up the structures) have been devised by the government to encourage farmers to engage with this form of cultivation.
To encourage cultivation of vegetables under controlled atmosphere, Punjab government has empanelled five firms to assist farmers to set up polyhouses and polynet houses in their fields. The state government will provide subsidy on the greenhouse structures erected by these firms.
In Khammam, Telangana, the Horticulture Department is readying two poly-house demonstration units to popularise greenhouse technology and help farmers take up cultivation of high yielding vegetables round the year under controlled weather conditions.
Projects have already been taken up in Telangana, Gujarat and Himachal Pradesh ranging from feasibility studies of green house facilities and distribution halls for grading, sorting and packing to designing and setting up of green houses for breeding of rice and other crops and cultivation of tomatoes, strawberries, capsicum, cucumbers and lettuce.
For higher end, larger scale farms, Indian growers are also exploring technology from Europe. For instance, the Netherlands is the traditional exporter of greenhouse grown flowers and vegetables all over the world. The Dutch greenhouse industry is one of the most advanced in the world, and has now also become a provider of technology and support for the development of greenhouse cultivation around the world. Advanced technology solutions include climate sensors, air treatment devices, and software support.
However, success doesn’t only depend on equipment. Organisations such as Koppert provide biological solutions for natural pest control, natural pollination and seed treatment, to not only improve the quality and yield of the produce, but also make it safer.
There are many Indian as well as international organisations providing greenhouse solutions ranging from materials, technology and project consultancy. In the coming years it is expected that India’s rich agricultural, horticultural and relatively newer floricultural expertise will get enhanced and further competitive with the adoption of greenhouse cultivation to feed the burgeoning global and domestic demand.
Devangshu Dutta
October 25, 2014

These are thoughts shared in an emailed interview with the AgriBusiness and Food Industry magazine (published in the November 2014 issue.)
A Perspective on the Indian market:
Our first word of advice to companies that are looking at India as an evolving and large market, is to acknowledge the fact that that it has very diverse cuisines and food cultures.
Both Indian and international companies wishing to enter this market for the first time need to understand and acknowledge that one-size certainly does not fit everyone.
The variety of finished products needed requires food companies to address smaller quantities and to have flexible production.
Therefore, suppliers of capital equipment and technology also need to be able to think about how they can make their solutions more flexible to adapt to changing market needs, and also to price them appropriately for the Indian market. Simply extending solutions that work in large, developed markets such as Western Europe and North America is not the best approach.
I would use the example of one of our clients, a manufacturer of bakery automation equipment, who have approached the market with an open mind. After initial investigations they have gone back to the drawing board and created production lines that have smaller capacity, can produce multiple products including Indian specialities, and which are techno-commercially more feasible for an Indian customer to adopt.
There is no reason to think that India’s food industry should follow exactly the same development curve as the west. The population is much larger, with significantly lower income, and needs that are far more diverse and changing far more rapidly than in most other economies. The technical and technological models for India need to be strongly focussed on four major attributes:
Agricultural, horticultural and animal husbandry practices and technologies, as well as those in the downstream sectors such as food processing, need to perhaps even look at setting new benchmarks for accessibility and long-term sustainability.
Food processing and the Indian consumer market:
Food processing has been part of human history since we learned to transform hunted, gathered and farmed raw products into new foods through curing, cooking, culturing etc. This processing has been driven by mainly two major factors: to make the raw material into a product that is more palatable and easily consumed (for example, from raw grains to bread), or to extend the storage life of the raw material (for example, in the form of cheese, pickles, or sweets, or using cooling and freezing).
However, during the last century, processing has been driven mostly by “convenience” by providing partly or fully cooked options, to reduce the time spent by individuals in cooking and to instead apply that time to activities outside home. Social structures in India are changing, as individuals are migrating out of their home-towns to other locations within the country. The number of households is increasing dramatically, while cooking time and cooking skills are both declining. With this, out-of-home consumption as well as partially or fully-cooked packaged foods are bound to rise, leading to greater need of food processing capacities.
Also, with increasing industrialisation of food manufacturing, standards have become important both for efficiency and for safety. We’re seeing signs of such development happening in recent years in India as well – expectations of both consumers as well as regulatory authorities are higher with each passing year. The industry needs to invest proactively in better technology and processes in all areas – cultivation, handling, processing, packaging, storage and transportation – to raise the standards of hygiene, safety, traceability etc.
Food productivity needs urgent attention:
India is among the largest producers of many agricultural products. However, our yields per head of workforce, per animal, per hectare, or per litre of water consumed can be improved significantly. Not only is the population growing, but per capita consumption of most products will rise as the economic situation of each family unit changes. Better practices, technologies and know-how need to be acquired and applied to dramatically improve Indian agricultural productivity.
An interesting model of development to look at is the “golden triangle” approach followed by the Netherlands – active and intensive cooperation between the government, academic institutions and the private sector.
So far, by and large, academic institutions in India have limited themselves to “teaching” and have stayed away from actively collaborating with industry. Academic institutions and the industry typically connect only for the occasional “lecture” by senior individual from industry, or during the time of recruitment of fresh talent. Government largely limits itself to creating macro-level policies. More effective communication and coordination between these three legs could help to dramatically improve the standards in the agricultural and food sector in India and make the nation not just self-sufficient but significantly more competitive in both cost and quality of the final products.
Similarly, active collaboration within the industry itself is important to achieve combined growth, which can only happen if companies step beyond the usual industry association framework.
Local production and service of food processing equipment is an important factor:
In cases where the market is large enough, local production of the equipment should certainly be investigated because it can help to bring down the initial capital cost for customers, and also provide a quicker service and support base.
A first step that a company takes is to create a local presence, either through a distributor or agent, or by directly opening a sales and service office of its own. However, most international companies need to gain a certain degree of confidence in the market, both in terms of sustained demand and in terms of operating conditions, before they would invest in manufacturing in India, since it takes a whole different level of management commitment as well as financial involvement.
With the announcement of the government’s “Make in India” initiative, hopefully more international companies will come forward to take advantage of the changing operating environment in the country.
Devangshu Dutta
March 24, 2011
During its history, the Indian subcontinent has been known as the “Golden Bird” for its natural and manufactured riches. In fact, long before the United States of America, India was the Land of Promise. (The irony, of course, is that Columbus also set foot on North America when he was actually trying to discover an alternative route to India.)
However, in the more recent centuries, India became an exploited golden goose which not only stopped laying golden eggs, but also almost appeared starved at different points in time.
The government’s thrust on infrastructure and industrialisation in the 1950s would have been a great base for economic growth, but the country had to wait another 4 decades to see a true boom, which only happened after the government began stepping back from excessive controls. Similarly, while the Green Revolution took India to self-sufficiency in grain and White Revolution made India the largest producer of milk, we are very far from the place where we can celebrate a boom in agriculture.
If anything, the recent economic boom is much more an urban and upper-income phenomenon, and that is creating some serious socio-economic fault-lines, about which I have expressed concern earlier. The growth of income inequality looks slower in the case of India than in the case of China, but that is only because India still has far too many poor people weighing down the decile averages.
My concern today is of a different nature: about the need to secure food and nutrition supplies for the burgeoning economy.
Over the decades, farm-holdings have steadily fragmented. With shrinking parcels, a farming family finds it increasingly difficult to create enough surplus produce to trade effectively. As farming becomes unattractive, the family looks at alternative, primarily urban opportunities to generate income, reducing the hands available to farm.
At the same time, economic shifts are causing increasing urbanisation, as concrete and glass takes over what used to be active farming land. Large cities such as Delhi (Gurgaon) and Bengaluru are prime examples, but the phenomenon is affecting smaller cities as well.
The demographic dividend to which we should otherwise look forward could, therefore, turn out to be a triple time-bomb, with:
The employment issue needs to be addressed by placing adequate emphasis on manufacturing (especially labour intensive products) and entrepreneurship, but without addressing agriculture, even this growth would unsustainable.
Also, India is at the inflexion point similar to where China was in the 1990s. The increasing income is leading to changes in food consumption. Not only is the overall consumption growing, the diet is broader and more balanced, as people are able to afford a greater variety of food. There is a growing consumption of milk, meat and poultry products, as well as processed foods (per capita of processed foods quadrupled from the late 1980s to the early-2000s). All of these require more inputs (land, feed, water, and fertiliser) per unit of food produced.
We may be tired of hearing this, but Indian farm productivity continues to be among the lowest in the world. For instance, India as the largest milk producing country is still only at about half the level of milk production per head of cattle, when compared to the global best. Similar comparisons can be made across the food supply chain.
There are three legs to create a change: technology, dissemination of information, and market demand.
There is an urgent for technology infusion across the chain, from seed to shelf. Technology doesn’t only mean tinkering with the genetic code (about which there are significant sensitivities). Traditional technologies that are centuries-old can be as effective, sometimes even more so, as technologies that come out of modern labs. If we can avoid taking a “fundamentalist” approach between modern and traditional, we will probably achieve much more, and faster in cultivating and harvesting more efficiently.
Information dissemination is vastly superior today, and with the convergence of internet and mobile technologies, not only is it possible to compile ever more information, but also spread it in regional languages very cost-effectively.
But these two alone will not be quick enough. The last, but possibly the most important leg, is market demand.
For obvious reasons, manufacturers and retailers are focussed on growing their brands, sales and driving per capita consumption. I would argue they also need to look equally critically and perhaps more urgently at the supply chain.
Without seeing the farmer and the processors as true partners in the supply chain, and ensuring them a productive existence, any victory on the market or brand-side will only be hollow.
As customers, retailers and brand manufacturers not only have the weight, but the sophistication to encourage development. Retailers and brands have the power to drive change. They must also assume the responsibility. A few of them have begun showing the way, but need support from many more. Urgently.
