admin
August 1, 2026
Murali K Menon, Firstpost
1 August 2026
The next time you are shopping for veggies on a quick commerce app, we’d suggest you hop onto the organic produce section and consider where those vegetables came from. Chances are, they have travelled through a supply chain pretty different from the one that bought veggies to your kitchen just five years ago. Some of that produce is supplied by Urban Farms Co., a little-known company that is rethinking food systems.
Urban Farms works with about 2,000 small farmers on the outskirts of several of India’s cities, as well as in states like Rajasthan and Maharashtra to grow vegetables using regenerative practices and supplies them to urban consumers via quick commerce and modern retail. The definition of renegenrative agriculture changes depending on who you ask, but broadly it refers to an approach that seeks to restore soil health, as opposed to conventional, chemical-intensive farming.
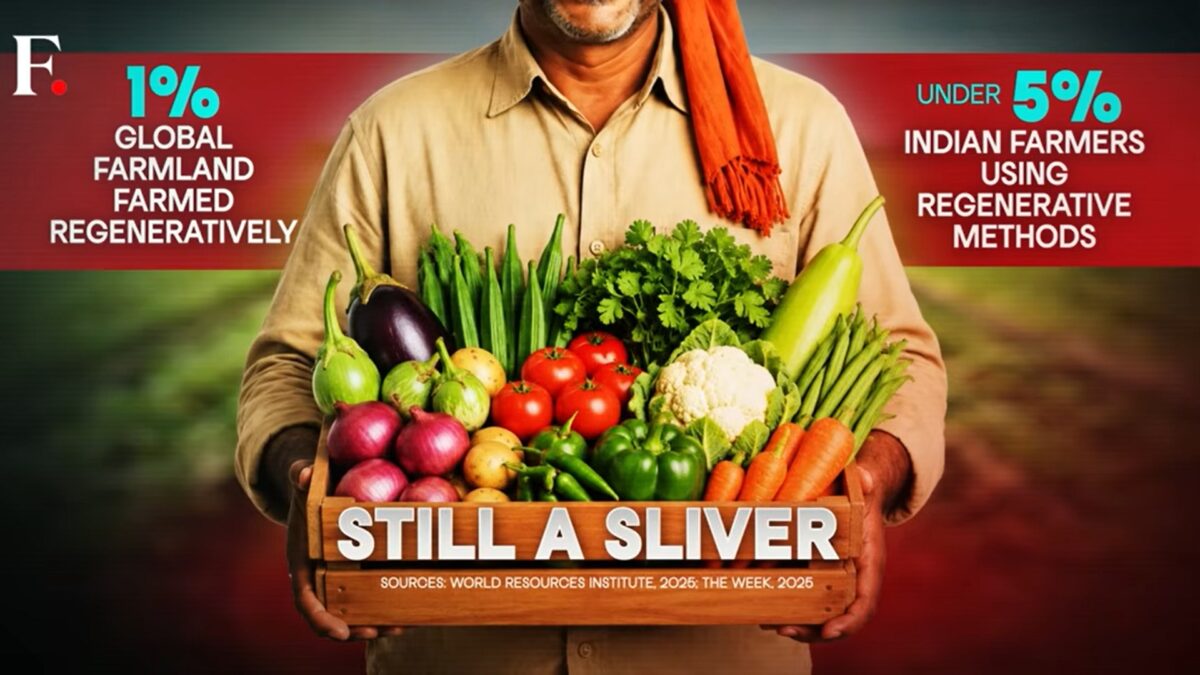
About 1% of global farmland is now under regenerative practices, according to a 2025 World Resources Institute study. Urban Farms, whose farmer network grows over 50 varieties of vegetables, handles around 12,000 tonnes annually and is targeting a twenty-fold jump in revenue from its current Rs 30 crore in the next five years.
That target might sound ambitious until you look at its origins. Urban Farms was founded by members of the team behind Araku Coffee, the specialty coffee brand that put Indian coffee on the global map. Both Araku Coffee and Urban Farms are backed by the Hyderabad-based Naandi Foundation, among the country’s largest, multi-sector non-profits. The NGO was set up by Dr. Reddy’s Laboratories founder, the late Kallam Anji Reddy, and counts Kris Gopalakrishnan and Anand Mahindra on its board.
The broad details of Araku Coffee’s success are well known, but the model that underpins it is much less discussed. Over two decades, the project worked with thousands of tribal farmers to promote regenerative farming practices, restore degraded land, and improve farmer incomes while building a globally recognised premium coffee brand. The same spirit animates Urban Farms. Instead of tribal farmers, it works with small farmers on the outskirts of India’s cities. Instead of a premium export crop, it is betting on everyday vegetables sold through quick commerce and modern retail. But can a model proven in a premium niche survive in the toughest, most commoditised part of Indian agriculture?
Beyond coffee
Coffee was just a conversation-starter, says Manoj Kumar, the lead architect of the Araku Coffee project and the founding CEO of the Naandi Foundation. The developmental economist says that the project proved two things. “It proved at scale that our regenerative organic agricultural science worked for 20 years in every crop, from coffee to millet, consistently season after season, without any drop in yield. And, just as importantly, that we could do world-class excellence at scale with very ordinary poor people.”
The eventual goal was improving farmer economics. “In India, 85% of farmers have less than one hectare of land,” Kumar says. “The question is: what do we do with small and marginal farmers?” Urban Farms is one answer to that question. Unlike Araku Coffee, though, it isn’t built around a single crop.
“Urban Farms is about doing a system change. We are changing food systems,” says Vikash Abraham, the company’s CEO. So, what does that mean for something as everyday as a lady finger? Before it reaches your kitchen, Urban Farms is involved in almost every stage of its journey. It supplies regenerative fertilisers to farmers, works with them through the growing season, buys back their produce, and sells it to retailers and quick commerce platforms.
Urban Farms
“We procure from the farmer at the same price as conventional produce. We do not pay a premium per kilogram because we believe profitability is about cost of cultivation versus the entire income you get from your farm,” Abraham says. In other words, with Urban Farms, farmers don’t earn more because they sell lady finger at a higher price. They earn more because regenerative farming lowers their costs while giving them an assured buyer. A typical vegetable grower could earn as much as Rs 20,000 to Rs 30,000 more per acre annually, says Abraham, with savings increasing over time. A first-season comparison conducted by the company across 56.5 acres in Wardha, Maharashtra, found that soybean yields rose 12% and total cultivation costs fell by 8%.
Spending on farm inputs dipped from ₹9,750 to ₹5,267 per acre, while profits increased from ₹12,550 to ₹19,195. The model does not rely on government subsidies and farmers pay for the inputs themselves. According to Abraham, Urban Farms doesn’t approach farmers from a moral standpoint, or talk about climate change. “We go to them with a business proposition, and the business proposition is about making profitability.”
From trial to habit
Urban Farms’ residue-free vegetables generally cost about 40% more than conventional produce, although the gap varies by crop, market prices, and platforms. Lady finger, for instance, was priced at ₹24 for a 250gm pack on Zepto in Azadpur, in north Delhi, earlier this week compared with ₹17 for conventional produce; on Blinkit, the same pack was sold at ₹35.
Quick commerce accounts for 65% of its business under the residue-free category, with modern trade and other channels making up the rest. Abraham says part of that premium reflects the cost of maintaining a separate, traceable supply chain. The company supplies Blinkit, Zepto, Swiggy, and Flipkart as well as Reliance, Jubilant, and Country Delight, among others.
Devangshu Dutta, founder of retail consultancy Third Eyesight, says that he expects demand to grow, as incomes rise and consumers become more conscious of the food they are eating. But he thinks a 40% premium may be too high for regular consumption because vegetables, unlike coffee or craft chocolate, are staples.
“You could have a premium of maybe 20% to 30%. Some products could be higher than that, but that is something that has to be managed carefully.” For category growth to accelerate, he says, the produce must become “a fixture in the consumer’s pantry, in the consumer’s kitchen, on the consumer’s plate.”
Dutta believes that quick commerce is well-suited to fresh produce because Indian households have traditionally bought vegetables frequently rather than stocking up. “The bottleneck really is having the product range that consumers will buy over a period of time again and again.” That requires farmers growing different crops across regions and climatic zones. And building a wide range of vegetables also means working with farmers and ensuring farmer retention in the system season after season. “You don’t just sign up a farmer and say he’s going to be there forever,” Dutta says.
Urban Farms says it has managed to do that so far. In May this year, Anand Mahindra posted on X that 80 to 90% of the farmers who work with the company return every season. “Not out of loyalty to a movement, but because the economics work,” he wrote, pointing to yields comparable with conventional farming, lower input costs and produce that consistently tests residue-free.
Abraham says that Urban Farms would like to work with about 100,000 farmers by 2030, and the company’s growth will depend on how quickly it can both build and nurture relationships with its partners across the country. Applying the Araku model to a far more unpredictable market won’t be easy, but if Urban Farms can keep both farmers and shoppers in the system as it grows, coffee, as Manoj Kumar said, may indeed have been just the conversation-starter.
(Published in Firstpost)
admin
August 1, 2026
Two decades ago, the team at the Naandi Foundation turned tribal farmers in a remote Andhra valley into some of the world’s best-paid coffee growers. Araku Coffee now sells in Paris, and the best of it goes for thousands of rupees a kilogram. Now the same team is trying to do it again — this time with everyday vegetables. Their company, Urban Farms Co., works with regenerative farmers and sells their produce on apps like Blinkit and Zepto. The bet is that what worked for premium coffee can work for staples too. But vegetables aren’t coffee. They’re cheap, everyday, and something people buy all the time. Can this really scale, and does it actually leave farmers better off?
admin
November 6, 2014
India has a rich culture and ecosystem of social enterprises, non-profits and many other social purpose organisations that serve the needs of many segments of society within a vast landscape. However, for a foreign investor looking for impact investing or other philanthropic opportunities in India, it can often prove to be a challenging journey. Devangshu Dutta (Third Eyesight/PVC Partners) and the Audrey Selian (Artha Platform) together provided a landscape overview of India, highlighted key challenges and pitfalls to look out for, and shared an insider view for international investors in this first part of AVPN’s India series.
Devangshu Dutta
October 25, 2014

These are thoughts shared in an emailed interview with the AgriBusiness and Food Industry magazine (published in the November 2014 issue.)
A Perspective on the Indian market:
Our first word of advice to companies that are looking at India as an evolving and large market, is to acknowledge the fact that that it has very diverse cuisines and food cultures.
Both Indian and international companies wishing to enter this market for the first time need to understand and acknowledge that one-size certainly does not fit everyone.
The variety of finished products needed requires food companies to address smaller quantities and to have flexible production.
Therefore, suppliers of capital equipment and technology also need to be able to think about how they can make their solutions more flexible to adapt to changing market needs, and also to price them appropriately for the Indian market. Simply extending solutions that work in large, developed markets such as Western Europe and North America is not the best approach.
I would use the example of one of our clients, a manufacturer of bakery automation equipment, who have approached the market with an open mind. After initial investigations they have gone back to the drawing board and created production lines that have smaller capacity, can produce multiple products including Indian specialities, and which are techno-commercially more feasible for an Indian customer to adopt.
There is no reason to think that India’s food industry should follow exactly the same development curve as the west. The population is much larger, with significantly lower income, and needs that are far more diverse and changing far more rapidly than in most other economies. The technical and technological models for India need to be strongly focussed on four major attributes:
Agricultural, horticultural and animal husbandry practices and technologies, as well as those in the downstream sectors such as food processing, need to perhaps even look at setting new benchmarks for accessibility and long-term sustainability.
Food processing and the Indian consumer market:
Food processing has been part of human history since we learned to transform hunted, gathered and farmed raw products into new foods through curing, cooking, culturing etc. This processing has been driven by mainly two major factors: to make the raw material into a product that is more palatable and easily consumed (for example, from raw grains to bread), or to extend the storage life of the raw material (for example, in the form of cheese, pickles, or sweets, or using cooling and freezing).
However, during the last century, processing has been driven mostly by “convenience” by providing partly or fully cooked options, to reduce the time spent by individuals in cooking and to instead apply that time to activities outside home. Social structures in India are changing, as individuals are migrating out of their home-towns to other locations within the country. The number of households is increasing dramatically, while cooking time and cooking skills are both declining. With this, out-of-home consumption as well as partially or fully-cooked packaged foods are bound to rise, leading to greater need of food processing capacities.
Also, with increasing industrialisation of food manufacturing, standards have become important both for efficiency and for safety. We’re seeing signs of such development happening in recent years in India as well – expectations of both consumers as well as regulatory authorities are higher with each passing year. The industry needs to invest proactively in better technology and processes in all areas – cultivation, handling, processing, packaging, storage and transportation – to raise the standards of hygiene, safety, traceability etc.
Food productivity needs urgent attention:
India is among the largest producers of many agricultural products. However, our yields per head of workforce, per animal, per hectare, or per litre of water consumed can be improved significantly. Not only is the population growing, but per capita consumption of most products will rise as the economic situation of each family unit changes. Better practices, technologies and know-how need to be acquired and applied to dramatically improve Indian agricultural productivity.
An interesting model of development to look at is the “golden triangle” approach followed by the Netherlands – active and intensive cooperation between the government, academic institutions and the private sector.
So far, by and large, academic institutions in India have limited themselves to “teaching” and have stayed away from actively collaborating with industry. Academic institutions and the industry typically connect only for the occasional “lecture” by senior individual from industry, or during the time of recruitment of fresh talent. Government largely limits itself to creating macro-level policies. More effective communication and coordination between these three legs could help to dramatically improve the standards in the agricultural and food sector in India and make the nation not just self-sufficient but significantly more competitive in both cost and quality of the final products.
Similarly, active collaboration within the industry itself is important to achieve combined growth, which can only happen if companies step beyond the usual industry association framework.
Local production and service of food processing equipment is an important factor:
In cases where the market is large enough, local production of the equipment should certainly be investigated because it can help to bring down the initial capital cost for customers, and also provide a quicker service and support base.
A first step that a company takes is to create a local presence, either through a distributor or agent, or by directly opening a sales and service office of its own. However, most international companies need to gain a certain degree of confidence in the market, both in terms of sustained demand and in terms of operating conditions, before they would invest in manufacturing in India, since it takes a whole different level of management commitment as well as financial involvement.
With the announcement of the government’s “Make in India” initiative, hopefully more international companies will come forward to take advantage of the changing operating environment in the country.
Devangshu Dutta
October 14, 2008
If you’re like me, then at any given point of time you have a vague idea about what is in your refrigerator, but not quite. That must why we end up buying stuff that duplicates what is already in the fridge.
Here’s an example of what that translates into for me:
At other times, it is the semi-consumed half-loaf of bread that gets trashed half-way through its fossilization process. Or the new flavour of cheese spread, where the price offer may have been tastier than the spread itself.
I sure there will be at least some among you who would have similar stories. (I would be shattered if I’m told that I am the only one with these tales of inadvertent consumption!)
In the normal course, we would not call ourselves excessive consumers. For the most part, we believe we display rational shopping behaviour. We make our lists before leaving for the market and we generally know which shop or shops we want to stop in at. So, why do we end up doubling or trebling our purchases, when we aren’t actively “consuming” double or triple the amount of food?
Well, the lords of marketing spin have mapped their way into our minds. In a strategy that has been proven over centuries, we are offered things ‘free’ or at a significant discount. The very thought of getting something for free, or for less than what it is worth, is so seductive and irresistible.
(As an aside, just look at what has happened during the last few years in the real estate market and the stock market – everyone thought that they were getting a good deal because the stuff was “worth actually more” than the amount they were paying. Not!)
We believe we are being rational in buying the three packs of juice at the price of two – never mind the fact that juice wasn’t on the shopping list in the first place. The danglers and end-caps jump out and ambush us, as we walk through the aisles. The samplers entice in their small voices: “try me”.
You might say that the really traditional kiranawala is the customer’s greatest friend and also a barrier against uncontrolled consumption.
By keeping the merchandise behind the counter or in the back-room, he maintains a healthy distance between the addiction source and all us potential shopaholics. In fact, he goes beyond the call of duty, and even prevents us from stepping anywhere near the merchandise by delivering to our homes.
The enticing deals and offers that you can’t see won’t hurt you. You won’t call to get that new, exciting BOGO (buy one-get one) offer, because you don’t know that it’s there in the store.
Unless, of course, the sneaky brand with its accomplice – the advertising agency – sidesteps him, and puts out the temptation in your morning newspaper.
By now, surely, you’re wondering whose side I am on.
Well, as a consumer and a customer, I am only on one side – mine!
As someone who is intensively involved with the retail sector, I’m also on the side of the brands and the retailers.
And believe me, we are all actually sitting on the same side of the table.
The years in this decade, after the recovery from the minor blip of dot-com busts, have been like one mega party and most people have forgotten that parties seldom last forever. And the morning after the wild party can start with quite a headache.
Retailers and brands have recently acted as if there is no end to multiplier annual growth rates, and consumers have been only to happy to prove them right. Until now.
Currently, we are passing through a fairly serious global economic correction which started in 2007. But it has only really hit hard in the last couple of months, as the headlines have increasingly started talking about recessions and depressions. Naturally, there are some people who have really lost money, others may be looking at the possibility of lower income. But even those people who sustain their current incomes are “feeling poor”, just as they were “feeling wealthy” when the markets were booming.
Of course, superfluous or discretionary expenditure such as movies in multiplexes, eating out etc. are the first to get hit. But should grocery retailers rest easy – after all, people still have to eat, right?
And how about deals, and multi-buy discounts – isn’t this the scenario where “more for less” will be the strategy which will work?
Well, I don’t believe it is quite so cut-and-dried, or quite so simple. The grocery shopping lists will not only become tighter, but will also be more tightly adhered to. Anything that looks like it may be a wasteful expense will be unlikely.
Remember the deals in the fridge? What you are throwing away now starts looking like money being put into the trash.
Pardon the seemingly sexist remark, but men: your wives will not let you get away with driving your trolleys irresponsibly into aisles where you are not supposed to be!
So how should retailers and brands respond?
Well, a good starting point would be to understand what the real market is. Let us not infinitely extrapolate growth figures on a excel spreadsheet on the basis of the early-years of new businesses. Let us not extrapolate national demand numbers from the consumption patterns of select suburbs of Delhi and Mumbai.
When we have the numbers right, let’s look at the business fundamentals at those basic levels of consumption. Is there a viable business model?
Is the business full of productive resources, or are we overstaffed with “cheap Indian labour”?
Is your modern retail business or your food / FMCG brand really providing value to the Indian consumer? For instance, two very senior people from large retail companies were very vocal this last weekend in stating that the value provided by local business to the value-conscious consumer was grossly underestimated by the industry.
I believe that best filter for business plans is the filter of business sustainability. How sustainable is the business over the next few years? What is the real demand? What are the true cost structures, and can these be supported on an inflationary basis year-on-year, or will you be squeezing the vendors for more margin at every stage until the relationship goes into a death spiral?
Let’s look at macro-economics. Are you actively looking at generating and spreading wealth and income around, or is your focus only on stuffing that third pack of juice into the fridge for it to go stale? If your strategy is the latter one then, to my mind, that is neither a sustainable economic model nor a sustainable business.
There’s more about the current and developing economic scenario, “realistic retailing” and other such issues, elsewhere on the Third Eyesight website and blog, including a presentation made at the CII National Retail Summit in November 2006 (download or read as a PDF). (The article based on that presentation is here.)
I really look forward to your thoughts and would welcome a dialogue on how you believe retailers and brands should work through the next few years as we unravel the excesses of the recent past.
