
admin
August 11, 2026
Samar Srivastava, Forbes India
11 Aug 2026
Ask someone what an exurb is and chances are you’ll be met with a blank stare. Few city slickers would have heard of the term, let alone visited one. Located about 90 minutes from Gurugram, Ateli fits the description perfectly.
The drive is deceptively easy. Wide highways, sparse traffic, and long stretches of open countryside gradually give way to a settlement that feels oddly familiar. “If you’d had shut my eyes and brought me here, I’d have said we weren’t too far from Gurugram,” says Manish Tiwary, 56, managing director of Nestlé India.
Ateli is a residential settlement that has grown around its agricultural market. Cars jostle with cattle for road space. Kirana stores spill onto narrow streets.
Labourers gather at intersections in search of daily wage work while small factories, unfinished commercial buildings, and modest homes stand shoulder to shoulder. It has the look and feel of the outskirts of any fast-expanding Indian city.
Yet beneath that ordinariness lies something far more significant. With a population of barely 9,000, Ateli represents the kind of semi-urban India that is rapidly emerging as the country’s next consumption frontier. Rising incomes, better roads, deeper internet penetration, and easier access to branded products are narrowing the divide between metropolitan India and its smaller towns.
For Nestlé India, places like Ateli have become central to its next phase of growth. Tiwary, who took Forbes India through the town on a cloudy May morning, is convinced that India’s consumption story is changing. “The aspirations are the same,” he points out. “What sells on the fringes of an urban market is similar to what sells here.”
Whether consumers live in Gurugram or Ateli, they increasingly want the same products, brands, and experiences. The challenge for companies is no longer generating demand; it is ensuring that products are available where consumers want them, and at prices they are willing to pay.
Remapping the route
The conviction is informed by experience. Before taking over at Nestlé India, Tiwary headed Amazon India, where he watched demand for smartphones, air conditioners, diapers, and other discretionary products steadily spread beyond India’s largest cities. Consumer aspirations, he realised, were travelling much faster than traditional distribution networks.
Getting Maggi noodles, Nescafé coffee or KitKat chocolates into thousands of towns like Ateli, however, is a far more complicated proposition than shipping electronics through an ecommerce warehouse. On a per item percentage basis, the cost of distribution is higher, there are also more varied stock keeping units (SKUs) and the frequency of consumption means replenishment has to be faster. Fast-moving consumer goods (FMCGs) are low-ticket, high-frequency purchases. Margins are thinner, replenishment cycles are shorter and distribution economics are far more demanding.
Nestlé’s answer has been a patient, years-long investment in rebuilding its route to market. “Earlier, the company was over-indexed on urban India but the focus has now shifted to rural India,” says Amit Agarwal, SVP, fundamental research, Kotak Securities.
The timing appears to be fortuitous. Nestlé kicked off the June quarter with another strong performance, reporting a 48 percent jump in net profit to ₹975 crore, on a 25 percent increase in revenue to ₹6,378 crore. With this the company continued the strong performance it posted in the year ended March 2026. March quarter revenue and profits were up 23.1 and 22 percent respectively. The management attributed the performance to strong volume growth, wider distribution, and continued traction across both urban and rural markets, while cautioning that inflation in commodities such as cocoa, edible oils, and sugar remains a key watchpoint.
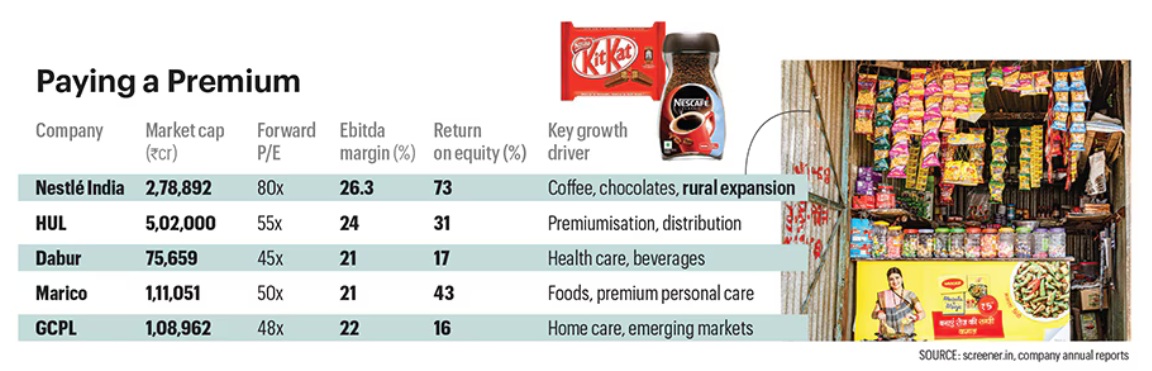
Investors have taken notice. Nestlé India’s shares have risen around 16 percent over the past year, giving the company a market capitalisation of roughly ₹2.79 lakh crore. At about 80 times forward earnings, it commands the richest valuations in India’s consumer sector, trading ahead of multinational peers such as Hindustan Unilever (HUL) and Colgate-Palmolive as well as domestic rivals Dabur, Marico and Godrej Consumer Products.
The premium reflects more than strong quarterly earnings. Across corporate India, companies that invested early in brands, distribution and execution are beginning to pull ahead as consumption gradually recovers. Listed liquor companies such as United Spirits and Radico Khaitan have continued to post double-digit revenue growth, reflecting resilient discretionary spending. Automobile manufacturers have benefited from lower financing costs and tax relief, particularly in entry-level motorcycles and small cars. FMCG companies with a meaningful rural presence have also reported improving volume growth.
The recovery has been uneven, but the direction is becoming clearer. According to NielsenIQ, rural India has outpaced urban markets in FMCG growth for eight consecutive quarters, with improving household incomes and higher spending in smaller towns driving much of the momentum. For companies that have spent years investing in distribution rather than chasing short-term margins, the payoff is beginning to manifest.
Nestlé believes it is particularly well positioned. Its categories—coffee, chocolates, baby food and noodles—remain under-penetrated compared with staples such as biscuits, soaps and toothpaste. That gives the company a rare opportunity: Not merely to take market share from rivals, but also to create new consumers. That ambition begins in places such as Ateli.
Direct Push
Ground zero for Nestlé’s rural strategy is Rakesh Kumar’s 12-by-12-foot kirana store-cum-warehouse in Ateli. The 35-year-old, who comes from a farming family, has been running the shop for more than a decade. The biggest change, he says, is not the number of customers walking through the door, but what they are buying. Alongside soap bars now sit oats, muesli, coffee, soups and Cerelac baby food.
“These are products no one was interested in five years ago,” Kumar says. “Now we get steady enquiries because people have become far more health conscious.” The shop’s shelves tell the story of India’s changing consumption patterns. Kumar stocks products from dozens of companies—from ITC and Perfetti to Ferrero and Keya—but his store also offers a glimpse into how the country’s FMCG distribution model is being rewritten.
A decade ago, retailers like him were supplied largely through wholesalers. Consumer companies concentrated their own sales forces in larger towns where inventory turned faster, leaving intermediaries to service smaller towns and villages.
It was an efficient system: Mass television advertising created demand, wholesalers ensured products reached retailers in a cost-efficient manner, and shops became the last mile of India’s consumption engine.
That model is now under pressure. Modern trade, ecommerce and quick commerce have chipped away at distribution as a competitive moat. Digital advertising has fragmented audiences, while nimble direct-to-consumer (D2C) brands have intensified competition across categories.
Simply reaching consumers is no longer enough. Companies increasingly need to know what consumers are buying, how quickly tastes are changing and which products are beginning to gaining traction.
Nestlé’s response has been to rethink rural expansion itself.
A re-run
“It has become more holistic and comprehensive,” says Sushrut Nallulwar, sales director at Nestlé India. Distribution remains the backbone of the strategy, but it is now supported by technology, locally relevant marketing and products designed specifically for different consumer segments. “It’s not just about scaling up route-to-market infrastructure anymore.”
Tiwary has watched this move before. During his years at HUL, the company dramatically trebled its rural direct footprint after identifying villages and small towns as the next engine of growth. The then chairman Harish Manwani famously told shareholders that though competitors were creating gaps, HUL had to “continuously create new gaps”.
Nestlé is now following a similar philosophy, albeit for a very different retail landscape. Retailers such as Kumar, who once depended almost entirely on wholesalers, are increasingly serviced directly by the company.
The economics are demanding. Serving thousands of retailers, each buying between ₹1 lakh and ₹5 lakh worth of products every month, requires warehouses, technology, logistics, credit management and a large field sales force. “The number of outlets is less important than what direct distribution gives you,” says Nallulwar. “It gives you control.”
Today, Nestlé reaches roughly 6 million retail outlets across India, of which around 2 million are serviced directly. Those outlets account for nearly 75 percent of the company’s sales, giving it far greater visibility of consumer behaviour than a traditional wholesale-led model.
While distribution models vary across FMCG companies, wholesalers continue to account for a much larger share of sales for most players. Nestlé estimates that wholesale contributes about 20 percent of its business compared to an industry average of 40 to 45 percent. The company is effectively choosing to incur higher distribution costs in return for better market intelligence and tighter execution.
Buying better data
Every direct interaction with a retailer generates information. Nestlé learns which products are moving fastest, which pack sizes consumers prefer, how frequently shelves are replenished and where competitors are beginning to gain ground. If a rival noodle brand suddenly starts selling well in Ateli—or consumers begin shifting towards smaller packs—the company knows almost immediately.
“Nestlé is essentially buying better data,” says Devangshu Dutta, chief executive of Third Eyesight, a retail consultancy. “That may depress margins in the short term, but it creates a much stronger competitive position over time. Better visibility of what retailers are stocking and consumers are buying allows it to react much faster than a wholesale-led model.”
Control, however, extends well beyond making sure cartons arrive on time. The backbone of that system is increasingly digital. Orders are placed through Nestlé’s retailer app. Field sales representatives capture information on stock availability, competing brands and consumer preferences during every store visit. That information flows back into the company’s planning systems, allowing it to fine-tune inventory, merchandising and product innovation market by market.
For Nestlé, distribution is no longer about moving products. It is about reducing the distance between the consumer and the company’s decision-makers. The insights frequently translate into product decisions. According to Nallulwar, nearly two-thirds of rural FMCG purchases happen at the ₹5 and ₹10 price points, making affordability just as important as physical reach. “It is not just about reaching outlets,” he says. “There has to be consumer relevance in terms of availability at the right price points.”
One example hangs right outside Kumar’s shop.
Seeding the market
Insights from Nestlé’s sales teams prompted the company to redesign its ₹10 Maggi packs. Instead of individual packets, they are now linked together in long strips that retailers hang outside stores.
The redesign wasn’t simply about affordability. In rural India, where shelf space is scarce and many purchases are made on impulse, the hanging strips function as miniature billboards. Nallulwar calls it “aerial visibility”, ensuring the product catches a shopper’s eye before they even step inside the shop.
For Kumar, the benefits are equally tangible. Orders placed through Nestlé’s app typically arrive the following day, giving him faster replenishment and, at times, better credit terms than buying from wholesalers.
On India’s next consumption battleground, speed of information may prove just as valuable as speed of delivery.
Walk around Ateli and those investments are hard to miss. Across from Kumar’s store, retailers have been provided with visi-coolers stocked with ready-to-drink Nescafé, KitKat and other chocolates. “We are still seeding the market,” says Tiwary. “But it is important to be present. Expanding the category is important.”
The opportunity goes beyond instant noodles. Coffee, chocolates and baby food are all beginning to gain traction in smaller towns, but their penetration remains far below that of more established FMCG categories.
Maggi noodles, for instance, has a rural penetration rate of just 10 percent, measured by consumers who have eaten the product during the previous month. The frequency of Maggi consumption is far below the 80 percent for biscuits or 90 percent penetration for toothpastes. When you compare the categories, the size of the opportunity is evident.
“The biggest opportunity for us is that household penetration in our categories is still significantly lower than in developed categories,” says Nallulwar. “There is a large headroom for these categories to grow.”
White Spaces
For most consumer companies, growth comes from taking market share away from competitors. Nestlé believes India’s biggest opportunity lies elsewhere. It is betting that the country’s next consumption boom will come not from persuading consumers to switch brands but from encouraging them to buy products they have never bought before.
This partly explains why the company has spent the past three years expanding its distribution network into towns like Ateli. Getting products onto shelves is only the first step. The real prize is changing what ends up in the shopping basket.
Coffee illustrates the opportunity. For decades, India has remained overwhelmingly a nation of tea drinkers. At just 70 grams per person annually, India’s coffee consumption is a fraction of the global average of 1.3 kg, according to the Coffee Board of India. Europeans consume about 4.5 kg a year, North Americans 5.1 kg, while Finns drink more than 12 kg per person annually.
The gap within India is equally revealing. According to Crisil, urban Indians consume roughly four times as much coffee as their rural counterparts, suggesting that rising incomes and urbanisation could significantly expand the addressable market.
For Nestlé, the opportunity is, therefore, not merely to persuade consumers to switch from one coffee brand to another; it is to persuade millions of Indians to drink coffee in the first place. “Coffee is still a significantly under-penetrated category,” says Sunayan Mitra, director, Coffee and Beverages, Nestlé India. “That gives us a long runway for growth.”
The strategy begins with affordability. Consumers are introduced to the category through ₹2 Nescafé sachets sold at neighbourhood kirana stores and tea stalls. As incomes rise, Nestlé hopes consumers will graduate to jars, ready-to-drink cold coffee, and eventually premium offerings such as Nescafé Gold Blend and Nespresso.
That journey—from an impulse purchase to a premium brand—is shaping how the company thinks of growth. “Ultimately, if I don’t have anything new to offer the consumer, why would they upgrade?” says Tiwary.
The same philosophy applies to other products as well. Take chocolates. Per capita chocolate consumption in India remains among the lowest globally, despite rapid premiumisation over the past decade. Baby food continues to be significantly under-penetrated. Pet food, while growing rapidly, remains a tiny category compared with the developed markets. Even Maggi noodles, as mentioned earlier, reaches only around 10 percent of rural consumers despite being Nestlé’s biggest brand.
Finding these categories has become a business in itself. Nestlé Professional, the company’s out-of-home business, has evolved into a testing ground for identifying such opportunities. Instead of waiting for consumer demand to emerge, the division increasingly searches for fragmented local markets that can be organised around trusted brands.
Two years ago, for instance, the team identified an opportunity in Kerala’s coastal belt, where coconut milk powder is used by restaurants and institutional kitchens. The market was dominated by regional manufacturers with varying quality standards.
Leveraging the familiarity of the Maggi brand and working closely with chefs and caterers, Nestlé began to push its own coconut milk powder. “It was a roaring success—we hit the jackpot,” says Saurabh Makhija, director, Nestle Professional, declining to disclose sales numbers.
The Kerala experiment has since become a template. In Hyderabad, where Irani chai is woven into the city’s food culture, Nestlé segmented bakeries into premium, mainstream and economy outlets before introducing Milkmaid as an alternative to locally produced sweetened milk. Rather than attempting to change consumer habits, the company sought to formalise a fragmented market.
The lesson, says Tiwary, is that India can no longer be viewed as a single consumer market: “It is many different Indias.” A category that barely exists in one state may be mature in another. A product that succeeds in Bengaluru may fail in rural Bihar. The challenge is no longer creating national brands but identifying the thousands of local opportunities. That is where Nestlé believes its investment in distribution begins to pay off.
Every retailer visit, every digital order and every conversation between a salesman and a shopkeeper adds another piece to the puzzle. The next ₹10 product, the next regional launch or even the next national brand may not emerge from a Mumbai boardroom. It may emerge from a kirana store in Ateli.
The Next HUL?
Nestlé’s distribution push, its search for white spaces and its willingness to create entirely new categories have not gone unnoticed by investors. At nearly 80 times forward earnings, Nestlé India trades at a substantial premium to its rivals. The valuation implies investors are looking well beyond the next quarter.
For decades, HUL has been the benchmark for Indian FMCG companies—a business built on unmatched distribution, category breadth and extraordinary execution. Nestlé is unlikely to rival HUL on size anytime soon. But the question is: Can it become India’s next great consumer compounder?
Its investment case increasingly rests on three pillars. The first is distribution. Over the past three years, Nestlé has built one of the country’s deepest direct distribution networks, which gives the company not just reach, but information.
The second is category creation. Unlike many FMCG companies whose biggest brands enjoy near-universal penetration, several of Nestlé’s businesses—coffee, Maggi noodles, pet food, chocolates and baby—are in the early stages of their growth curves, giving Nestlé an unusual advantage: It is not competing for market share, but trying to expand the market itself.
The third pillar is moving up the value chain, or premiumisation. A consumer who begins with a ₹2 Nescafé sachet may graduate to a coffee jar, ready-to-drink coffee and maybe a premium blend. The same logic applies to much of Nestlé’s portfolio.
Veteran investor Bharat Shah, erstwhile co-founder at ASK Asset & Wealth Management and now in the process of setting up his own fund, has owned Nestlé’s stock for 30 years before exiting recently. He points out that years of rich profits and fat balance sheets have taken consumer companies’ attention away from adequate innovation and continued adaptability, whether in product or category creation, distribution platform innovation or technology adaptation. This is particularly true for MNCs where decision-making happens in headquarters and so they are behind the curve.
He also points to the dramatic changes in the consumer landscape—the emergence of local brands that chip away national brands, changes in the terms of trade due to the rapid advent of Q-commerce and modern trade, and the need to innovate and premiumise. Many categories have high penetration and so volume growth is hard to get.
On the drive back towards Gurgaon, it is tempting to think of Ateli as just another small town on the edge of India’s economic map. But for Nestlé, it represents the future of Indian consumption.
(Published in Forbes India)
admin
August 6, 2026
Pritha Pahari, The Core
5 Aug 2026
Saurav, a 27-year-old resident of Navi Mumbai, has bought the same tub of whey protein for three years, same brand, same 1kg pack, same monthly ritual after his gym membership renews.
Last month, at checkout, the price had jumped by nearly a thousand rupees. He assumed it was maybe a limited-time markup. But when he checked his order history, he noticed that the price had been going up for two to three months until it crossed a threshold that made him realise that whey protein has gradually become more expensive.
India is the world’s largest milk producer, yet it imports most of its whey protein because its dairy sector was never built to make cheese, the one thing that whey needs to exist.
That gap is now colliding with a global protein boom, driven partly by weight-loss drugs that leave patients needing more protein.
The result is a price rise that is now reaching the local pharmacy and fitness stores, and one that is unlikely to recede.
The Price Move
Research firm, The Daily Datum analysed Keepa price data for 11 whey protein SKUs on Amazon and found an average price increase of 32% and a median rise of 27% across varying tracking periods.
Keepa is a third-party price-tracking tool for Amazon, it logs a product’s price history over time by continuously scraping Amazon’s listing pages, so you can see a graph of how a specific SKU’s price has moved (sales, hikes, restocks) going back months or years.
Prices of different types of proteins i.e. blends, isolates and concentrates have all moved by similar amounts, and so have Indian D2C brands and long-established imported ones.
In protein powder terms, concentrates are ~70-80% protein (less processed, retain more fats/carbs), isolates are ~90%+ protein (more filtered, less lactose/fat), and blends mix two or more protein types (e.g., whey + casein, or whey concentrate + isolate) to combine benefits like fast and slow absorption.
The one outlier, MuscleBlaze’s premium Biozyme Performance line, has roughly doubled, but excluding it, the category average is still 26%, about five times India’s headline food inflation, which stood at 5.32% year-on-year in June 2026, according to government data.
The retail prices are only a reflection of what is happening with the raw ingredients needed for whey.
Imported whey protein concentrate landed in India at roughly Rs 700–800 per kg in 2024; by mid-2026, the industry estimates put it at Rs 2,300–3,000 per kg, a rise of over 200%.
Brands have absorbed much of that shock through smaller pack sizes and blended formulations rather than passing it straight through, which is why retail prices have risen a fraction of what the raw material has.
For scale, India’s protein supplement market (powders, bars and ready-to-drink shakes together) is put at roughly $860 million to just over $1 billion in 2025, though the exact figure depends a lot on which research firm and which product categories you ask (IMARC Group and Grand View Research land in that range but don’t agree closely). That compares with a global protein supplements market well above $30 billion.
Not A Farmed Commodity
“You don’t milk a cow for whey. You milk a cow for milk. And then you have to make cheese,” said Rajiv Mitra, Strategic Advisor, Sonai Dairy, a Maharashtra based dairy.
Whey from cheese-making is “sweet whey”, protein-rich and further processed through filtration and expensive drying infrastructure into the 80–90% protein concentrate that ends up in a gym-goer’s scoop.
“This is a structural bottleneck,” Mitra said. “It’s not a kind of seasonal commodity up and down.” New filtration and drying plants can take two to four years to build, with much of the machinery imported.
This is where India’s dairy habits work against it.
Devangshu Dutta, founder of the retail consultancy Third Eyesight, while speaking to The Core explained that globally, about 95% of whey protein comes as a co-product of Western-style hard and semi-hard cheeses such as cheddar and mozzarella. India’s dairy sector, by contrast, is built around paneer, curd, khoya and ghee.
Paneer is made by acid coagulation, which produces “acid whey”, lower in protein and higher in minerals, and not suitable for concentration into protein powder.
“Unless consumption of western-style cheeses grows dramatically in India, co-production capacity will remain low,” Dutta said.
Mitra makes the same point from the kitchen rather than the factory floor: squeeze lemon into milk to make paneer at home and the liquid that separates out simply gets drained. “Traditionally, for years, while we have been the highest producer of milk, our consumption pattern is such that we do not harness the whey that is produced,” he said.
That liquid is easy to overlook because it looks like nothing more than watery runoff, but it isn’t a waste.
When milk curdles, the solid part becomes paneer or cheese, and the yellowish liquid left behind, the whey, still carries a meaningful share of the milk’s protein along with lactose and minerals.
Filtered, concentrated and dried at an industrial scale, that liquid becomes the powder sold in tubs as whey protein concentrate or isolate. In most Indian kitchens it is simply poured away; in a cheese-and-whey-processing economy like the US or Europe’s, it is captured and turned into a saleable ingredient.
That gap between what gets thrown out and what gets processed is the crux of the shortage.
Why It’s Getting More Expensive
India imports an estimated 80–90% of its supplement-grade whey, mostly from the US, Europe, New Zealand and Australia, in dollars. The rupee has weakened sharply against the dollar over the past few years, from around 74 to nearly 97 by July 2026, adding another 10–15% to landed cost before customs and tax.
India’s own import policy adds a further layer of cost. Dairy is among the most protected sectors in the Indian economy: duties on whey, cheese and milk powder run 30–60% depending on the product, India offers no duty-free quota for dairy, and the government has repeatedly kept dairy outside trade negotiations, including in the interim India–US trade agreement reached in early 2026.
US suppliers, the world’s largest whey producers, also frequently fall short of the vegetarian-rennet certification Indian food rules require, which further narrows where Indian buyers can import from. None of this caused the current price spike, but it does mean India pays a built-in premium over the raw international price, and there is no sign of that premium being negotiated away soon.
Global demand, meanwhile, keeps climbing while milk output in the US and Europe grows only slowly. The global whey protein market is put at roughly $9.7 billion in 2025 by one widely cited estimate (Grand View Research).
It has clearly grown a lot over the past decade, but market-research firms disagree fairly widely on the starting point and pace of that growth.
Mitra pointed to a newer driver on top of the usual sports-nutrition demand: GLP-1 weight-loss drugs.
“Doctors have asked patients to consume more protein” to offset muscle loss from the drugs, he said, and as patents expire and generics spread to India and China, “the demand-supply gap is definitely going to increase further.”
(Some industry commentary points to semaglutide patents lapsing in markets including India and China around 2026, which would open the door to cheaper generics, though this detail comes from a single industry source and is worth treating as a general trend rather than a confirmed date.)
He laid out what he called a three-pronged squeeze: India’s own GLP-1 users will need more protein even as domestic production stays constrained; the US and Europe, which used to export surplus whey, will increasingly consume it themselves as their own GLP-1 use grows; and India’s roughly 30% vegetarian population, which depends on dairy for protein, will lean on it even harder.
Ingredient suppliers and dairy processors abroad broadly back this account, at least directionally, though they are careful not to call GLP-1 the sole cause. In wire-service and trade-press interviews, executives at FrieslandCampina and Lactalis have cited the weight-loss drug trend by name as a reason for new investment in high-protein whey processing, and StoneX’s dairy consulting head has said the food industry simply lacks the capacity to turn whey into the concentrates and isolates the market now wants. Those are real, on-record statements, but they’re a handful of quotes, not a market-wide survey, so it would be a stretch to read them as proof that GLP-1 is now a dominant driver.
The macro numbers, where they exist, suggest a more modest picture: one investment-bank estimate (cited secondhand rather than pulled from the original research note) put GLP-1’s impact on total European calorie demand at around a quarter of one percent, since only a low single-digit percentage of the population is on the drugs so far.
Separately, some retail-data providers have reported that households with a GLP-1 user spend noticeably more on protein-rich products than matched non-user households.
Taken together, traditional sports-nutrition and everyday-fitness demand almost certainly remains the larger base of whey consumption, GLP-1 use is a real and fast-growing add-on that industry executives say is starting to show up in sourcing decisions, but nobody has published a solid, independently verified number for how much of the current price spike GLP-1 specifically accounts for. Anyone who tells you an exact percentage is guessing.
Who Feels It First?
Large manufacturers are better insulated than small ones.
“The bigger players always get into long-term contracts,” Mitra said. Smaller brands and contract manufacturers, reliant on buying at spot prices, “get squeezed first.”
Big companies can also cross-subsidise from other product lines for a while, he said, but that isn’t a permanent fix: “Businesses are not there to absorb cost. Businesses are there to make profit.” Margin compression, in his words, “is never sustainable.”
An executive at HealthKart, which owns MuscleBlaze, was quoted saying in an Financial Express article that whey concentrate costs have more than tripled in two years and are “quickly approaching 4x,” and that the company has raised prices while absorbing part of the increase itself.
The founder of Wellbeing Nutrition was quoted in the same Financial Express article saying whey isolate prices have roughly tripled over the same period, and that whey, which makes up 15–20% of the company’s revenue, is now being promoted less actively as a result.
The founder of The Whole Truth, a clean-label brand that also uses cashews and cocoa, was quoted in the same article in Financial Express, saying input costs across its ingredient list have surged and that the company has pushed through several price increases, including a 15–20% hike on protein bars, rather than change its recipe.
Budget-focused brands such as Nakpro, AS-IT-IS and Avvatar have not made similar public statements, but their pricing sits in the same band as the rest of the market, and their category positioning, cheaper, no-frills whey aimed at price-sensitive buyers, looks consistent with the same cost pressure, even without a direct quote confirming it.
Smaller sachet and single-serve formats, which let a brand hold a lower shelf price even as the cost per kilogram rises, have also become more common across the category over the past year, though this is more an observed pattern than something brands have explained on the record.
Consumers shouldn’t expect quick relief either. “Commodity prices normally fall before retail prices,” Mitra said.
Existing contracts and retail pricing cycles are sticky, so the consumer will see relief much later than any drop in the raw material.
Some Headroom, No Quick Fix
Both experts see room for India to produce more eventually.
Dutta noted that rising protein-consciousness and GLP-1 adoption are giving Indian manufacturers “headroom for growth,” though feedstock constraints will remain a challenge.
Mitra talked about the scale needed: new capacity requires a couple of hundred crores of investment and years to commission, on top of a slow, generational shift in how Indians eat dairy. Cold storage for hard cheeses, which need months of ageing, is also still being built out.
Some of that investment is already happening.
Amul has launched a whey protein line priced well below imported brands, part of a broader push by Indian dairy majors to move into higher-margin, value-added products; cheese and whey can carry margins of 25–45%, against much thinner margins on liquid milk.
Parag Milk Foods already sells whey protein under its Avvatar brand and has positioned itself as a nutrition company rather than a pure dairy one.
Milky Mist, which is preparing a stock market listing, has said it will use part of the proceeds to add new production lines for whey protein concentrate, yoghurt and cream cheese at its Tamil Nadu plant.
Cheese-focused players including Schreiber Dynamix, Britannia Bel Foods and Lactalis India are separately expanding capacity, since more cheese production is what generates more whey as a by-product in the first place.
None of these projects will materially add to supply in the next year or two; dairy-processing plants of this kind typically take two to four years from investment to commissioning, and most industry estimates suggest India’s domestic whey production still covers only a small fraction of what the country consumes.
Neither expert expects plant-based protein to substitute for whey in a hurry. “Whey still offers a superior amino acid profile” and better digestibility, Mitra said, predicting diversification and hybrid blends rather than replacement.
What Could Break the Cycle?
Globally, the shortage is widely described by dairy analysts as a processing bottleneck rather than a milk shortage: milk supply itself has been broadly stable, and cheese production, which generates whey, has continued at normal levels. The constraint is the specialised filtration and drying capacity needed to turn liquid whey into the concentrated, dried powder the supplement industry uses, and that capacity takes years to build.
Major producers, including Glanbia, Fonterra, Arla, Tirlán and Idaho Milk Products, have announced billions of dollars of new whey-processing investment in the US, Europe and New Zealand over the past year. Most of these projects are expected to come online through 2027, not before, so global analysts generally don’t expect meaningful supply relief until late 2026 at the earliest, and more likely 2027.
US milk production is forecast to keep growing gradually into 2027 as well, which should help at the margin, though rising input costs (energy, feed, financing) are also squeezing dairy farmer margins in exporting regions, which cuts the other way.
For India specifically, easing would most likely need several things to move together over the next two to three years: new domestic processing capacity from players like Amul, Parag, Milky Mist and the cheese-focused majors actually coming online, rather than merely being announced; global WPC and WPI supply catching up with demand as the 2026–27 capacity wave lands; a stabler or stronger rupee, since a large share of India’s whey is still imported and priced in dollars; and some change to India’s own tariff and certification structure on dairy imports, which currently adds cost on top of the global price and shows no sign of loosening given how firmly successive governments have kept dairy out of trade deals.
GLP-1-driven demand would also need to plateau rather than keep accelerating as drug prices fall and generics spread.
Even if all of that happens, retail prices in India are unlikely to fall quickly. Brands are currently absorbing part of the cost increase rather than passing all of it through, which means a chunk of any future relief in the raw material would likely go toward rebuilding margins before it reaches the shelf.
Contracts, inventory cycles and psychological pricing (brands are usually slower to cut prices than to raise them) add further lag. Mitra’s framing captures this: raw material costs typically fall before retail prices do, and the gap between the two can run into quarters, not weeks.
What experts keep coming back to is that this has stopped being a niche fitness-industry story. “
This is no longer just about dairy,” Mitra said. It is now about healthcare, pharmaceuticals, nutrition, overall food.
(Published in The Core)
admin
August 1, 2026
Murali K Menon, Firstpost
1 August 2026
The next time you are shopping for veggies on a quick commerce app, we’d suggest you hop onto the organic produce section and consider where those vegetables came from. Chances are, they have travelled through a supply chain pretty different from the one that bought veggies to your kitchen just five years ago. Some of that produce is supplied by Urban Farms Co., a little-known company that is rethinking food systems.
Urban Farms works with about 2,000 small farmers on the outskirts of several of India’s cities, as well as in states like Rajasthan and Maharashtra to grow vegetables using regenerative practices and supplies them to urban consumers via quick commerce and modern retail. The definition of renegenrative agriculture changes depending on who you ask, but broadly it refers to an approach that seeks to restore soil health, as opposed to conventional, chemical-intensive farming.
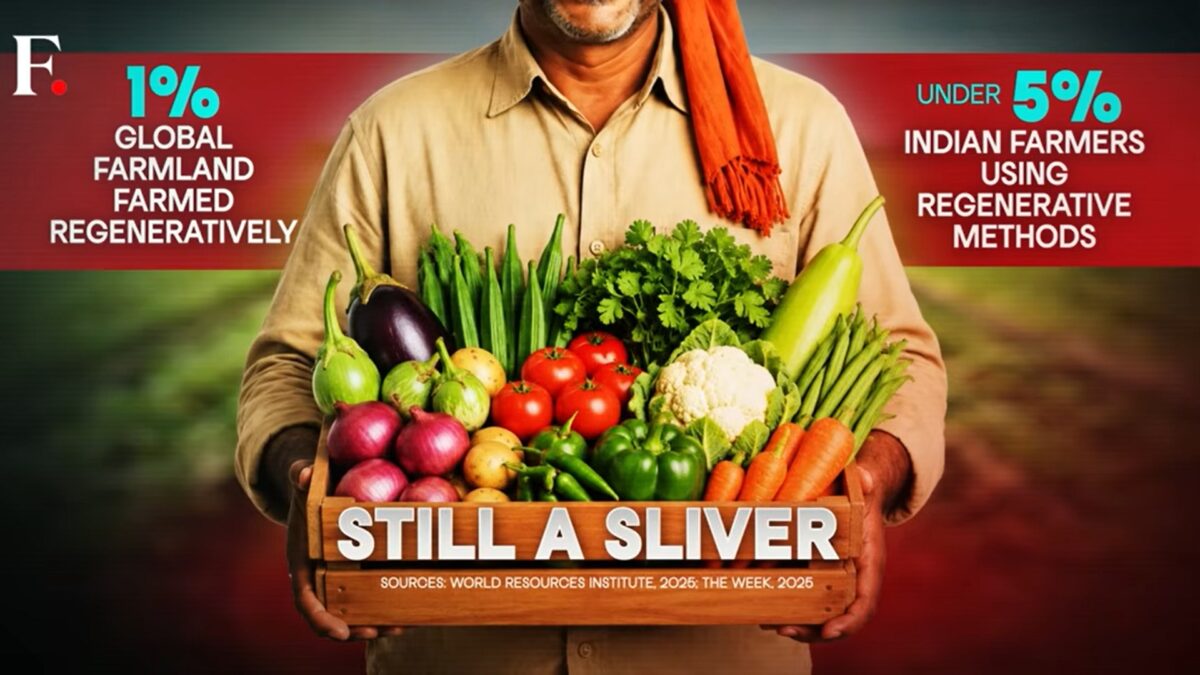
About 1% of global farmland is now under regenerative practices, according to a 2025 World Resources Institute study. Urban Farms, whose farmer network grows over 50 varieties of vegetables, handles around 12,000 tonnes annually and is targeting a twenty-fold jump in revenue from its current Rs 30 crore in the next five years.
That target might sound ambitious until you look at its origins. Urban Farms was founded by members of the team behind Araku Coffee, the specialty coffee brand that put Indian coffee on the global map. Both Araku Coffee and Urban Farms are backed by the Hyderabad-based Naandi Foundation, among the country’s largest, multi-sector non-profits. The NGO was set up by Dr. Reddy’s Laboratories founder, the late Kallam Anji Reddy, and counts Kris Gopalakrishnan and Anand Mahindra on its board.
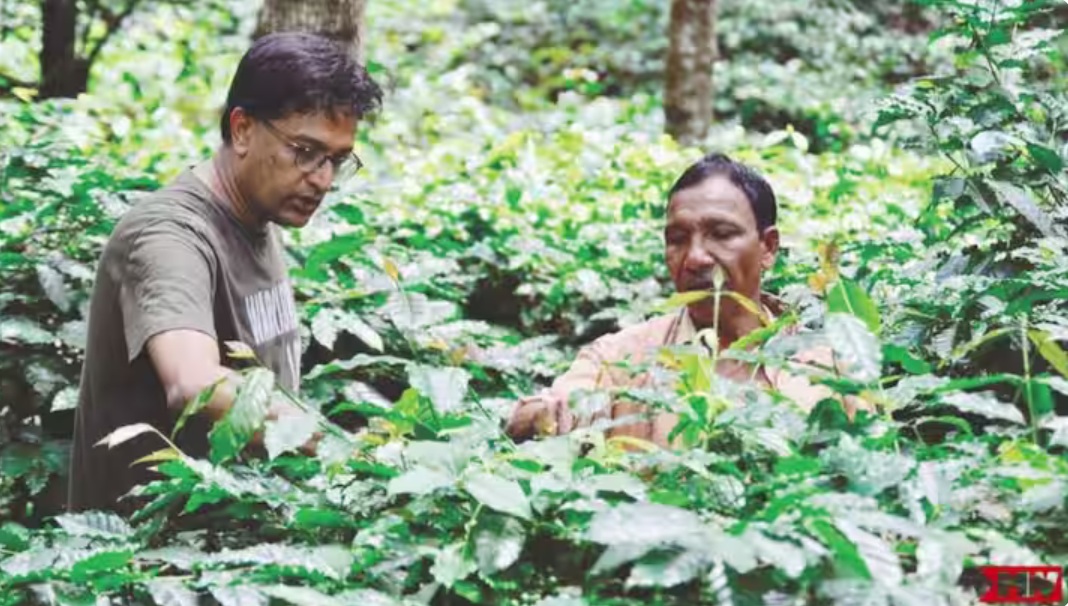
The broad details of Araku Coffee’s success are well known, but the model that underpins it is much less discussed. Over two decades, the project worked with thousands of tribal farmers to promote regenerative farming practices, restore degraded land, and improve farmer incomes while building a globally recognised premium coffee brand. The same spirit animates Urban Farms. Instead of tribal farmers, it works with small farmers on the outskirts of India’s cities. Instead of a premium export crop, it is betting on everyday vegetables sold through quick commerce and modern retail. But can a model proven in a premium niche survive in the toughest, most commoditised part of Indian agriculture?
Beyond coffee
Coffee was just a conversation-starter, says Manoj Kumar, the lead architect of the Araku Coffee project and the founding CEO of the Naandi Foundation. The developmental economist says that the project proved two things. “It proved at scale that our regenerative organic agricultural science worked for 20 years in every crop, from coffee to millet, consistently season after season, without any drop in yield. And, just as importantly, that we could do world-class excellence at scale with very ordinary poor people.”
The eventual goal was improving farmer economics. “In India, 85% of farmers have less than one hectare of land,” Kumar says. “The question is: what do we do with small and marginal farmers?” Urban Farms is one answer to that question. Unlike Araku Coffee, though, it isn’t built around a single crop.
“Urban Farms is about doing a system change. We are changing food systems,” says Vikash Abraham, the company’s CEO. So, what does that mean for something as everyday as a lady finger? Before it reaches your kitchen, Urban Farms is involved in almost every stage of its journey. It supplies regenerative fertilisers to farmers, works with them through the growing season, buys back their produce, and sells it to retailers and quick commerce platforms.
Urban Farms
“We procure from the farmer at the same price as conventional produce. We do not pay a premium per kilogram because we believe profitability is about cost of cultivation versus the entire income you get from your farm,” Abraham says. In other words, with Urban Farms, farmers don’t earn more because they sell lady finger at a higher price. They earn more because regenerative farming lowers their costs while giving them an assured buyer. A typical vegetable grower could earn as much as Rs 20,000 to Rs 30,000 more per acre annually, says Abraham, with savings increasing over time. A first-season comparison conducted by the company across 56.5 acres in Wardha, Maharashtra, found that soybean yields rose 12% and total cultivation costs fell by 8%.
Spending on farm inputs dipped from ₹9,750 to ₹5,267 per acre, while profits increased from ₹12,550 to ₹19,195. The model does not rely on government subsidies and farmers pay for the inputs themselves. According to Abraham, Urban Farms doesn’t approach farmers from a moral standpoint, or talk about climate change. “We go to them with a business proposition, and the business proposition is about making profitability.”
From trial to habit
Urban Farms’ residue-free vegetables generally cost about 40% more than conventional produce, although the gap varies by crop, market prices, and platforms. Lady finger, for instance, was priced at ₹24 for a 250gm pack on Zepto in Azadpur, in north Delhi, earlier this week compared with ₹17 for conventional produce; on Blinkit, the same pack was sold at ₹35.
Quick commerce accounts for 65% of its business under the residue-free category, with modern trade and other channels making up the rest. Abraham says part of that premium reflects the cost of maintaining a separate, traceable supply chain. The company supplies Blinkit, Zepto, Swiggy, and Flipkart as well as Reliance, Jubilant, and Country Delight, among others.
Devangshu Dutta, founder of retail consultancy Third Eyesight, says that he expects demand to grow, as incomes rise and consumers become more conscious of the food they are eating. But he thinks a 40% premium may be too high for regular consumption because vegetables, unlike coffee or craft chocolate, are staples.
“You could have a premium of maybe 20% to 30%. Some products could be higher than that, but that is something that has to be managed carefully.” For category growth to accelerate, he says, the produce must become “a fixture in the consumer’s pantry, in the consumer’s kitchen, on the consumer’s plate.”
Dutta believes that quick commerce is well-suited to fresh produce because Indian households have traditionally bought vegetables frequently rather than stocking up. “The bottleneck really is having the product range that consumers will buy over a period of time again and again.” That requires farmers growing different crops across regions and climatic zones. And building a wide range of vegetables also means working with farmers and ensuring farmer retention in the system season after season. “You don’t just sign up a farmer and say he’s going to be there forever,” Dutta says.
Urban Farms says it has managed to do that so far. In May this year, Anand Mahindra posted on X that 80 to 90% of the farmers who work with the company return every season. “Not out of loyalty to a movement, but because the economics work,” he wrote, pointing to yields comparable with conventional farming, lower input costs and produce that consistently tests residue-free.
Abraham says that Urban Farms would like to work with about 100,000 farmers by 2030, and the company’s growth will depend on how quickly it can both build and nurture relationships with its partners across the country. Applying the Araku model to a far more unpredictable market won’t be easy, but if Urban Farms can keep both farmers and shoppers in the system as it grows, coffee, as Manoj Kumar said, may indeed have been just the conversation-starter.
(Published in Firstpost)
admin
August 1, 2026
Two decades ago, the team at the Naandi Foundation turned tribal farmers in a remote Andhra valley into some of the world’s best-paid coffee growers. Araku Coffee now sells in Paris, and the best of it goes for thousands of rupees a kilogram. Now the same team is trying to do it again — this time with everyday vegetables. Their company, Urban Farms Co., works with regenerative farmers and sells their produce on apps like Blinkit and Zepto. The bet is that what worked for premium coffee can work for staples too. But vegetables aren’t coffee. They’re cheap, everyday, and something people buy all the time. Can this really scale, and does it actually leave farmers better off?
admin
July 27, 2026
Vaeshnavi Kasthuril, MINT
Bengaluru, 27 Jul 2026
Over the past six years, Trent Ltd has grown its revenue more than fivefold, outpacing Titan Co. Ltd, Tata Consumer Products Ltd (TCPL) and Voltas Ltd to become the fastest-growing established company in Tata Sons’ consumer and retail portfolio.
Trent, incorporated in 1998, is the youngest among the Tata group’s four major listed consumer businesses. Voltas was incorporated in 1954, TCPL traces its origins to Tata Tea, established in 1962, while Titan was incorporated in 1984.
While Titan remains the group’s largest consumer business by revenue, Trent has overtaken Voltas and nearly caught up with TCPL.
Trent’s revenue rose to ₹20,189 crore in FY26 from ₹3,635 crore in FY20, showed Tata Sons’ FY26 annual report. In comparison, Titan’s revenue expanded 4.2 times, while TCPL and Voltas grew 2.1 times and 1.8 times, respectively. Six years ago, Trent accounted for just 8.6% of the combined revenue of the group’s four major consumer businesses. In FY26, that share has climbed to 14.1%, close to TCPL’s 14.3%.
Trent’s portfolio includes Westside and Zudio in fashion, Samoh and Burnt Toast in newer lifestyle formats, and Star in grocery retail.
Zudio effect
The growth has been driven by Trent’s aggressive expansion across value and premium fashion. Zudio has emerged as the retailer’s biggest growth engine, benefiting from rising demand for affordable fashion among middle-income consumers, while Westside has continued to strengthen its presence in the premium apparel and lifestyle segment.
Zudio has been “a phenomenal driver of revenue growth”, with the retailer aggressively expanding the format over the past few years, said Devangshu Dutta, founder of retail consulting firm Third Eyesight.
He said Trent has also benefited from a structural shift in the country’s retail landscape as consumers increasingly move from fragmented, unorganised markets to organised retail. “The conversion from informal to formal happens not so much driven by demand but by availability. So if you open a new outlet… you have something which was not there earlier, which becomes a magnet for footfall,” Dutta said.
He said that Zudio’s combination of fashion-led products and sharp pricing has helped it stand out in the crowded value apparel market.
The retailer has simultaneously expanded beyond apparel into adjacent categories such as beauty and personal care, home décor, footwear, and accessories through Westside, while also nurturing newer concepts, including Samoh, Burnt Toast, and Star.
During FY26, Trent added 289 stores, taking its total network to 1,286 outlets across 321 cities and expanding its retail footprint to more than 17.7 million sq. ft.
The company said it sees opportunities to increase store density in existing markets while expanding into new cities, particularly as demand for organized retail continues to deepen beyond the country’s largest metropolitan areas.
The next phase of growth is likely to be driven by Westside. According to media reports, Trent plans to significantly accelerate the expansion of its flagship premium fashion chain by opening up to 100 stores annually, nearly double its historical pace. The chain, which had 300 stores at the end of FY26, is expected to expand into newer geographies, including the northeastern states, while strengthening its presence in key metropolitan markets.
Dutta said macroeconomic uncertainty, including the impact of geopolitical tensions and softer employment conditions, could weigh on discretionary spending. “If there is uncertainty, then you tend to be a little bit more careful,” he said.
Dutta said that while consumer demand may fluctuate in the short term, the long-term shift towards modern retail remains firmly intact.
Noel Tata’s farewell message
The FY26 annual report also carries Noel Tata’s final message as chairman of Trent, marking the end of an era for the retailer he helped transform into one of India’s largest fashion retailers.
Tata reiterated his long-held ambition of building Trent into a platform capable of creating and scaling multiple consumer businesses rather than relying on a single retail format. “I have long believed that Trent is not intended to be defined by a single brand, but rather by a portfolio of brands,” he wrote, adding that Westside, Zudio and Star continue to have significant runway for growth.
Looking ahead, he said Trent should aspire to build Indian brands with global relevance and generate a material share of revenues from overseas markets.
He also recalled his vision, first articulated in 2023, of making Trent ten times larger in terms of revenue with commensurate profitability, noting that the company’s revenue and profitability run rate have already grown more than 2.5 times since then.
The company has not yet named a successor to Noel Tata, who is set to retire as chairman in November.
(Published in MINT)
