Devangshu Dutta
September 28, 2017
In recent decades, the dependence on established medical disciplines has begun to be challenged. There is the oft-quoted dictum that healthcare sector tends to illness rather than health. Another saying goes that some of the food you eat keeps you in good health, but most of what you eat keeps your doctor in good health. With a gap emerging between wellness-seekers and the healthcare sector, so-called “alternative” options are stepping in.
Some of these alternatives actually existed as well-structured and well-documented traditional medical practices for thousands of years before the introduction of more recent Western medical disciplines. This includes India’s Siddha system and Ayurved (literally, “science of life”), which certainly don’t deserve being relegated to an “alternative” footnote. Ayurved is also said to have influenced medicine in China over a millennium ago, through the translation of Indian medical texts into Chinese.
Other than these, there are also more recent inventions riding the “wellness” buzzword. These may draw from the traditional systems and texts, or be built upon new pharmaceutical or nutraceutical formulations. Broader wellness regimens – much like Ayurved and Siddha – blend two or more elements from the following basket: food choices and restrictions, minerals, extracts and supplements, physical exercise and perhaps some form of meditative practices. Wellness, thus, is often characterised by a mix-and-match based on individual choices and conveniences, spiked with celebrity influences.
A key premise driving the wellness sector is that modern medicine depends too heavily on attacking specific issues with single chemicals (drugs) or combinations of single chemicals that are either isolated or synthesised in laboratories, and that it ignores the diversity and complexity of factors contributing to health and well-being. The second major premise for many wellness practitioners (though not all!) is that, provided the right conditions, the body can heal itself. For the consumer the reasons for the surge in demand for traditional wellness solutions include escalating costs of conventional health care, the adverse effects of allopathic drugs, and increasing lifestyle disorders.
After food, wellness has turned into possibly one of the largest consumer industries on the planet. Global pharmaceutical sales are estimated at over US$ 1.1 trillion. In contrast, according to the Global Wellness Institute, the wellness market dwarfs this, estimated at US$ 3.7 trillion (2015). This figure includes a vast range of services such as beauty and anti-ageing, nutrition and weight loss, wellness tourism, fitness and mind-body, preventative and personalized medicine, wellness lifestyle real estate, spa industry, thermal/mineral springs, and workplace wellness. Within this, the so-called “Complementary and Alternative Medicine” is estimated to be about US$200 billion.
There are several reasons why “complementary and alternative medicine” sales are not yet larger. Rooted in economically backward countries such as India, these have been seen as outdated, less effective and even unscientific. In India, the home of Siddha and Ayurved, apart from individual practitioners, several companies such as Baidyanath, Dabur, Himalaya and others were active in the market for decades, but were usually seen as stodgy and products of need, and usually limited to people of the older generations and rural populations. In the West they typically attracted a fringe customer base, or were a last resort for patients who did not find a solution for their specific problem in modern allopathy and hospitals.
However, through the 1970s Ayurved gained in prominence in the West, riding on the New Age movement. Gradually, in recent decades proponents turned to modern production techniques, slick packaging and up-to-date marketing, and even local cultivation in the West of medicinal plants taken from India.
As wellness demonstrated an increasingly profitable vector in the West, Indian entrepreneurs, too, have taken note of this opportunity. Perhaps Shahnaz Husain was one of the earliest movers in the beauty segment, followed by Biotique in the early-1990s that developed a brand driven not just by a specific need but by desire and an approach that was distinctly anti-commodity, the characteristics of any successful brand. Others followed, including FMCG companies such as the multinational giant Unilever. The last decade-and-a-half has also brought the phenomenon called Patanjali, a brand that began with Ayurvedic products and grew into an FMCG and packaged food-empire faster than any other brand before! While a few giants have emerged, the market is still evolving, allowing other brands to develop, whether as standalone names or as extensions of spiritual and holistic healing foundations, such as Sri Sri Tattva, Isha Arogya and others.
An absolutely critical driver of this growth in the Indian market now is the generation that has grown up during the last 25-30 years. It is a class that is driven by choice and modern consumerism, but that also wishes to reconnect with its spiritual and cultural roots. This group is aware of global trends but takes pride in home-grown successes. It is comfortable blending global branded sportswear with yoga or using an Indian ayurvedic treatment alongside an international beauty product.
Of course, there is a faddish dimension to the wellness phenomenon, and it is open to exploitation by poor or ineffective products, non-standard and unscientific treatments, entirely outrageous efficacy claims, and price-gouging.
To remain on course and strengthen, the wellness movement will need structured scientific assessment and development at a larger scale, a move that will need both industry and government to work closely together. Traditional texts would need to be recast in modern scientific frameworks, supported by robust testing and validation. Education needs to be strengthened, as does the use of technology.
However the industry and the government move, from the consumer’s point-of-view the juggernaut is now rolling.
(An edited version of this piece was published in Brand Wagon, Financial Express.)
Devangshu Dutta
January 10, 2017
In this piece I’ll just focus on one aspect of technology – artificial intelligence or AI – that is likely to shape many aspects of the retail business and the consumer’s experience over the coming years.
To be able to see the scope of its potential all-pervasive impact we need to go beyond our expectations of humanoid robots. We also need to understand that artificial intelligence works on a cycle of several mutually supportive elements that enable learning and adaptation. The terms “big data” and “analytics” have been bandied about a lot, but have had limited impact so far in the retail business because it usually only touches the first two, at most three, of the necessary elements.
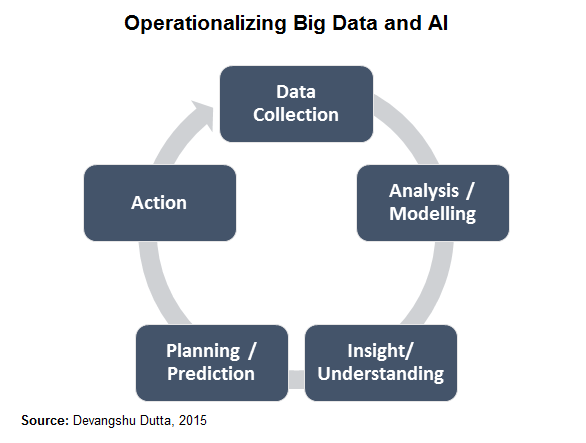
“Big data” models still depend on individuals in the business taking decisions and acting based on what is recommended or suggested by the analytics outputs, and these tend to be weak links which break the learning-adaptation chain. Of course, each of these elements can also have AI built in, for refinement over time.
Certainly retailers with a digital (web or mobile) presence are in a better position to use and benefit from AI, but that is no excuse for others to “roll over and die”. I’ll list just a few aspects of the business already being impacted and others that are likely to be in the future.
On the consumer-side, AI can deliver a far higher degree of personalisation of the experience than has been feasible in the last few decades. While I’ve described different aspects, now see them as layers one built on the other, and imagine the shopping experience you might have as a consumer. If the scenario seems as if it might be from a sci-fi movie, just give it a few years. After all, moving staircases and remote viewing were also fantasy once.
On the business end it potentially offers both flexibility and efficiency, rather than one at the cost of the other. But we’ll have to tackle that area in a separate piece.
(Also published in the Business Standard.)
Devangshu Dutta
December 29, 2016
In 2016, brick-and-mortar modern retailers seemed to have begun recovering their confidence, and cautiously investing in expansion. However, currency shortage has significantly dampened demand at the end of the year. The hangover would continue into the first half of 2017, and consumers could be muted overall on discretionary purchases, including fashion, mobile upgrades and out-of-home dining.
On the other hand, while digital transactions introduce a note of caution (friction) in the consumer’s purchase decision, for e-tailers they do reduce complexity, cash-handling costs and potential returns which could provide significant unexpected wins.
I’ve written about this for years, and don’t tire of reiterating: the retail sector must recognise that shopping is a unified activity for the consumer; physical stores and non-store environments are alternative but complementary channels. Brands can and must use whatever channel mix works for them, and brick-and-mortar retailers need to invest in creating an integrated growth blueprint towards “unified commerce”.
On their part, while e-commerce companies are constrained by FDI policy, they will need to invest more in developing “old economy” strengths – strong product differentiation and distinguishable brands. Fashion, accessories, home decor and other lifestyle products are strong drivers of gross margin for all multi-product retailers, and e-commerce players struggling on the path to profit would focus on these even more, as well as on private labels. They also need to have management teams that are able to cast their minds 3-5 years into the future, while keeping close watch on immediate cash flows. Capital is available, but turning risk-averse. All businesses need to focus on up-skilling their teams, retaining good people, improving processes and adopting technology. In recent years, growth in the retail sector seems to have been driven by a “spray-and-pray” approach, not necessarily management sophistication. Spending like there’s no tomorrow is a sure way to no tomorrow.
In short, 2017 could be the year where the entire retail sector grows up – a lot. We hope.
(This piece was published in The Hindu – Businessline on 29 December 2016).
admin
August 1, 2016

The cold chain sector is expanding quickly due to increased investments from Indian and international organisations going towards both modernisation of the existing facilities and establishment of new ventures. Over the last few years cold-chain has gained a buzz, finding its way not only into industry presentations but also into budget speeches in Parliament. It is widely reported that India needs to build more cold chain capacity, especially to reduce the enormous amount of waste of food products in the chain from farm to consumer.
India is one of the largest producers of agro-products i.e. fresh fruits and vegetables, milk and related products, fishery products and meat. However, due to lack of the required facilities, spoilage of products is comparatively high.
In recent years, significantly incentivised both by business logic and by tax breaks, there has been a fair amount on investment in cold storages. However, the sector is still highly fragmented; there is inequitable distribution of cold storages, interlinkages between storages is also very poor and many facilities are also operating below capacity.
The National Centre for Cold Chain Development (NCCD) reported that as of December 2014, 70% capacity was utilised, where the total number of cold storages available in India was around 5300 and approximately 6000+ vehicles, providing about 30 Million Metric Tonnes capacity of storage. Most of these facilities are located in the states of Uttar Pradesh, Uttaranchal, Punjab, Maharashtra and West Bengal.
Storage and transportation capacity is only the very first step in strengthening cold chain capabilities but, unfortunately, that is where many entrepreneurs and investors in cold-chain are stopping their thought process. Many players in the industry have been using obsolete machinery, and storages are majorly for a single commodity. The result, predictably, is underutilisation of capacity or mishandling of food products leading to operational problems, cost escalations, spoilage and other losses. Just to mention a simple example that many seem to forget: even domestic refrigerators have at least 3-4 temperature-humidity zones: the freezer, the chill tray, the large cool area, and a vegetable tray. In comparison, many cold stores are built without adequate thought to the various influencing factors. It’s important to recognise that in developing a cold chain capability, the products to be handled, the environment in which the cold chain will operate, not only storage but intake, handling and transportation, all have a role to play.
With a fragmented operating environment, both in terms of production as well as distribution, often a single investor or company may not be able to create the business logic to set up a cold chain facility. Collaboration between multiple individuals and agencies may be a way out.
An example of successful use of integrated cold chain is the Tamil Nadu Bananas Growers Federation. Banana growers in the Tamil Nadu belt were diminishing due to lack of appropriate storage facilities, and farmers were forced to sell produce at throw away prices. With introduction of integrated cold chain solutions, the federation of farmers from Tamil Nadu has now managed to gain a hold of the banana market again. They have managed to increase their income manifold by growing better qualities and storing bananas for longer period of time in the integrated cold chains.
Cold chain logistics in the true sense begin with harvesting and post-harvest handling, going on to controlled atmosphere vehicles, cold storages, sorting and grading facilities, modern pack houses and controlled atmosphere retail stores. Most importantly, even operational know-how is something that is not made part of the investment plan, leading to unviable, unprofitable cold chain facilities.
The focus should be to integrate the cold chain, and also build capacities in all areas. As per NCCD (December 2014), India has approximately 6,000 reefer vehicles against a requirement of 60,000. Similarly the number of pack houses available is 250 and the projected requirement is for 70,000. Hence, the need for a more balanced investment in terms of modern pack-houses, refrigerated transport units and ripening chambers is evident and will bring far better results, both operationally and financially.
In addition, there has to be a significant improvement in developing the know-how and skills sets available to the sector. While the country is faced with large-scale unemployment annually, a well-thought out development of the cold chain sector including due investment in knowledge-based initiatives can create significant numbers of better paying jobs around the country, especially in rural areas from where the produce is sourced.
With development of the consumer and retail sector supporting its growth, integrated cold chain development should be at the top of the agenda for government as well as for private business.
Devangshu Dutta
January 15, 2016

Retailers seem to be fighting a losing battle against the growth of ecommerce, and it is only the nature of the shopping activity, especially for fashion – interactive, social, and immersive as it is – that has kept many retailers relevant and in business.
However, the defensive stance is changing, and now they’re using technology to get the customers back into the store. Forward-thinking retailers are reimagining trial rooms, stores, business processes and entire business models. It’s not a physical versus virtual approach but an approach that integrates both sides. The idea is to create a more immersive experience than pure digital retail can be, using some of the same tools as ecommerce.
It is important to remember that the whole retail environment is a “suggestive” environment. Due to cost and other operational factors most retailers are ill-equipped to provide appropriate levels of excitement, suggestion and support during the browsing and buying process.
For many, the simplest move could be screens serving up their catalogue to customers within the store. For instance, US department store chain Kohl’s has initiated connected fitting rooms that identify products the customer is carrying, and bring up not only those items onscreen, but additional colours and sizes that are available. If the customer wants an alternative, a message goes to a sales associate who can fetch the requested option. Macy’s and Bloomingdales are using tablets in the trial rooms, while Nordstrom, Neiman Marcus and Rebecca Minkoff are attempting to boost their fashion sales using magic mirrors to provide similar enablement. These devices and the processes empower and involve the customer far more, while leaving store staff free for other activities.
A step up, Puma is using “virtual trials” for its apparel products by having a customer take images of herself in specific positions, and then mapping styles on their own images to visualise how they might look. While this needs more work and investment, this is still only a more developed product browser technique from the customer’s point-of-view.
The next level, augmented reality trials and virtual fit, are significantly more sophisticated at creating simulations of a selected garment image draping and falling on the customer’s body even as he or she moves normally. Imaging and texturing of the simulated garments is technically challenging and expensive, repeated for each new style and option. The imaging also needs to mimic the “wearer’s” movements. Nevertheless, retailers such as Polo Ralph Lauren are finding it worth their while to investigate these new technologies, as these reintroduce the much needed “theatre” that are integral to a successful retailer.
For the customer virtualisation expands the number of items “taken” into the trial room, and creates more convenient product discovery. More products can be seen in the same shopping time, and sharing of images and videos with friends and family, engages them in the shopping process as well.
For retailers, the benefits multiply. Inventory can be optimised, and there is reduced handling and shrinkage. Even without sales associates, it is feasible to prompt for alternatives and related products, improving conversion and transaction values, reducing space and costs of physical trial rooms, and increasing the number of customers serviced especially at peak traffic times.
A phenomenal advantage is the data captured that is relevant while the customer is in the store, but which can be linked to future promotions. Valuable intelligence, such as what is being tried and for how long, can help the retailer to quickly gauge demand patterns, and adjust pricing and promotions. Normally retailers only capture sales transactions (post-fact), and miss out the rich information on in-store behaviour that etailers do collect and analyse.
However, massive hurdles to virtualisation remain, including data input accuracy, product accuracy, and the technical capabilities of the tech solution adopted. A bigger concern is whether technology is intuitive and seamless, or whether it gets in the way of the shopping experience. Further, consumers do have privacy concerns about the images and other data collected.
Its important to remind ourselves that, on its own, technology is just a novelty – huge transformation of business processes, organisational capabilities and behaviours must happen as well.
That is perhaps the biggest mountain to climb.
