Devangshu Dutta
January 5, 2010

If we were to look at phrases that have cropped up during the recent recessionary times in the consumer goods sector, “private label” has to be among those at the top of the list.
From clothing to cereals, toothpaste to televisions, there is hardly a category that has not seen retailers trying their hand at creating own labelled products.
The first motivation for most retailers to move into private label is margin. On first analysis, it appears that the branded suppliers are making tons of extra money by being out there in front of the consumer with a specific named product. The retailer finds that creating an alternative product under its own label allows it to capture extra gross margin. Typically the product category picked at the earliest stage of private label development would be one for which several generic or commodity suppliers are available.
At this early stage, the retailer is aiming for a relatively predictable, stable-demand and easily available product whose sales would be driven by the footfall that is already attracted into the store. A powerful bait to attract the customer is the visible reduction in price, as compared to a similar branded product. If the product can be compared like-for-like, customers would certainly convert to private label over time.
However, maintaining prices lower than brands can also be counter-productive. In many products, while customers might not be able to discern any qualitative difference, they may suspect that they are not getting a product comparable to one from a national or international brand. And while private label can drive off-take, the price differential can also erode gross margin which was the reason that the retailer may have got into private label in the first place. Over time, such a strategy can prove difficult to sustain, as costs of developing, sourcing and managing private label products move up.
The other strong reason a retailer chooses to have private label is to create a product offering that is differentiated from competitors who also offer brands that are similar or identical to the ones offered by the retailer. Department stores, supermarkets and hypermarkets around the world have all tried this approach – some have been more successful than others. The idea is to provide a customer strong reasons to visit their particular store, rather than any of the comparable competitors.
Of course, when differentiation is the operating factor, the products need more insight and development, and closer handling by the retailer at all stages. A price-driven private label line may be sourced from generic suppliers, but that approach isn’t good enough for a line driven by a differentiation strategy. In this case, costs of product development and management increase for the retailer. However, to compensate, the discount from a comparable national brand is not as high as generic nascent private label. In fact, some retailers have taken their private label to compete head on with national brands – they treat their private labels as respectfully as a national branded supplier would treat its brand.
So what does it take to go from a “copycat” to being a real brand?
Third Eyesight has evolved a Private Label Maturity Model (see the accompanying graphic) that can help retailers think through their approach to private label, whether their product offering is dominated by private label, or whether they have only just begun considering the possibility of including private label in their product range. The model sketches out a maturity path on five parameters that are affected by or influence the strength of a retailer’s private label offering:
In some cases, retailers may have multiple labels, some of which may be quite nascent while others might be highly evolved, clear and comparable to a national brand. This could be by default, because the labels have been launched at different times and have had more or less time to evolve. However, this can also be used as a conscious strategy to target various segments and competitive brands differently, depending on the strength of the competition and their relationship with the consumer.
The interesting thing is that size and scale do not offer any specific advantage to becoming a more sophisticated private label player. Some extremely large retailers continue to follow a discounted-price “me-too” private label strategy where even the packaging and colours of the product are copied from national brands, while much smaller players demonstrate capabilities to understand their specific consumers’ needs to design, source and promote proprietary products that compare with the best brands in the market.
For a moment, let’s also look at private labels from the suppliers’ point of view. As far as we can see, private label seems to be here to stay and grow. Suppliers can treat private labels as a threat, and figure out how to ensure that they retain a certain visibility and relationship with the consumer. On the other hand, interestingly, some suppliers are also looking at private label as an opportunity. They see the growth of private label as inevitable, and would much rather collaborate in the retailer’s private label development efforts. This way they can maintain some kind of influence on the product development, possibly avoid direct head-on conflict with their own star branded products and, if everything else fails, at least grab a share of the market that would have otherwise gone over to generic suppliers.
If you are retailer, I would suggest using the Private Label Maturity Model to clarify where you want to position yourself, and continue to use it as a guide as you develop and deliver your private label offering.
If you are a supplier concerned about private label, my suggestion would be to gauge how developed your customer is and is likely to become, and ensure that you are at least in step, if not a step ahead.
Of course, if you need support, we’ll only be too happy to help! (Contact Third Eyesight to discuss your private label needs.)
Devangshu Dutta
January 4, 2010
Prompted by an article in the New York Times, Bernice Hurst, Contributing Editor of RetailWire, brought up an interesting subject to discuss – the tradition of small, independent retailers on Manhattan’s Lower east side, their survival despite the recession, and their determination to thrive.
One of the retailers interviewed for the article said that the business was “so much fun”. In referring to the kind of products she was developing said, “there are no boundaries to these things”.
Imagination may have no boundaries, but markets always do. When you’re small fry the pond seems limitless. And if all is in harmony (no tuna to gobble you, all fry remaining small, enough algae to feed off, forever), then the market is a good and boundless place. If only.
Personally, I hope there will always be some ponds with room in them to let such small fry bubble up their innovations: they keep the fashion business alive.
They also serve to remind us that there are reasons for running business that are not based on the race-to-scale.
The New York Times article is here – Yes, We’re Open – and the Retailwire discussion is here – Manhattan Still Home to Independent Retailers.
Devangshu Dutta
October 8, 2009

Here is a summary of the Sustainable Fashion Forum, and some more pictures from the afternoon.
And here is a previous article on sustainability and corporate responsibility.
admin
May 9, 2009
By Devangshu Dutta, Tarang Gautam Saxena
While the Indian consumers have aspired to own international fashion brands, India’s large population base in turn has been an aspirational market for the international companies.
To remote observers, the Indian market may appear to be a virgin territory as far as international apparel and footwear brands are concerned. But India has seen the presence of international brands for almost a century, including mass brands such as Bata and luxury brands such as Louis Vuitton. However, as the colonial government systematically repressed local textile production, the local resistance to foreign products grew as well. Therefore, until the 1980s, the presence of international fashion brands was negligible.
In the early 1990s, as the Indian economy opened up again, a few international fashion brands entered the Indian market. The pioneering companies during this stage were Benetton, Coats Viyella and VF Corporation.
At this time the Indian apparel market was still fragmented, with multiple local and regional labels and very few national brands. Ready-to-wear apparel was prevalent primarily for the menswear segment which was thus a target for many international fashion brands (such as Louis Philippe, Arrow, Allen Solly, Lacoste, Adidas and Nike).

In the midst of this the media industry was also witnessing a high growth which aided the international brands in gaining visibility and establishing brand equity in the Indian market.
The late-1990s marked a significant milestone in the growth of modern retail in India. Higher disposable incomes and the availability of credit significantly enhanced the consumers’ buying power. A growing supply of good-quality retail real estate in the form of shopping centers and large format department stores also allowed companies to create a more complete brand experience through exclusive brand stores and shops-in-shop.
The number of international brands continued to grow each year at a steady pace until the early 2000s, and took off exponentially thereafter. By 2005 the number of international fashion brands present in India was over three times compared to that in the mid 1990s. The last few years (since 2005) have continued the significant growth of international fashion brands, including luxury brands such as LVMH, Aigner, Tommy Hilfiger and Chanel.
The Popular Entry Strategies
Many of the international companies entering India in the late 1980s and 1990s chose licensing as the entry route to India to gain a quick access to the Indian market at a minimal investment.
A few companies such as Levi Strauss set up wholly owned subsidiaries while others such as Adidas and Reebok entered into majority-owned joint ventures. This helped them to gain a greater control over their Indian operations, sourcing and supply chain, and brand.
In the subsequent years import duties for fashion products successively came down making imports a less expensive sourcing option and the realty boom brought investors in retail real estate that were ideal franchisees for the international brands. By 2003, franchising became the preferred launch vehicle for an increasing number of international companies, while only a few chose to enter through licensing.
In 2006 the Government of India reopened retail to foreign investment (allowing up to 51 per cent foreign direct investment in “Single Brand” retail). Using this route, many brands have entered India by setting up majority owned joint ventures, or transitioned their existing franchise arrangements into a joint venture structure.
The Entry Structure for Some International Brands
| Entry Strategy | Time Period | ||
| 1980s or Earlier | 1990s | Post-1999 | |
| Licensed | Louis Philippe, United Colors of Benetton and 012, Wrangler | Allen Solly, Arrow, Jockey, Lacoste, Lee, Nike, Van Heusen, Vanity Fair | Puma |
| Wholly Owned Subsidiary | Bata, Pepe Jeans | Levi’s® | Hanes, Triumph |
| Joint Venture (Majority) | Adidas, Reebok | Diesel, Nautica, Sixty Group | |
| Franchise or Distribution | Aldo, Burberry, Canali, Versace, Debenhams, Esprit, Gucci, Guess, Hugo Boss, Mango, Marks & Spencer, Mothercare, Tommy Hilfiger | ||
| Joint Venture (incl. Minority Stake) | Celio, Etam, Giordano | ||
Source: “Global Fashion Brands: Tryst with India” (A Report by Third Eyesight) © Third Eyesight, 2009
Note: The above table shows the structure used during entry, and not the structure that exists currently.
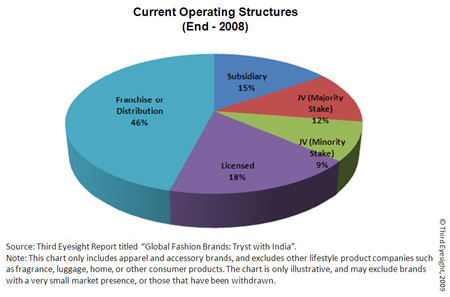
By the end of 2008, just under half of the brands were present through a franchise or distribution relationship, while over a quarter had either a wholly-owned or majority-owned subsidiary. These structures allowed the brands to have greater control of operations, particularly of product.
Shifting Strategies
Many international companies have evolved their presence in India into structures different from those at the time they entered the market.
A good example depicting the shift in business strategy is that of VF Corporation which entered India in 1980s by assigning the Wrangler license to Dupont Sportswear. Since then it has launched a variety of brands in different product categories with number of Indian partners and finally formed a joint venture, VF Arvind Brands Pvt. Ltd., with Arvind Brands.
Another example of a company that has evolved its presence is Benetton, which first entered India through a licensee (Dalmia). Benetton then transitioned in 1991 into 50:50 joint-venture and finally in 2004 took over the Indian business completely. However, it adopted the franchising route in 2006 for its premium fashion brand, Sisley, appointing Trent (a Tata Group company) as the national retail franchisee.
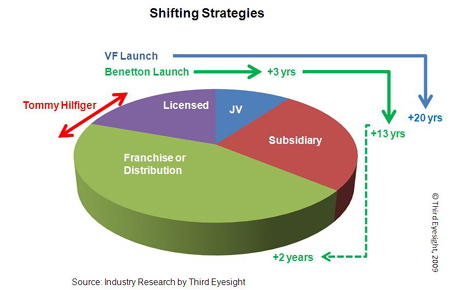
Many other companies such as Nike, Tommy Hilfiger, Marks & Spencer and Pierre Cardin (as described in our report “Global Fashion Brands: Tryst with India”) have changed their approach as the original structures did not perform as well as they had expected.
Obviously, each such change has cost the brands time, management effort, money and, sometimes, market share.
We believe that these shifts and the pain related to it could have been reduced, had the brands ruthlessly questioned the motivation for considering this market and their expectations from the market in determining an appropriate strategy.
What’s Ahead?
In the midst of economic upheaval around the world, how does India look as a market for international fashion brands?
Well, it is difficult to generalize even in the best of times. In the current global turmoil there is certainly a lot more unpredictability about international expansion for most companies.
Although India’s position as a target market for international brands has been improving, as is evident from the number of launches in the last 6-7 years, some companies considering international expansion may prefer entering other markets that may seem more “familiar”, developed and safe (such as Europe, Japan, South Korea or Taiwan). Against such comparisons, India’s growing but fragmented market can seem chaotic and difficult to deal with.
However, the fact remains that there are very few markets globally that can provide the sustained size of mid-term and long-term opportunity that India does. We are already seeing the more far-sighted and committed brands consolidating their position and presence in the market by continuing to look at expansion, even while examining how they can make their existing points of sale perform better. We also constantly come across new companies carrying out investigations into the market.
In the current environment we expect to see a shift in the nature of launch vehicle. While franchising seems to be a safe option for risk-averse brands in the current times, we will probably see more brands with a long term strategy, who would establish a controlled presence either through joint-ventures or through wholly-owned subsidiaries, since they can lay the foundation of the business today at much lower costs today than in the past few years.
India’s foreign direct investment (FDI) policy, allowing FDI only up to 51% in retail trading of “Single Brand” may have held back some fashion brands as they are still managed by owner founder with a conservative outlook on “control”. However, in the last couple of years, we have found companies not being deterred by the barriers to FDI.
As their comfort and familiarity with India has grown, international companies are more willing today to create corporate structures that allow them a presence in the market today and a step-through to a more controlling stake as and when government regulations allow.
All in all, we feel that international brands are in India not only to stay, but also to expand. There is yet a lot of potential untapped in the market, and as the integration of the Indian consumer with global trends continues, international brands can expect to find India an increasingly fertile ground for growth.
(c) 2009, Third Eyesight
Devangshu Dutta
April 16, 2009
The recession is taking a toll on the business models of premium and luxury retailers.
According to the Los Angeles Times, faced with sales declines at their full-price stores, Neiman Marcus, Saks Fifth Avenue and Nordstrom are lavishing more dollars and devotion on their outlets which are performing better than their traditional stores.
According to Robert Wallstrom, president of Off 5th, Saks Inc.’s outlet division, “These days, customers are saying they want a brand, customer service and a deal.”
Outlets may just be the lifeboat needed by some of the brands to get through the current downturn, with the mix of the “real steal” deals to get the footfalls and the “just a little off the top” to get the margin. The current outlet stores are good enough to avoid severe damage to the brand.
However, a critical question does remain unanswered: once the consumer becomes used to shopping at a certain price level, might some brands struggle to move back up the curve?

