
Tarang Gautam Saxena
June 27, 2011
In most conversations we have had with international brands in the last 2-3 years, India consistently appears on list of the top-5 markets in which to expand into.
The second most populous country in the world, India has a young population that offers a vibrant population mix that will provide a workforce and consumers in decades to come. There is steady growth in per capita income and a greater availability of credit, as well as a significant change in the consumers’ outlook to life that has propelled consumption levels.

The United Nations Conference on Trade and Development ranked India as the second most attractive destination for global foreign direct investments in 2010. The lowest recorded GDP growth rate during the global slowdown was still a decent 6.7 per cent. This growth rate is expected to have returned around 9 per cent in 2011, and is driven by robust performance of the manufacturing sector, as well as government and consumer spending.
The ongoing opening up of the economy over two decades and its robust growth has steadily attracted brands and retailers into the country. Many of them have now been in the country since the early 1990s, and the numbers have grown exponentially during the last 8-10 years. Despite this, the market is far from saturation and many more international brands are actively scouting the market.
Many of them are value brands in their home markets and may, therefore, be more a logical fit into a “developing” market, but there are also plenty of premium and luxury names on the list. For instance while the growth has largely been led by soft goods product brands, as incomes have grown, the presence of more expensive consumer durable brands has also expanded.

While the journey to the Indian market has not been a smooth ride even for the well established and successful international brands in the market, brands that have invested in understanding the psyche of the Indian consumer, adopted flexibility in market approach and displayed persistence, have been paid off handsomely.
Some international brands have exceeded domestic brands in size and reach, while others have had to reconcile to being niche operators. Some have seen profits while others may have their senior management wondering what fit of madness brought them to tackle this market where they can only dream about making money sometime in the future.
Typically, when looking at a new market the very first question anyone would ask is: what is the market potential for brand?
However, you should also be prepared to ask yourself: what need is the brand addressing and what is the value being offered by the brand? How would it be able to effectively and efficiently deliver that value? In many cases, for those entering a non-existent product category a more basic question is: “Is there a need for my product offer?” Just because a brand is huge somewhere else in the world does not automatically make it desirable to the Indian consumer.
While most brands want to target the Indian middle-class millions, their sourcing structure and strategy places them out of the reach of most of the population. Brands that have succeeded in creating a significant presence, maintaining their brand image and having a sustainable operating model have, almost uniformly had a significant amount of local manufacturing. Notable examples from fashion include Bata, Benetton, Levi Strauss, Reebok, among others. In case of certain food brands such as Domino’s and McDonald’s, the companies have collaborated with and developed their vendors locally to bring down costs, and improve serviceability.
Apart from the costs and margins, another important issue is that of the adaptability of the product mix. Brands that are sourcing locally and have a significant product development capability in India are also able to respond to specific needs of the Indian market better, rather than being driven by what is appropriate for European or North American markets. This is an enormous advantage when you are trying to be “locally relevant” to the consumer in an increasingly cluttered marketplace.
Indeed the question is more to do with the brand’s willingness and capability to create a product mix that is most suitable for India through a blend of international and India-specific merchandise. The famous “Aloo-tikki” burger by McDonald’s is a great example of a product specifically developed for the Indian consumers. Not just that, India is probably McDonald’s only market in which its signature dish, the Big Mac, is not sold.
Of course, flexibility in tweaking the product to suit Indian market can become a concern when it amounts to losing control over the brand direction, and mutating away from the core proposition that defines the parent in the international market. Many brands wish to control every aspect of product development head office, but this also severely limits their ability to respond to local market needs and changes. A one-size fits all strategy obviously will limit the number of consumers that the brand can effectively address in a market such as India.
Another key question is: what is the degree of control that a brand wants to exercise on the brand, the product, the supply chain and the retail experience of the consumer? The corporate structure itself may be determined by the internal capabilities and strategies of the international brand in their home market or other overseas markets. A brand that has presence through a wholesale business in the home market may not have internal capability or experience in retail, and would look for an Indian partner who can fill in the gap.
Based on whether they want direct operational control over store operations, international companies can set up fully owned subsidiaries or joint ventures to manage the business in India. Many brands prefer to take a slow and steady approach as they do want to exert a significant amount of control over the business (including companies such as Inditex, the owner of Zara, and other retailers such as Wal-Mart and Tesco), entering only when they are fairly confident of being able to closely manage the business in India right up to the retail store.
During our work we have come across both extremes – companies that want to manage the minute details of the India business out of their own head offices, as well as companies that are so hands-off that they only want to hear from their franchisee or licensee when things are especially good or particularly bad. While a balanced, middle-of-the-road approach would be the logical one in each case, in reality individual styles of the top management have a huge influence on the approach actually taken. Also, the size of the potential market segment – relevant to the brand – has an important role to play in the strategy. If the brand is meaningful only to a small segment of the population, or priced at the top-most end of the market, one company may choose to establish an exploratory distribution relationship, while another might choose to set up an owned presence rather than look for an Indian partner to handle their small business.
While perfect partnerships seldom exist, companies could be a lot more careful we have found them to be, in questioning the criteria and motivations for choosing partners. In some cases, financial strengths, or past industrial glory were qualifying factors for picking franchisees, and the relationships have failed because the business culture was divergent from the Principal’s. In other cases, partners have been picked because they “have real estate strengths”, but no consideration has been paid to whether the partner has the operational skills to manage a fashion brand.
On several occasions, franchise relationships and joint ventures have split because one or both partners find that their expectations are not being fulfilled, or the water looks deeper than it did when they got into the business.
The opportunities in India are many. As the managing director of one international brand commented in a conversation with Third Eyesight, India is a market where a brand can enter and live out an entire lifetime of growth.
However, international brands do need to carefully identify what role they wish to play in the market, and what capability and capacity they need operationally to create the success that can truly root a brand into the rich Indian soil.
admin
January 7, 2010
By Tarang Gautam Saxena, Chandni Jain and Neha Singhal
In Retrospect
While India was a promising market to many international brands, it was not completely immune from the global economic flu. More than its primary impact on the economy, the global downturn sobered the mood in the consumer market. Even the core target group for international brands, that had just begun to splurge apparently without guilt, tightened their purse strings and either down-traded or postponed their purchases.
In 2008 in the midst of economic downturn, skepticism and uncertainty, the international fashion brands had continued to enter India at nearly the same momentum as the previous year. Many international brands such as Cartier, Giorgio Armani, Kenzo and Prada entered India in 2008 targeting the luxury or premium segment. However, given the high import duties and high real estate costs, the products ended up being priced significantly higher than in other markets. Many players ended up discounting the goods heavily to promote sales while a few also gave up and closed shop.
As the Third Eyesight team had foreseen last year, 2009 saw a further slowdown and fewer international brands being launched during the year. The brands that were launched in 2009 included Beverly Hills Polo Club, Fruit of the Loom, Izod, Polo U.S., Mustang, Tie Rack and Timberland. Some of these had already been in the pipeline for quite some time and invested a considerable time and effort in understanding the dynamics of the Indian retail market, scouting for appropriate partners, building distribution relationships and tying up for retail space, setting up the supply chain and, most importantly, getting their operational team in place.
International Fashion Brands in India

After many deliberations, the well-known global brand Donna Karan New York set foot in the Indian market in 2009 through an agreement with DLF Brands to set up exclusive DKNY and DKNY Jeans stores India. The brand is also reported to have signed a worldwide licensing agreement with S Kumars Nationwide Ltd to design, manufacture and retail DKNY menswear in certain specific countries.
Second Chances
Amongst the international brands that have recently entered the Indian market, a few are on their second or even third attempt at the market.
For instance, Diesel BV initially signed a joint venture agreement in 2007 with Arvind Mills, and the partnership intended opening 15 stores by 2010. However, by the middle of 2008, the relationship ended with mutual consent, as Arvind reduced its emphasis on retailing international brands within the country. Within a few months of the ending of this relationship, Diesel signed a joint venture with Reliance Brands for a launch scheduled for 2010. Both partners seem to be strategically aligned with a common goal as the international iconic denim brand wants to take on the Indian market full throttle and the Indian counterpart has indicated that it wants to rapidly build its portfolio of Indian and foreign brands in the premium to luxury segments across apparel, footwear and lifestyle segments.
Similarly, Miss Sixty entered India in 2007 through a franchisee agreement with Indus Clothing. It switched to a joint venture with Reliance Brands in the same year but the partnership was called off in 2008, despite plans to open more than 50 stores in the first three years of operations. Miss Sixty has finally entered India through a franchise agreement with a manufacturer of women’s footwear and accessories. The company has currently introduced only shoes and accessories category and is looking at potential partners for its label Energie and girls’ range Killah.
Other brands that have re-entered the Indian market include Germany-based Lerros whose first presence in India was back in mid-1990s. The brand re-entered the market in 2008 through own brand stores and is growing its presence through this route as well as through multi-brand stores.
Oshkosh B’gosh is another brand that had entered India in mid 1990s, through a licensing agreement with Delhi based buying house, Elanco. The licensee found the childrenswear market hard to crack, and closed down. In 2008, Oshkosh re-entered the Indian market through a licensing partnership with Planet Retail and is now available through shop-in-shop counters at Debenhams stores. Reports suggest that it may consider setting up exclusive brand outlets.
During the turbulence of 2008 and 2009, a few brands also exited the market. Some of them were possibly due to misplaced expectations initially about the size of the market or about the pace of change in consumer buying habits. Others were due to a failure either on the part of the brand or its Indian partners (or both) to fully understand what needed to be done to be successful in the Indian market. Whatever the reason, the principals or their partners in the country decided that the business was under-performing against expectations and for the amount of effort and money being invested, and that it was better to pull the plug.
Some brands that have been pulled out of the Indian market during 2008 and 2009 include Dockers, Gas, Springfield and VNC (Vincci). Gas (Grotto SpA) is reported to remain interested in the market but has not found another partner after its deal with Raymond fell through in 2007 and all dozen of its standalone stores were shut down.
The Scottish brand Pringle and its Indian licensee did not renew their agreement upon its expiry. The Indian partner has reportedly signed an agreement to launch another international brand in India, while Pringle is said to be looking for new licensee.
The good news is that successful relationships outnumber every exit or break in relationship possibly by a factor of ten. Some of the brands that have sustained are among the early entrants having a presence in India since the late-1980s and 1990s or even earlier. These include Bata, Benetton, adidas, Reebok (now also owned by adidas), Levi Strauss and Pepe. Having grown very aggressively during 2006 and 2007 Reebok quickly became the largest apparel and footwear brand in India, while Benetton and Levi’s are expected to cross the $100-million mark for sales this year.
Entry Strategy & Recent Shifts
As envisaged in Third Eyesight’s report from a year ago, with changing market conditions and a growing confidence in the Indian market, there has been a shift among international brands in the choice of the launch vehicle. While franchising has been the preferred mode of market entry in the recent past for risk-averse brands, more brands today demonstrate a long-term commitment to the Indian market, and are choosing to exercise ownership through wholly or partially owned subsidiaries and through joint ventures.
In 2009, we have seen a noticeable shift in favour of joint-ventures as the choice for entry into the market. Even the brands already present are looking to modify the nature of their existing presence in India in order to exert more control over the retail operations, products, supply chain and marketing.
Current Operating Structure
(End 2009)
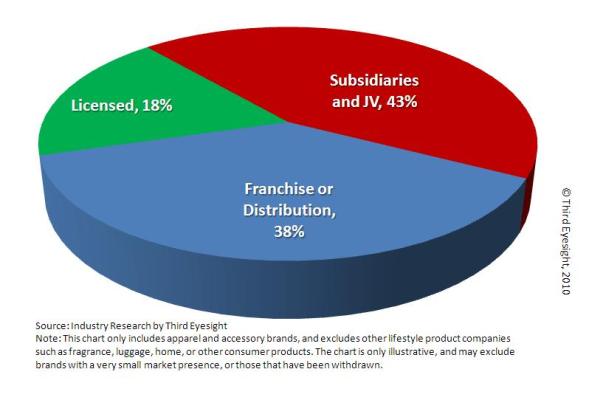
Brands that changed their operating structures and, in some cases partners, in recent years include VF (Wrangler, Lee etc.), Lee Cooper, Lee, and Louis Vuitton amongst others.
Mothercare, the baby product retailer, which is present through a franchise agreement with Shopper’s Stop has, in addition, recently formed a joint venture with DLF Brands Ltd to enable the expansion through stand-alone stores. Gucci, which had initially entered in 2006 with the Murjani Group as a franchisee, has recently changed over to Luxury Goods Retail, and is now in the process of restructuring the relationship into a joint venture.
VF has also been reported to be looking to license Nautica, Jansport and Kipling to a new partner. Until now, these brands were handled through the joint venture with Arvind Brands. Arvind has increasingly focused on its core business, closed stores and scaled down expansion plans for the international brands.
Burberry that had entered India in 2006 through a franchisee arrangement with Media Star opened two stores under this arrangement. It has now set up a new joint venture with Genesis Colors and plans to open 20 stores across the country.
More recently Esprit has also been reported to have approached Aditya Birla Nuvo to deepen its engagement by moving from its distribution arrangement into joint venture as the international brand sees excellent potential in the Indian market.
Buckling up for 2010
Throughout 2009, the one fact that became clear was that the Indian market was resilient. Now, as the global economic condition stabilizes, confidence levels of brands and retailers in India have also improved.
Several launches are already expected in 2010, and possibly many more are being worked upon. In the following 12 months, consumers can expect to find within India acclaimed brands such as Diesel, Topman, Topshop and the much-anticipated Zara. Many more Italian, British and French brands are examining the market.
Most of the international fashion brands already present in the market are also projecting a cautiously upbeat outlook in their plans, while a few are looking positively bullish.
For example, Pepe, an old player in premium and casual wear segment, has reported plans to grow its retail network further and open 50 more franchise stores by September 2010. Similarly the German fashion brand S. Oliver that entered the Indian market in 2007 is looking to grow significantly. It has already moved from a franchise arrangement with Orientcraft to a joint-venture with the same partner, and has stepped up its above-the-line marketing presence. The brand has recently reported its plans to scale up its retail presence to 77 stores by the end of 2012 while also strengthening its presence through shop-in-shop in multi-branded outlets in high potential markets.
Those international brands that have tasted success have not achieved it by blindly importing business models and formulas from other markets. Most have had to devise a different positioning from their home markets. Some have significantly corrected pricing and fine-tuned the product offering since they first launched. These include The Body Shop which decreased its prices by up to 30% this year, and Marks & Spencer which reduced prices by 20-40%. Others are unearthing new segments to grow into; for instance, Puma and Lacoste are now seriously targeting womenswear as a growth market.
On the operational side, the good news for retailers and brands is that the average real estate costs have reduced significantly, although marquee locations remain high. In several locations lease models have also moved from only fixed rent to some form of revenue sharing arrangement with the landlord. And, while the sector has seen some employee turmoil as many non-retail executives who came into the business in the last 5-7 years have returned to other sectors, employee salary expectations are also more realistic.
As customer footfall and conversions pick up, international brands are also shoring up their foundations for future expansion in terms of better processes and systems, closer understanding of the market, and nurturing talent within their team. Third Eyesight’s recent work with international brands’ business units in India highlights the international players’ concern with ensuring a consistent brand message, improved organizational capabilities right down to front-line staff, and focus on unit productivity (per store and per employee).
We may yet see a few more exits, and possibly some more relationships being reshuffled and partners being changed. However, all things considered, we can look forward to a net increase in the number of international brands in the country.
The Indian consumer is certainly demonstrating more optimism and as far as there are no major unforeseen global or domestic shocks, this optimism should translate into a healthier business outlook for international brands as well. According to early signs, 2010 could be an excellent curtain-raiser for a new decade of growth for international fashion brands in India.
[The 2009 report is available here: “International Fashion Brands – India Entry Strategies”]
(c) 2010, Third Eyesight
[Note: This report is based on information collected from a combination of public as well as proprietary sources, and in some cases may differ from press reports. However, no confidential information has been shared in this report.]
