
Devangshu Dutta
May 31, 2010
Are you being carried, or are you carrying others?
To know the answer to that question, bear with me while I take you on a short mental journey through the emerging landscape of “ethical business” and to the stories at the end of this piece. (Okay, you can cheat and skip ahead, but I would really prefer you to read through the whole thing.)
For the most part sustainability and responsibility – or “corporate social responsibility” (CSR) to use the proper jargon – is seen as more relevant to the western economies, rather than the emerging economies like China, India and Brazil.
The pressure to do the ‘right thing’ is like a carpenter’s vice, whose one jaw is public opinion and the other is regulation, together squeezing ever tighter on corporate business. Clearly, there is a significant portion of customers in western markets who are vocal in expressing their opinions on business practices that are seen as wrong or unethical. On the other side, judicial implementation of regulations is also extremely stringent.
In fact, in the last 10-15 years CSR and sustainability have become far more important to top management in western economies since the real penalties in terms of negative impact on the brand and financial penalties through regulation and litigation are extremely high. Multi-billion dollar businesses certainly have much at risk, as demonstrated by well-documented PR disasters of large brands and retailers in the last decade or so. The variety of issues they have faced has covered sweatshop factories, child-labour, product safety, food adulteration and many others.
Since the mid-1990s there has been a steady increase in CSR initiatives, or at least an increase in initiatives that are labelled under the CSR umbrella. There is no doubt that there is good intent behind many CSR initiatives.
Some of these are focussed on improving the core business processes and practices of the company, and have measurable improvement goals that also have a positive impact beyond the company itself. These can truly be called socially-responsible corporate initiatives.
However, one can’t help but question many others which are fuzzy in their impact on both within the business and outside. The motivation of this type of initiative seems to be a two-pronged PR effort: firstly to get positive PR for “good work” mostly unrelated to the business and secondly, more importantly, to avoid negative PR for poor or questionable business practices in the company’s mainstream products or services.
Lest I sound too cynical about the corporate efforts, let me say this: there is also lack of clarity and agreement in non-corporate circles about what constitutes “corporate social responsibility” or “responsible business”. The label is relatively new to mainstream management thinking and very mutable. Social responsibility, ethical business, sustainability are all terms that are broad-based, used interchangeably, and are open to interpretation which can change with the context. (I wrote about this in an earlier column “Corporate Responsibility – Beyond Babel” about 18 months ago.)
And that brings me to four separate incidents that happened recently, which are (in hindsight) neatly threaded together with a common thought process. (Thank you for your patience so far!)
The first was a discussion recently initiated by an international organisation about what could motivate Indian brands and retailers to make moves in the area of corporate responsibility, whether regulations needed to be tighter or whether it would be consumer pressure that would bring about a change. The underlying assumption – right or wrong – was that, as corporate entities, Indian retailers and brands were not sufficiently motivated to take significant and visible steps towards making their businesses more sustainable and socially responsible than their current state. The discussion was inconclusive, with many different, all potentially valid, points of view on the subject.
Very soon thereafter, I had the opportunity to participate in a dialogue with Gurcharan Das, the philosopher-author who, in his last corporate role, was Managing Director – Strategic Planning for Procter & Gamble worldwide. The dialogue primarily centred on his latest book: “The Difficulty of Being Good”. There was much debate and discussion on the wider consequence of individual actions and especially of those in positions of authority, highlighting the importance of individual choices.
A few days later, in a totally different context and with an entirely different person, the third incident occurred, when I was told an updated version of an old story to demonstrate the power of “a few good men” (and women). The story was as follows:
“50 people were travelling in a bus. Part-way through the journey, the weather suddenly turned stormy, with massive thunder and lightning bolts cracking all over the place. At times it seemed as if lightning would strike the bus and kill everyone on board. Then, someone proclaimed that there was someone on the bus whose end had come, who the lightning was seeking, and that it would be better for everyone else to get that person off the bus. The driver stopped the bus, and each person was sent off by turn, to go and touch a tree at a distance. 49 people got off the bus and returned unharmed after touching the tree. Then, as the last person got off and walked away from the bus, the bus was struck by a massive bolt of lightning.”
I thought this was a gruesome but effective moral science tale! During the next few hours I went about my activities, but kept mulling over the lesson(s) in that little story.
Then, that very afternoon, I got an email containing the following thought: “…when it looks like the whole place is going to implode – with pollution, disease, and war; famine, fatigue, and fright – there are still those who see the beauty. Who act with kindness. And who live with hope and gratitude. Actually, they carry the entire planet. (Mike Dooley)”
In looking back to the article 18-months ago, I closed the loop: it is the individual manager, who is also a citizen in a community, a consumer, and as a parent a stakeholder in future generations, who has to make the choices. His or her choices – both right and wrong – do have an impact beyond his or her own life and business. The so-called triple bottom line – profit, people (community) and planet (environment) – are irrelevant unless the first question is answered: “what does this mean for me?”
So as we go about our day, launching and growing brands, opening new stores, creating new products, I offer you this thought to reflect upon: are we carrying, or being carried? Is the bus safe because of us, or are we the ones the lightning is seeking?
[Go to the earlier post: “Corporate Responsibility – Beyond Babel“, December 2008]
Devangshu Dutta
May 11, 2010

REVIEW: BEATING THE COMMODITY TRAP: Richard D’Aveni (Harvard Business Press)
In his latest book, Professor Richard A. D’Aveni focusses on a topic that most businesses should be acutely concerned with: the problem of commoditization. In interviews he has accurately described commoditization as “the black plague on modern corporations” and “a deadly disease that’s spreading like crazy”.
Certainly, if one had to pick the ultimate nightmares to keep CEOs awake at night, commoditization would definitely be among the top of the list. Specifically, given the economic uncertainties around the world in the last couple of years, business leaders who are not concerned about their products or services being turned into commodities are either supremely equipped to maintain their differentiation, or immensely deluded as to their capabilities to fight market forces. Prof. D’Aveni suggests that maintaining differentiation alone is not enough to sustain business.
A product or service becomes a commodity when it is not distinguishable from competing offerings and therefore not valued above the competition. Prof. D’Aveni views commoditization along two key attributes: the benefits or features that are being offered and the price (margin) that is available to the business. Based on his model, he has identified three types of competitive stress that a business could face:
The book suggests competitive strategies that a business could take to avoid getting caught in the commodity trap. These strategies can be boiled down to the biological choice: fight or flight (escape). Professor D’Aveni echoes the basic warfare strategy laid out by many military and business strategists through the ages. He suggests that businesses need to gauge the opponents, choose their battles, and pick opponents against whom they can win. He also calls for pre-emptive action: where companies can, they should either change the business environment to avoid commodity battles entirely, or initiate the battle of commoditization and control its direction and momentum.
In fact, anticipation and pre-emption is the key to avoiding the commodity trap. To help with this, Prof. D’Aveni offers a relatively simple framework to analyse a current market situation in terms of a price-benefit matrix, and to identify the advance corrective actions to be taken.
The book is short and straight-forward enough to pick through a domestic flight, or to read in the back-seat during a long commute between office and home. The easy to understand framework gets the messages across quickly. In analysing the variations of commoditization, both in consumer and business oriented industries, the Professor also offers up something for everyone.
However, the book’s strengths also turn out to be among its biggest weaknesses. The book would have benefited from more depth to each of the concepts. Skipping quickly from one area to the other, in some places the book risks losing coherence of thought.
Some short books are like downhill hairpin bends on a mountain road; Prof. D’Aveni’s book is one of those. Much as you might be tempted to go fast, it’s advisable to go slow. If you speed through it, you might miss a nugget that actually makes sense to your business.
One of the other grouses I had was with the examples quoted. The predominantly US market examples reduce the book’s relevance for a global audience – the Professor presumes the reader will know the company and its context well enough to understand the lessons being discussed. In some cases the examples are incomplete and possibly even incorrect: one such is the example of Zara. The broad-brush attributes Zara’s business success to turning fashion into commodity, and ignores the fact that fashionability and desirability are a cornerstone of Zara’s offer, not the cheapest price. Others would possibly be far more accurate examples of commoditization in the context of price.
However, if you are sufficiently concerned about the possibility of being commoditized out of profitability, or being marginalised out of market share, I would suggest that you could easily overlook these flaws. The fundamental premise of the book is far too important to ignore. [Beating the Commodity Trap on Amazon]
(This review was written for Businessworld.)
Tarang Gautam Saxena
March 19, 2010
India has been consistently rated amongst the top destinations for consumer businesses year after year. While international fashion brands had earlier entered India at a steady pace, there was a greater surge of the global brands in the Indian market since 2002.
Interestingly many international brands opted to choose the franchise route for their entry into India. There were changes in the market environment and government policies that made the business environment favourable for growth through franchising.
Firstly, as a signatory of the WTO, India reduced import duties consistently. Consequently products could be sourced from other countries at more competitive prices and international brands could create an internationally-consistent product offering, with greater control on the supply chain.
Secondly, with more international brands vying for a share of consumer’s wallet, there was a need for brands to create a distinctive brand identity. Exclusive branded outlets increasingly became a marketing tool through which the brands could not only showcase a complete product range but also create the full brand experience.
Simultaneously the real estate market grew significantly, bringing in many “investors” who did not have the capability or the desire to develop their own brand. The availability of potential master franchises ready to invest capital and real estate created an environment conducive for growth of franchising.
As per Third Eyesight’s report (“Global Fashion Brands: Tryst with India”), by the end of 2008, just under half of the brands were present through a franchise or distribution relationship.

Unlike more developed markets where brands have sizable networks of large-format store as a launch and growth platform, in India there are still limited choices to simply “plug-and-play” using department stores or any other large-format retail network. Also, having a local partner as a franchisee provides a closer understanding of the market and the ability to adapt to changing consumer needs.
For a successful relationship it is vital that a franchisee should have an entrepreneurial mind-set. The essence of the brand needs be well understood, and the franchisee must have operational involvement rather than a “passive investment” approach.
The question is whether franchising would continue to remain the preferred entry mode as a new decade starts. Liberalisation of foreign investment norms has already led to many brands transitioning into a joint venture or subsidiaries. (See the more recent version of the report on International brands in India.)
However, while for many international brands it would be ideal to have ownership and control over the operations in a strategic market like India, direct investment does also increase their risk and the investment is not financial alone.
Therefore, for many brands, franchising would still remain the more practical choice whether by using a national master franchisee or using site-specific franchise relationships in combination with a direct wholesale presence in India.
Devangshu Dutta
February 28, 2010
Who knew that a mere vegetable – the humble purple, shiny brinjal, eggplant, aubergine – could create such an uproar?
And why retailers and consumer product companies should be concerned about genetically modified (GM) crops is a complicated story with multiple twists and turns across political, economic, social, scientific and philosophical landscapes.
At their basic level, brinjals have so far been possibly equally hated and loved for their flavour and texture across the world. But their newest avatar – Bt Brinjal – is now being viewed on the one hand as an evil alien transplant that will kill everything good and natural, and the first step of capitalist monopolies to dominate food crops in a large and growing market, while on the other hand it is seen as a saviour of the embattled farmer, an eco-friendly alternative to pesticides and a well-thought out scientific solution to agricultural productivity.
Though it might appear that genetically modification is a 20th century invention, the fact is that such food is not new. Since the time we began farming some 10,000 years ago, we have been carrying out genetic screening and selection, and modifying to create plants and animals that suit our purposes. All farmed products are a product of artificial rather than pure natural selection, as humans have pure-bred and cross-bred strains of crops that are seen as more beneficial in terms of nutrition, hardiness and ease of cultivation.
However, there are some important differences between earlier efforts and now, which underlie the recent loud and violent debate. Let me outline the concerns as seen from the anti-GM side of the table.
Previous genetic selections and modifications happened not just over generations of plants, but generations of human beings. By default, this allowed time to try and test different variants and arrive at varieties that met multiple criteria – profitable cultivation, nutrition, taste, durability and safety. There are concerns that not enough is known about the eventual impact of the new GM crops on human and environmental health, and the speed of adoption frightens people. (In 1948 a Swiss chemist was awarded the Nobel Prize for his work on DDT’s effectiveness as a pesticide, just a few short decades before it was banned from widespread agricultural use for – among other things – apparently causing cancer, and being acutely toxic to organisms other than the pests at which it was targeted.)
In the past, if some variety was wiped out due to climatic variation or pests, it was very likely that alternative varieties were close at hand to substitute it. (Estimates about the number of brinjal varieties in India alone vary widely, from 2,000 to over 3,500 though most of them are not actively cultivated in any significant number.) On the other hand the agricultural information and supply chain today is far more integrated, allowing a previously unknown speed and completeness of adoption of new technology and inputs, frequently at the cost of traditional knowledge. Extinction of natural species is not just due to hunting or disasters, whether man-made or natural. If a new engineered variety is profitable in the foreseeable future, farmers would very likely replace other varieties without examining the long-term impact. (This is true also of other inputs, like overuse of heavily promoted synthetic fertilisers or pesticides.)
Previous ‘engineering’ was restricted to pollination, grafting and selection, whereas now we are attempting to manipulate individual genes or sets of genes, and transplanting genes across species (from a bacterium in the case of Bt). This approach is similar to how we look at most things, today – individually, separate from or devoid of the natural context, ignoring any interaction with other elements (other genes, in the case of genetically modified crops). While in some cases there may be no significant impact on the outcome, our knowledge of genetics is far from complete and holistic to be able to confidently make the statement about no long-term harm.
All agriculture in the last 10,000 years was based on the assumption that future generations of the crop could be raised from seed saved from previous generations. Current genetically modified varieties, on the other hand, are seen as corporate intellectual property created with huge investments, where the return of investment is sought from fresh seed being sold by the company to the farmer for each planting. This is one of the most violently opposed aspects of GM crops, not just in developing economies like India but in developed economies such as the US as well.
I believe I’ve listed the major concerns of the anti-GM side of the debate above, with the rider that not everyone on the anti-GM side shares all the concerns equally.
Unfortunately, the debate is neither simple nor clear as emotions and stakes run high on both sides of the debate.
Pro-GM groups and individuals express the view that their opponents are stuck in the past and are standing the way of progress that is urgently needed to solve immediate human problems.
For one, proponents of genetic modification will point out that the humongous increase in human population needs new strains of crops that can grow more with fewer inputs in terms of water, fertilisers and pesticides. Without such crops, we run the risk of widespread food and water shortages around the world. ‘Green’ concerns may also be quoted in favour of GM crops. The argument is that using genetically modified crops would actually do less damage to the environment than conventional crops, for instance by needing lower doses of pesticide, or producing more crop from smaller patches of land.
Another concern quoted by the pro-GM group is that publicly funded organisations do not have the skills, the scale or the funding to undertake massive and rapid research for the breakthrough agricultural solutions needed in the short term, and that fundamental research needs to be carried out by commercial for-profit organisations. Obviously, as an outcome of that, the profit from the intellectual property needs to be protected such that it can provide adequate returns over a period of time.
For now, most governments (including in India) are playing it safe by maintaining the current status, and disallowing the introduction of GM crops, although there are opposing viewpoints even within each government.
As consumers, also, we could take the view, as many consumers are taking, that what exists (or what existed many years ago) is the best and safest option, since it is the most proven. We could give more muscle to producers and sellers of natural, organically grown varieties, by choosing to buy only such merchandise and rejecting GM foods completely.
I wish it was that simple.
I wish we could say that everything artificial is harmful and everything natural is beneficial. I wish we could blithely accepts labels such as ‘Franken-foods’ for genetically modified crops, treating them as a monster creation.
I wish we could say that one side or the other is adopting more robust scientific methods so that we can take clear and well-informed decisions.
As consumers, unfortunately for us, the truth is not so clear. There are pros and cons on both sides, which will get quoted in and out of context, to support different arguments, for and against genetic modifications.
More importantly, both for consumers and the industry, what is not clear is how complete separation of GM and non-GM products can be maintained. Once GM foods enter the supply chain, it is likely that they will mix with non-GM produce, whether at the farm, in storage or in processing. The current compliance standards in the global food sector offer no confidence that the non-GM and GM supply chains can be sealed off from each other and monitored separately, such that retailers and consumers can make their choice with complete confidence that they are buying what it says on the label.
In this case, more time, and a more robust and holistic investigation may be the only solution. The Environment Minister has asked us to ‘watch this space’.
Now what we end up with in terms of individual, social and economic health will depend on what kind of effort and intent goes into that space. Industry, consumers, scientists, farmers, and governments, all have a role to play in shaping that intent. We all choose whether we want the green organic genes – or the other kind, be they blue genes, purple or yellow.
admin
January 7, 2010
By Tarang Gautam Saxena, Chandni Jain and Neha Singhal
In Retrospect
While India was a promising market to many international brands, it was not completely immune from the global economic flu. More than its primary impact on the economy, the global downturn sobered the mood in the consumer market. Even the core target group for international brands, that had just begun to splurge apparently without guilt, tightened their purse strings and either down-traded or postponed their purchases.
In 2008 in the midst of economic downturn, skepticism and uncertainty, the international fashion brands had continued to enter India at nearly the same momentum as the previous year. Many international brands such as Cartier, Giorgio Armani, Kenzo and Prada entered India in 2008 targeting the luxury or premium segment. However, given the high import duties and high real estate costs, the products ended up being priced significantly higher than in other markets. Many players ended up discounting the goods heavily to promote sales while a few also gave up and closed shop.
As the Third Eyesight team had foreseen last year, 2009 saw a further slowdown and fewer international brands being launched during the year. The brands that were launched in 2009 included Beverly Hills Polo Club, Fruit of the Loom, Izod, Polo U.S., Mustang, Tie Rack and Timberland. Some of these had already been in the pipeline for quite some time and invested a considerable time and effort in understanding the dynamics of the Indian retail market, scouting for appropriate partners, building distribution relationships and tying up for retail space, setting up the supply chain and, most importantly, getting their operational team in place.
International Fashion Brands in India

After many deliberations, the well-known global brand Donna Karan New York set foot in the Indian market in 2009 through an agreement with DLF Brands to set up exclusive DKNY and DKNY Jeans stores India. The brand is also reported to have signed a worldwide licensing agreement with S Kumars Nationwide Ltd to design, manufacture and retail DKNY menswear in certain specific countries.
Second Chances
Amongst the international brands that have recently entered the Indian market, a few are on their second or even third attempt at the market.
For instance, Diesel BV initially signed a joint venture agreement in 2007 with Arvind Mills, and the partnership intended opening 15 stores by 2010. However, by the middle of 2008, the relationship ended with mutual consent, as Arvind reduced its emphasis on retailing international brands within the country. Within a few months of the ending of this relationship, Diesel signed a joint venture with Reliance Brands for a launch scheduled for 2010. Both partners seem to be strategically aligned with a common goal as the international iconic denim brand wants to take on the Indian market full throttle and the Indian counterpart has indicated that it wants to rapidly build its portfolio of Indian and foreign brands in the premium to luxury segments across apparel, footwear and lifestyle segments.
Similarly, Miss Sixty entered India in 2007 through a franchisee agreement with Indus Clothing. It switched to a joint venture with Reliance Brands in the same year but the partnership was called off in 2008, despite plans to open more than 50 stores in the first three years of operations. Miss Sixty has finally entered India through a franchise agreement with a manufacturer of women’s footwear and accessories. The company has currently introduced only shoes and accessories category and is looking at potential partners for its label Energie and girls’ range Killah.
Other brands that have re-entered the Indian market include Germany-based Lerros whose first presence in India was back in mid-1990s. The brand re-entered the market in 2008 through own brand stores and is growing its presence through this route as well as through multi-brand stores.
Oshkosh B’gosh is another brand that had entered India in mid 1990s, through a licensing agreement with Delhi based buying house, Elanco. The licensee found the childrenswear market hard to crack, and closed down. In 2008, Oshkosh re-entered the Indian market through a licensing partnership with Planet Retail and is now available through shop-in-shop counters at Debenhams stores. Reports suggest that it may consider setting up exclusive brand outlets.
During the turbulence of 2008 and 2009, a few brands also exited the market. Some of them were possibly due to misplaced expectations initially about the size of the market or about the pace of change in consumer buying habits. Others were due to a failure either on the part of the brand or its Indian partners (or both) to fully understand what needed to be done to be successful in the Indian market. Whatever the reason, the principals or their partners in the country decided that the business was under-performing against expectations and for the amount of effort and money being invested, and that it was better to pull the plug.
Some brands that have been pulled out of the Indian market during 2008 and 2009 include Dockers, Gas, Springfield and VNC (Vincci). Gas (Grotto SpA) is reported to remain interested in the market but has not found another partner after its deal with Raymond fell through in 2007 and all dozen of its standalone stores were shut down.
The Scottish brand Pringle and its Indian licensee did not renew their agreement upon its expiry. The Indian partner has reportedly signed an agreement to launch another international brand in India, while Pringle is said to be looking for new licensee.
The good news is that successful relationships outnumber every exit or break in relationship possibly by a factor of ten. Some of the brands that have sustained are among the early entrants having a presence in India since the late-1980s and 1990s or even earlier. These include Bata, Benetton, adidas, Reebok (now also owned by adidas), Levi Strauss and Pepe. Having grown very aggressively during 2006 and 2007 Reebok quickly became the largest apparel and footwear brand in India, while Benetton and Levi’s are expected to cross the $100-million mark for sales this year.
Entry Strategy & Recent Shifts
As envisaged in Third Eyesight’s report from a year ago, with changing market conditions and a growing confidence in the Indian market, there has been a shift among international brands in the choice of the launch vehicle. While franchising has been the preferred mode of market entry in the recent past for risk-averse brands, more brands today demonstrate a long-term commitment to the Indian market, and are choosing to exercise ownership through wholly or partially owned subsidiaries and through joint ventures.
In 2009, we have seen a noticeable shift in favour of joint-ventures as the choice for entry into the market. Even the brands already present are looking to modify the nature of their existing presence in India in order to exert more control over the retail operations, products, supply chain and marketing.
Current Operating Structure
(End 2009)
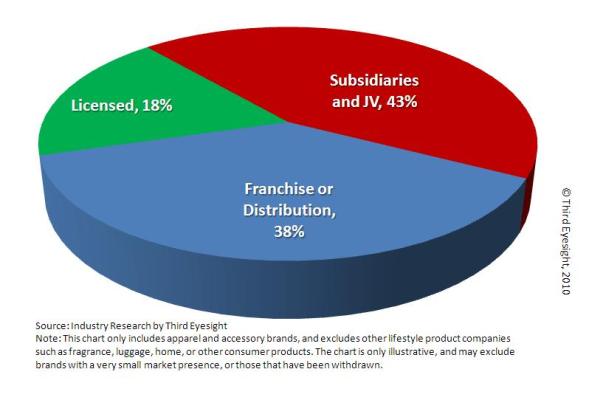
Brands that changed their operating structures and, in some cases partners, in recent years include VF (Wrangler, Lee etc.), Lee Cooper, Lee, and Louis Vuitton amongst others.
Mothercare, the baby product retailer, which is present through a franchise agreement with Shopper’s Stop has, in addition, recently formed a joint venture with DLF Brands Ltd to enable the expansion through stand-alone stores. Gucci, which had initially entered in 2006 with the Murjani Group as a franchisee, has recently changed over to Luxury Goods Retail, and is now in the process of restructuring the relationship into a joint venture.
VF has also been reported to be looking to license Nautica, Jansport and Kipling to a new partner. Until now, these brands were handled through the joint venture with Arvind Brands. Arvind has increasingly focused on its core business, closed stores and scaled down expansion plans for the international brands.
Burberry that had entered India in 2006 through a franchisee arrangement with Media Star opened two stores under this arrangement. It has now set up a new joint venture with Genesis Colors and plans to open 20 stores across the country.
More recently Esprit has also been reported to have approached Aditya Birla Nuvo to deepen its engagement by moving from its distribution arrangement into joint venture as the international brand sees excellent potential in the Indian market.
Buckling up for 2010
Throughout 2009, the one fact that became clear was that the Indian market was resilient. Now, as the global economic condition stabilizes, confidence levels of brands and retailers in India have also improved.
Several launches are already expected in 2010, and possibly many more are being worked upon. In the following 12 months, consumers can expect to find within India acclaimed brands such as Diesel, Topman, Topshop and the much-anticipated Zara. Many more Italian, British and French brands are examining the market.
Most of the international fashion brands already present in the market are also projecting a cautiously upbeat outlook in their plans, while a few are looking positively bullish.
For example, Pepe, an old player in premium and casual wear segment, has reported plans to grow its retail network further and open 50 more franchise stores by September 2010. Similarly the German fashion brand S. Oliver that entered the Indian market in 2007 is looking to grow significantly. It has already moved from a franchise arrangement with Orientcraft to a joint-venture with the same partner, and has stepped up its above-the-line marketing presence. The brand has recently reported its plans to scale up its retail presence to 77 stores by the end of 2012 while also strengthening its presence through shop-in-shop in multi-branded outlets in high potential markets.
Those international brands that have tasted success have not achieved it by blindly importing business models and formulas from other markets. Most have had to devise a different positioning from their home markets. Some have significantly corrected pricing and fine-tuned the product offering since they first launched. These include The Body Shop which decreased its prices by up to 30% this year, and Marks & Spencer which reduced prices by 20-40%. Others are unearthing new segments to grow into; for instance, Puma and Lacoste are now seriously targeting womenswear as a growth market.
On the operational side, the good news for retailers and brands is that the average real estate costs have reduced significantly, although marquee locations remain high. In several locations lease models have also moved from only fixed rent to some form of revenue sharing arrangement with the landlord. And, while the sector has seen some employee turmoil as many non-retail executives who came into the business in the last 5-7 years have returned to other sectors, employee salary expectations are also more realistic.
As customer footfall and conversions pick up, international brands are also shoring up their foundations for future expansion in terms of better processes and systems, closer understanding of the market, and nurturing talent within their team. Third Eyesight’s recent work with international brands’ business units in India highlights the international players’ concern with ensuring a consistent brand message, improved organizational capabilities right down to front-line staff, and focus on unit productivity (per store and per employee).
We may yet see a few more exits, and possibly some more relationships being reshuffled and partners being changed. However, all things considered, we can look forward to a net increase in the number of international brands in the country.
The Indian consumer is certainly demonstrating more optimism and as far as there are no major unforeseen global or domestic shocks, this optimism should translate into a healthier business outlook for international brands as well. According to early signs, 2010 could be an excellent curtain-raiser for a new decade of growth for international fashion brands in India.
[The 2009 report is available here: “International Fashion Brands – India Entry Strategies”]
(c) 2010, Third Eyesight
[Note: This report is based on information collected from a combination of public as well as proprietary sources, and in some cases may differ from press reports. However, no confidential information has been shared in this report.]
