
admin
July 20, 2024

Gargi Sarkar, Inc42
20 July 2024
The Indian government’s ban on Chinese apps and products in 2020 saw two massive casualties. Everyone knows about TikTok, but fast fashion brand Shein was equally as big in India four years ago.
But the India setback did not halt Shein’s global momentum, just as it did not stop TikTok from becoming what it is today. Shein became the world’s largest online-only fashion company in 2022.
Valued at a staggering $10 Bn, the brand accounted for nearly one-fifth of the global fast-fashion market in 2022, outpacing giants such as Zara and H&M. To put things in context, Shein was founded in 2008, whereas Zara was incorporated in 1975 and H&M in 1947.
In India, Shein set the market on fire. Launched in India in 2018, the brand was already a major player by 2020, dominating online searches and influencer-led content. But the ban in 2020 meant all that came to a halt.
The Indian government’s ban stemmed from fears of Shein’s Chinese parent company storing or transferring data of Indian customers to China. While the ban itself came under a tense geopolitical climate, one could say that Shein’s exit left a gap in India’s fashion market which D2C brands quickly filled.
Brands such as Urbanic, Twenty Dresses, Cilory, attempted to fill the void but couldn’t quite match Shein’s popularity. Indeed, VCs also backed fast fashion and casual wear startups such as The Souled Store, Virgio, NewMe and others which looked to replicate the Shein formula.
Ecommerce unicorn Meesho has also looked to fill the gap with affordable fashion and a similar content-led sales strategy that worked wonders for Shein.
While many of these brands have grown in scale over the past four years, none of them — at least so far — have quite replicated the magic of Shein and how quickly it disrupted the market.
And that’s arguably why Shein’s re-entry into India through a partnership with Reliance Retail is a big deal.
Shein joins the Mukesh Ambani-led conglomerate’s exclusive portfolio of over 50 brands, including Silk Feet, Jivers, Xlerate, Feet Up, Dhuni by Avaasa, Riva, John Player Select, Kidlyboo, and Altair. Besides this, Reliance Retail has similar deals with designer labels such as Kenzo, Y3, Marc Jacobs, Coach, Steve Madden, Kate Spade, among others.
It’s clear why Shein has looked to re-enter India, where the fast fashion industry is projected to reach a size of $30 Bn by FY23, as per a Redseer report. The overall fashion segment grew at a modest 6% YoY in FY24, whereas the fast fashion subsegment surged by up to 40% in the same period. Now, Shein is back to grab a large chunk of the market once again, though there’s definitely a lot different about this Shein.
Reliance Punches Shein’s Ticket To India
The first thing that we need to note is that Shein is not back as a standalone entity, but its products will be available on Reliance Retail’s apps and physical stores. Shein is not operating business in India — Reliance is said to be bringing in former Meta director Manish Chopra to lead the brand.
Shein’s parent entity will receive a licence fee as a share of profits generated solely within India. The operations will be managed by a company wholly owned by Reliance Retail. Crucially, all data and the app itself will be hosted and stored within India, ensuring that Shein has no access to or control over this data.
These are some of the key factors behind Shein’s comeback to India being approved by the government nearly one year ago.
Reliance Retail is set to launch the Chinese fast-fashion label Shein within the coming weeks. Further, to diversify its supply chain and promote domestic industries, Shein reportedly will be sourcing goods from India for its global operation in the Middle East and other markets.
More than anything else, fast fashion brands and indeed other some of the more premium brands need to worry about the Reliance factor. Shein’s brand name and Reliance’s massive resource base are a deadly combo.
Reliance Retail’s fashion ecommerce app Ajio directly competes with Myntra, Nykaa Fashion, Meesho, Amazon India, Flipkart, Tata Cliq, and other platforms. From a distribution point of view, Ajio will be the exclusive storefront for Shein, and exclusivity is a big deal in fashion ecommerce.
Ajio commands around 30% market share based on monthly active users (MAUs), data sourced from AllianceBernstein shows.
Flipkart Group’s Myntra maintains the highest market share in terms of active users, surpassing 50%. However, the report notes a decrease in transaction frequency, with Myntra’s GMV growing only 12% in FY23 compared to 35% in FY22.

“Shein’s re-entry may have a somewhat negative impact on Nykaa Fashion, as Nykaa primarily targets the premium fashion segment. In contrast, Myntra caters to both the mass and premium fashion markets and already has strong brand recognition in the fashion industry. Therefore, the impact on Myntra might be mild, whereas Nykaa Fashion could feel more significant effects,” Karan Taurani, SVP, at Elara Capital said.
He added that Shein is part of a broader strategy by Reliance Retail to expand its portfolio of brands. In that sense, Shein is just another addition to its portfolio.
A Myntra executive admitted to Inc42 that Ajio has an edge when it comes to exclusivity, but added that Myntra has also introduced Gen Z-focussed features which are gaining fast traction. Myntra’s focus on in-house brands or private labels is paying off, however, at the same time, the company is also looking to snap up more exclusive brand partnerships.
Should D2C Brands Worry?
One thing that Ajio cannot afford to do is give Shein more prominence. Fashion ecommerce marketplaces are quick to see gaps in terms of sales of particular brands and look to woo them to their side. In this regard, Shein will be competing with a number of D2C brands as well as international labels in fast fashion.
As per Inc42 data, between 2018 and 2023, D2C fashion brands captured almost 93% of the total funding raised in the Indian fashion ecommerce space.
The Myntra executive quoted above believes that Shein will definitely disrupt D2C fashion brands in India as many of them target the Gen Z audience, but they are also looking to protect margins and break into the premium segment.
The D2C landscape in fashion includes the likes of Andamen, House Of Rare, Bombay Shirt Company, Snitch, Damensch, The Souled Store among others. And there are houses of brands such as Mensa Brands, TMRW and others which combined have dozens of brands across categories in fashion. It’s not easy to stand out, and Shein will have to fight for its space on the aisles.
Most of these brands are looking to widen their net margins by adding premium products. Premiumisation is a major thesis among Indian D2C brands right now as they realise many of them are targeting a very limited cream of the market.
On the other hand, Shein has built its reputation on affordability. So is Shein actually directly competing with these players? Market experts believe that Shein is not successful just because of its pricing, but its use of data.
“Brands with the right product and high-quality service should attract customers who are not price-sensitive. A price-oriented brand is not a major threat; the real risk is if your product fails to keep up with market trends. Fashion-driven brands could take your business away if your product quality and service do not meet customer expectations. However, if your product is trendy, the quality is high, and your service is good, you should be safe in retaining customers who are not focused on price,” Devangshu Dutta, founder and CEO of Third Eyesight, said.
Those in the industry do believe that one brand cannot conquer the fashion market. That simply does not happen with the fashion industry, which is why there is so much depth in the market. Shein’s success will lead to the emergence of more D2C brands that look to mimic the data-led, trend-first model.
“The potential of the Indian market is evident, and it’s becoming increasingly exciting. This means that many companies will emerge in this category to serve this customer base. It validates the hypothesis we had two and a half years ago: the Indian consumer is evolving, and fashion should evolve along with them. From that perspective, Shein’s entry justifies and validates our hypothesis,” the founder of a Bengaluru-based GenZ-focussed fashion brand said.
Good brands always emerge from intense competitive churn, and Indian brands have the potential to go global if they hit it big. “Competing against Shein and building a successful business will open new opportunities for us and strengthen our execution and agility,” the founded quoted above added.
Is Shein Ready For Second Innings?
Now, coming back to Shein, it remains to be seen if it will be able to gain popularity like its first stint in India. One must remember that Shein tried to make a comeback in India in 2021 after the government’s ban through ecommerce giant Amazon, but the brand supposedly did not get much traction.
“I think the case of visibility is different when comparing Amazon and Reliance Retail. Through Reliance Retail, the visibility could be much higher compared to Amazon because Reliance Retail already has a very wide portfolio of fashion brands, including more than 25-30 luxury brands across various categories. It’s all about creating visibility, generating buzz, and going to market together in terms of marketing efforts. Reliance has a very strong omnichannel presence, both online and offline,” Elara Capital’s Taurani said.
While Amazon is, of course, a large ecommerce phenomenon, the platform is not a primary port-of-call for online fashion shoppers. This is why Shein could potentially perform better with Reliance Retail.
“We have to wait and see how Shein performs in India. We will need to observe how this unfolds to comment on its visibility and performance, both online and offline. In marketplaces, brands compete daily, and Shein’s strength has always been its designs. We’ll have to closely watch how Reliance leverages this strength,” an industry analyst said.
(Published on Inc42)
admin
May 8, 2024
At the recent Phygital Retail Convention in Mumbai, Devangshu Dutta anchored an engaging “Fireside Chat” with Bhavana Jaiswal of IKEA India and Kapil Makhija of Unicommerce , on retailers engaging with their customers across channels and formats, and the opportunities as well as challenges in managing experiences seamlessly across online and offline interfaces.
Watch the video at this link:
admin
March 18, 2024

Christina Moniz, Financial Express
March 18, 2024
It is not difficult to understand why e-commerce firm Flipkart wants a bite of the Q-commerce pie.
India’s quick commerce market has been growing year-on-year at 77% to reach $2.8 billion in GMV (gross merchandise value) in 2023, according to a Redseer report. In comparison, e-commerce has been growing at 14-15% year-on-year. No one would dispute that with instant deliveries of products and groceries in 10-20 minutes, quick commerce firms like the Zomato-owned Blinkit, Zepto and Swiggy Instamart have changed the face of e-commerce and retail over the past few years.
While quick commerce thrives, none of the players in this ring are profitable yet. According to Devangshu Dutta, CEO at Third Eyesight, most quick commerce firms are in an expensive market acquisition phase and are at least a year away from profitability — perhaps longer. He expects that the unit economics for these companies will improve. “Some of the quick commerce players have created a substantial consumer base, which is growing in the frequency of transactions, moving to higher order values and transacting more products with potentially better margins,” says Dutta.
Both Zepto and Blinkit expect to turn profitable in FY25, as per their public statements.
So what are the primary challenges? “Traditional large e-commerce players face obstacles in facilitating last-mile deliveries, establishing dark stores, managing supply chains effectively, and navigating fierce market competition,” says Anshul Garg, managing partner & head, Publicis Commerce India.
The other key challenge for the late entrants is that customers seldom switch platforms. This is different from the way customers shop for products like electronics on e-commerce, where they compare prices/ deals across multiple e-commerce marketplaces. Brands like Flipkart need to define their playbook by maybe exploring categories other than grocery if they are to make a dent in this market.
As things stand, quick commerce has a mere 7% of the potential market. The total addressable market is estimated at $45 billion, higher than food delivery, as per JM Financial. Blinkit leads the market with a 46% share, followed by Swiggy Instamart at 27%, and Zepto at 21%.
Growing-up pangs
Kushal Bhatnagar, associate partner at Redseer Strategy Consultants, explains that there are broadly three ways that Q-commerce firms are working towards profitability. The first is by pushing higher priced items on their platforms and bumping up higher average order values. They’re also foraying into non-grocery segments such as cosmetics and headphones.
The other lever is ensuring dark store efficiencies. “While dark stores are an added cost, most platforms have a solid understanding of the demand across micro markets and are able to extract better profitability from each dark store. So the trend is positive, even if profitability is still to be achieved,” explains Bhatnagar.
For a dark store to deliver ROI and become profitable, it needs to cross 1,200-1,300 daily orders.
Some players like Zepto are also experimenting with a nominal platform fee of Rs. 2 per order, which they sometimes increase during peak times — by up to Rs. 10 — to gain from a surge in demand. Some are also implementing 12-15% fees for orders under Rs. 500, nudging customers to spend more.
Ad revenue is another important lever driving growth for these platforms, especially as D2C brands hop on board and advertise on them to reach GenZ and millennial consumers in metros and tier-I markets. Advertising revenue is around 3% of a platform’s GMV, and it is expected to keep growing.
FMCG and F&B are the top advertising categories on quick commerce currently but that can change as platforms move into higher value categories. “Quick commerce is also venturing into unconventional categories such as electronics, mobile and large appliances. If all goes according to plan, we can anticipate a significant shift in advertising contribution, given that these categories boast higher average selling prices, prompting advertisers to adopt a slightly more aggressive stance,” says Shashank Rathore, vice-president, e-commerce at Interactive Avenues (IPG Mediabrands India).
(Published in Financial Express)
admin
February 21, 2024
The ability of fashion businesses to endure and thrive in the face of stiff competition and changing market dynamics is all about adapting to innovation, customer-centricity, and strategic planning. The correlation between high performing fashion business and product innovation is undeniable.
This panel discussion brings Design and Business Heads together to brainstorm on how fashion companies can devise strategies to drive innovation to remain competitive, meet evolving consumer expectations, and stay ahead of the race.
Moderator: Devangshu Dutta, Founder & Chief Executive, Third Eyesight
Panelists:
admin
February 21, 2024
Published in ETPrime, 21 February 2024
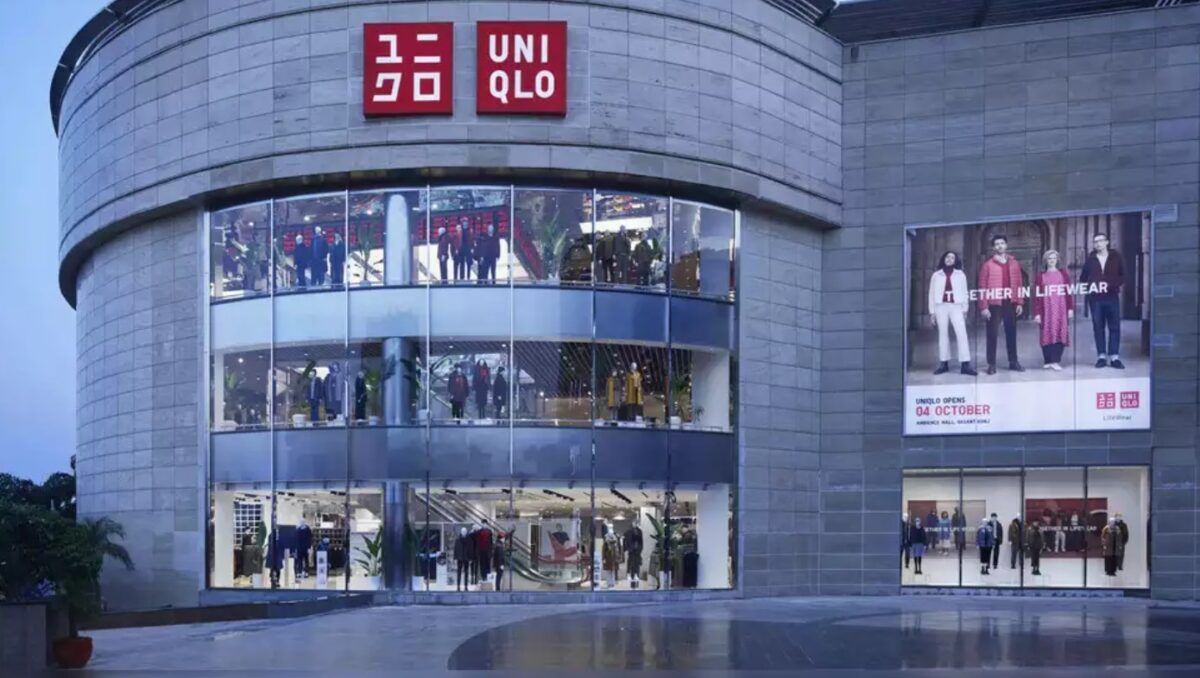
Around two years ago, when Delhi-based Debabrata Bhattacherjee decided to explore a new brand for casual wear, he decided to give Uniqlo a try. The 27-year-old was so impressed by the quality that he became a regular customer of the Japanese fashion brand that had set foot in India in 2019.
“What first attracted me was the convenient design of their store, which was very organised and clean. Very Japanese, to say! The shopping experience is very hassle-free and offers a lot of options. Their clothes are very comfortable and the quality is excellent,” said Bhattacherjee, a video producer. Though the brand is costlier than others, he is okay paying the premium.
Bhattacherjee is among the many Indians who have contributed to the rising sales of Uniqlo. Also known to be Asia’s biggest clothing brand, the Japanese company posted a 69% jump in sales in FY23 from FY22, with a net revenue of Rs 624.6 crore and a net profit of Rs 68.38 crore in India.
Uniqlo is among a bunch of Japanese and South Korean brands that have, in the past couple of years, been gaining more space in the lifestyle and beauty product shelves of Indians. Wacoal, MUJI, Innisfree, Sulwhasoo and Amorepacific have been witnessing a relatively quiet but consistent growth in sales in the country.
East Asian portfolio
Indian consumers are not new to the products from these countries. A popular example is automobiles: Suzuki, Hyundai, Toyota and Honda have made millions of Indians mobile. Now, fashion and lifestyle products from East Asia are also now becoming part of Indian households.
Anand Ramanathan, Partner and Leader-Consumer Products and Retail, Deloitte India, said this is because these brands have built a reputation for quality, design and durability — much like their peers in automobiles and engineering.
East Asian lifestyle and beauty brands initially had an influence in the Northeastern states, where the customers are not only ahead of the curve in fashionability but also found resonance with the look of these brands, said Devangshu Dutta, founder and CEO of management consulting firm Third Eyesight. “In due course, K-dramas and K-pop (Korean popular culture) has boosted their expansion across the country. Japan and Korea are highly developed beauty and skincare markets, with customers who are conscious both about their appearance, as well as about the products’ performance. These brands have established brand equity across markets on their quality, innovation, and product development,” he said.
Indians have been enjoying the “Korean wave” or Haalyu, which refers to the global popularity of Korean culture, music, movies, and TV dramas. Ramanathan pointed out that Korean has emerged as the most learnt language among the 13-22 age group in India. Apart from fashion, he said, the cultural impact can be seen in food and jewellery options of Indian Gen Z and millennials.
Well-travelled Indians who have been exposed to these brands find the pricing has “value” implicitly built in, Dutta added.
Companies from these countries also seem to find value in India. A 2023 survey by the Japan Bank for International Cooperation (JBIC) that collected responses from over 500 manufacturers in the island country showed that 48.6% of the companies considered India a key destination for medium-term business growth. Ramanthan cited a report by DPIIT that stated that since 2000, South Korea has invested $5.7 billion in India across various sectors. Recently, South Korea has invested $400 million in India during July 2022 to June 2023.
E-commerce is a driver
Another brand on this list is Japan-based Wacoal. The lingerie maker entered India in 2015 with its first store in Mumbai, and has posted an impressive 3X year-on-year increase over the last eight years, said Pooja Merani, COO of Wacoal India.
This was because its products have adapted designs that align with the preferences of the Indian market, demonstrating cultural sensitivity, she said. The company measures the physique of approximately 1,000 women and girls between the ages of 4 and 69 every year, said Merani. This has helped it make clothes that suit Indians well. “Prioritising fit and comfort in the offerings, and understanding the diverse body types in India, have likely contributed to customer satisfaction and loyalty,” she said.
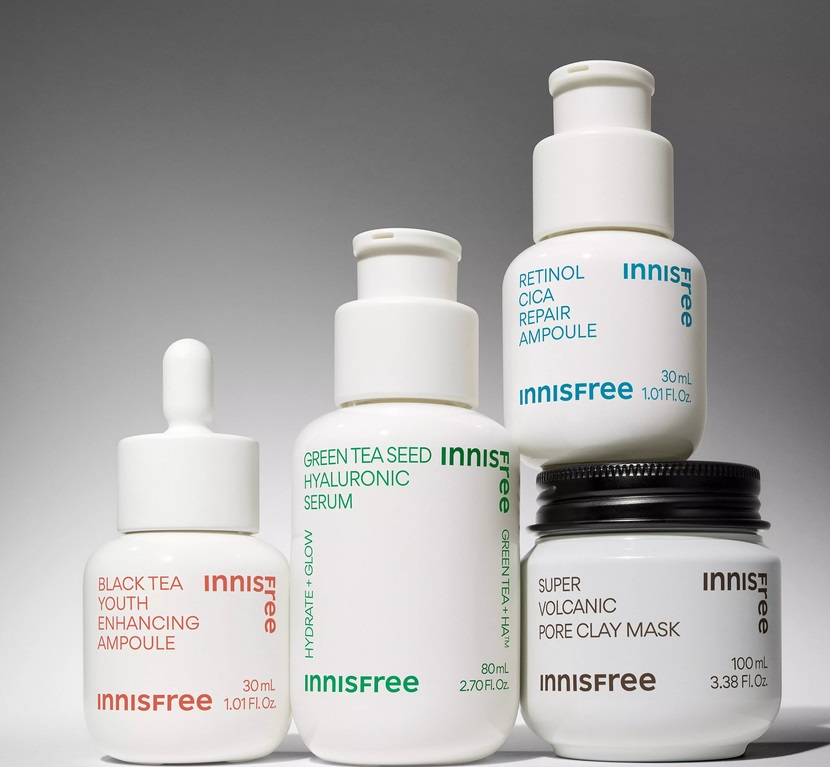
South Korean beauty firm Amorepacific, which is the parent company of popular cosmetic brands such as Innisfree and Sulwhasoo, said they are seeing traction in India as the beauty and wellness industry is experiencing robust growth. “There is an increasing awareness and emphasis on skincare, with consumers seeking effective and high-quality products. India has a large and youthful population, and the youth are often early adopters of beauty trends. Korean skincare products, with their trendy packaging, innovative formulations, and youthful image, can resonate well with this demographic,” said Mini Sood Banerjee, Assistant Director and Head of Marketing at Amorepacific Group.
The company had last year signed an agreement with Reliance Retail to sell through its online fashion platform, Tira. Banerjee said 80% of its sales are through e-commerce. “INNISFREE has been engaging with the Indian consumer much more rapidly in the online space.”
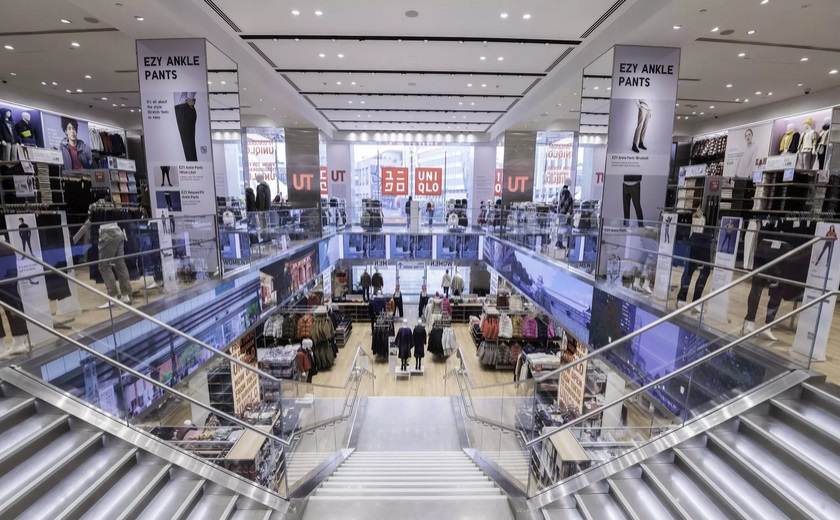
Uniqlo attributed its success to its blend of Japanese philosophy with Indian culture — the company started selling kurtas from 2019, when it had entered India through Delhi. A spokesperson credited the brand’s success to the 13 brick-and-mortar stores in India focussing on its “LifeWear” philosophy. “It is simple, high-quality, everyday clothing with a practical sense of beauty that is ingenious in detail. This approach originates from the Japanese values of simplicity, quality and longevity — and we have seen that Indians appreciate the high level of quality of our apparel,” the spokesperson said.
Making in India
These companies have also started production in India, a sign that they find the market promising.
Wacoal started its production in India last year, and is expanding into newer segments. The Uniqlo spokesperson said the company is on track to achieve 30% domestic sourcing. “We are actively growing local suppliers to deliver quality products for our customers. For example, we now work with 17 sewing factories and 6 fabric mills in India.”
Fashion, home textiles and other home products are potentially the first categories where manufacturing within India can be explored, said Third Eyesight’s Dutta. Brands with a large global footprint and established supply chains find it difficult to shift manufacturing bases.
“To make a shift to India, a substantial volume of demand needs to be generated within the country, and brands also need to be actively looking to diversify from their existing supply bases. Fashion brands and retailers with product lines that are relatively less technical or complex, or for which the size of economically viable production base is relatively small, are already looking at manufacturing more products and greater volumes in India,” he said.
Foreign brands have to find the product-market fit to be successful in a country. India being an ethnically diverse market, the product-market fit can be dissimilar across the country. Brands can be successful only if they can address specific segments and build the business accordingly, Dutta added.
Companies like Wacoal said they are mindful of the cultural challenges. Merani pointed out how the lingerie market is predominantly unorganised and has challenges such as limited awareness about proper sizing and cultural taboos. “Overcoming traditional industry norms and promoting accurate sizing awareness remains a persistent hurdle for us. Additionally, addressing diverse body types while ensuring top-notch quality further adds complexity,” she said.
‘Affluent India’
Despite the challenges and the steep pricing, experts said these brands are becoming popular as Indians have more disposable income.
According to a recent Goldman Sachs report that corroborated data using tax filings, bank deposits, credit cards and broadband connections, the affluent Indian consumer cohort has grown at a compound annual growth rate (CAGR) of over 12% in 2019-23, compared to 1% CAGR in India’s population. Rising retail participation has lifted India market cap over 80%, it pointed out. “The largest beneficiary of rising ‘affluent India’ are categories such as leisure, jewellery, out-of-home food and healthcare, and premium brands within all categories,” it added.
The willingness of Indian customers to pay a premium price for better quality products depends on factors such as product category, brand reputation, target demographic and economic conditions, said Amorepacific’s Sood.
For Japanese brands, the shift in India from electronics and automobiles to clothing and lifestyle is driven by strategic diversification and changing consumer trends. Japanese companies are leveraging globalisation and the increasing exposure of Indian consumers to international lifestyles, said Wacoal’s Merani.
“Economic factors, such as India’s growing middle-class population and economic growth, contribute to the attractiveness of the market. Thorough market research and understanding of local preferences, along with collaborations and partnerships, enable Japanese brands to align their products with the specific demands of the Indian consumer market. Overall, this shift reflects the adaptability and strategic decision-making of Japanese brands, indicating their confidence in the potential for success in diverse sectors beyond automobiles,” she said.
The Indian market still has legs.
The COO of Wacoal India said the lingerie market, for one, would grow by a CAGR of 9.3%, especially as more young women join the workforce.
India presents a great opportunity as a strong growing market. Even domestic brands are competing for “share-of-mind, shelf-space and share-of-wallet, and some larger Indian corporates are also backing their own brands and retail formats with strong investments,” added Third Eyesight’s Dutta.
If the Japanese and Korean brands want to survive, they would need to keep innovating and adapting to consumer preference. For Indians, meanwhile, it is “ache din” when it comes to shopping.
